

|
시장보고서
상품코드
2121739
현미경 기기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Microscopy Device - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
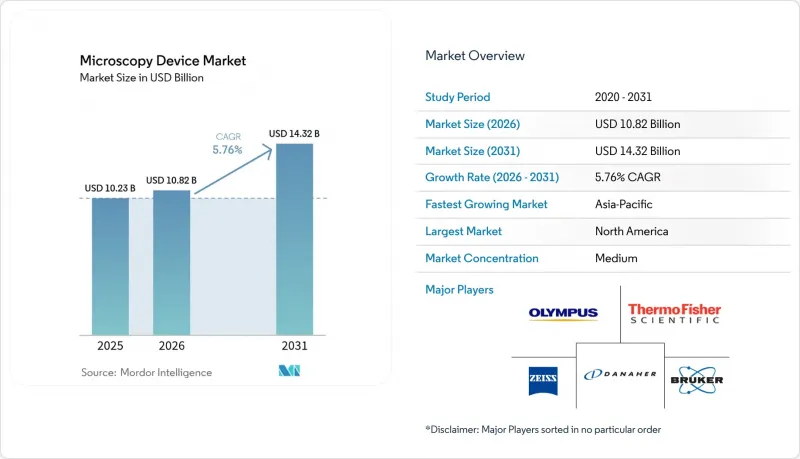
에 따르면 현미경 기기 시장 규모는 2025년에 102억 3,000만 달러, 2026년에 108억 2,000만 달러에 달하며, 2031년까지 143억 2,000만 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 5.76%로 성장할 것으로 전망되고 있습니다.
이 보고서는 현미경 유형(전자현미경, 광학현미경, 주사형 프로브 현미경, 기타), 용도(나노테크놀러지 연구, 생명과학, 반도체·전자, 기타), 최종사용자(병원·클리닉·검사 기관, 기타),지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 현미경 기기 시장의 동향 및 인사이트
초고해상도 광학 및 양자 센싱 분야의 기술 발전
STED, SIM, PALM 등의 초해상도 기술은 회절의 한계를 극복하여 50nm 이하의 구조를 가시화하고 있습니다. 이를 통해 연구 기관들이 생체 시스템내 단백질 간의 상호작용을 정량화하려는 노력을 기울이는 가운데, 단일 세포 연구 및 신경퇴행성 질환 연구가 강화되고 있습니다. 조기 도입자들은 다이아몬드 내의 질소 공석(NV) 센터를 이용한 양자 센싱 기술을 결합하여, 자기장 영상화, 반도체 웨이퍼의 나노 스케일 결함 탐지, 생물물리학 분야의 단일 분자 현상 포착을 수행하고 있습니다. 현미경 기기 시장은 처리량을 극대화하기 위해 동일한 워크플로우 내에서 광시야, 공초점, 초해상도 모드를 전환할 수 있는 하이브리드 플랫폼을 찾는 구매자들로 인해 호황을 누리고 있습니다. 북미와 유럽의 학술 컨소시엄 및 제약 기업이 대상의 타당성 확인 및 하이컨텐츠 스크리닝과 같은 파이프라인의 필요성에 따라 구매를 주도하고 있습니다. 광학 정렬의 복잡성과 특정 형광 염료에 대한 의존성이 여전히 일상적인 임상 활용을 방해하고 있으며, 포괄적인 용도 지원을 제공하는 공급업체에게는 서비스 및 교육 기회가 창출되고 있습니다.
AI를 활용한 자동 디지털 병리 도입
병리 네트워크는 수동 현미경 검사에서 조직 분류, 바이오마커 정량화, 이상 부위 표시를 수행하는 컨볼루션 신경망과 결합된 전체 슬라이드 이미징으로 전환되고 있으며, 현재 일부 모델은 신뢰할 수 있는 그라운드 트루스가 있는 적응증에서 95%를 넘는 민감도를 보이고 있습니다. 2026년 1월, 인도 중앙 누에 사육 위원회는 농업 종사자들이 누에 대한 질병을 조기에 탐지할 수 있도록 지원하는 AI 탑재 현미경 사업을 강조했습니다. 이는 응용 AI 현미경 기술이 임상 현장을 넘어 생산 환경으로 확대되고 있음을 보여줍니다. 종양 미세환경 분석에는 기가픽셀 규모의 전체 이미지에 걸친 면역 침윤 및 혈관 구조의 정량화가 필요하므로 종양학 부문의 워크로드가 추진력이 되고 있습니다. 유럽연합(EU)의 ‘체외진단용 의료기기 규정’은 AI 기반 진단 소프트웨어에 대해 CE 마크 획득을 의무화하고 있으며, 각 벤더는 모델의 성능을 임상 종점(endpoint)과 일치시키기 위해 전향적 임상 검증 시험을 실시해야 합니다. 병원과 진단 실험실은 병리 전문의 인력 부족과 의료의 편차를 줄이기 위한 다기관 간 소견 해석의 표준화 필요성에 힘입어, 2031년까지 연평균 성장률(CAGR) 6.60%를 기록하며 최종사용자 부문 중 가장 빠르게 성장하고 있습니다.
장비의 높은 초기 투자 비용 및 운영 비용
시설, 차폐, 진동 격리를 포함할 경우, 고급 극저온 전자현미경(cryo-EM) 시스템의 초기 비용은 여전히 500만-700만 달러 범위이며, 이로 인해 공동 보조금에 의존하는 많은 기관에서 도입이 지연되고 있습니다. 수차 보정형 투과형 전자현미경(TEM)의 연간 운영비는 유지보수, 극저온 냉각제, 클린룸의 공과금을 포함해 20만 달러에 달할 수 있으며, 장비에 대한 일부 보조금이 지원되더라도 더 광범위한 도입을 저해하고 있습니다. 시설 공유나 임대 모델은 이러한 장벽을 완화하지만, 일정 조정, 유지보수 기간, 가동 시간의 변동으로 인해 여러 기관에서 이용하려면 추가적인 조정 비용이 발생합니다. 병원이나 진단 실험실의 경우, 처리 능력 향상이나 표준화를 통한 명확한 비즈니스 사례가 제시되어 있더라도 예산 상한선으로 인해 디지털 병리학의 도입이 지연되고 있습니다. 현미경 기기 시장은 신흥 경제국에서 이러한 자본적 제약을 반영하고 있으며, 환율 리스크와 수입 관세가 고가 장비 구매에 추가적인 역풍을 가져오고 있습니다.
부문 분석
전자현미경 시장은 소형 극저온 전자현미경(cryo-EM) 시스템에 힘입어 2026-2031년까지 연평균 6.56% 성장할 것으로 예측되며, 전체 현미경 기기 시장보다 빠른 속도로 확대될 것으로 전망됩니다. 구조 기반 신약 개발 워크플로우에서 반복 주기를 단축하기 위해 더 높은 처리량과 시료 전처리 및 데이터 처리의 현장 관리가 요구됨에 따라 도입이 확대될 것입니다. 이와 병행하여 반도체 팹에서는 2nm급 노드에서 광학 계측으로는 확인할 수 없는 나노시트 스택,스페이서, 숨겨진 결함을 검사하기 위해 TEM과 SEM의 대수를 늘리고 있습니다. 수차 보정 광학계와 첨단 검출기는 로직 및 메모리의 양산 확대에 있으며, 격자 변형 매핑이나 원자 열 분해능을 실현하는 데 여전히 차별화 요인으로 작용하고 있습니다. 팹이 계측 분야에서 더 높은 통계적 커버리지와 신뢰성을 추구하는 가운데, 이러한 요인들로 인해 전자현미경 플랫폼은 공정 개발과 고장 분석 두 부문 모두에서 더 큰 역할을 담당하게 되었습니다.
광학 현미경은 사용 편의성과 낮은 서비스 비용을 중시하는 임상 워크플로우, 교육용 실험실, 품질관리 환경에서 널리 보급되며, 2025년에는 현미경 기기 시장 점유율의 41.80%를 차지했습니다.
지역별 분석
2025년, 북미는 현미경 기기 시장 점유율의 39.25%를 차지했습니다. 이는 제약 산업의 연구개발, 학술연구 성과, 반도체에 대한 투자가 광학 현미경과 전자현미경 플랫폼의 지속적인 조달을 지원했기 때문입니다. ‘CHIPS and Science Act’는 제조 인센티브 및 연구 프로그램에 527억 달러를 배정하고 있으며, 이로 인해 애리조나주와 오하이오주에서 신규 생산 라인을 건설 중인 인텔(Intel) 및 기타 기업의 첨단 계측 장비에 대한 수요가 증가하고 있습니다. 미국과 캐나다의 대학 연구실에서는 2025년에 확충된 국가 프로그램의 지원을 받아 저온 전자현미경(cryo-EM) 및 초고해상도 시스템을 계속해서 도입하고 있습니다. 여기에는 연구 인프라에 4억 5,000만 캐나다 달러(3억 3,500만 달러)를 배정한 캐나다의 ‘전략적 혁신 기금’도 포함됩니다. 이러한 요인들로 인해 안정적인 교체 주기가 유지되고 있는 한편, 병원들이 디지털 병리학을 확대하고 네트워크 전반에 걸쳐 표준화를 추진함에 따라 신규 구매자가 증가하고 있습니다. 북미의 현미경 기기 시장은 견고한 서비스 생태계와 공급업체의 존재감으로부터도 혜택을 받고 있으며, 이로 인해 규제 대상 워크플로우에 대한 교육 및 검증이 가속화되고 있습니다.
유럽에서는 공공 자금과 임상 검증 및 지속가능성을 중시하는 조화로운 규제에 의해 형성된 성숙한 도입 기반이 유지되고 있습니다. ‘호라이즌 유럽(Horizon Europe)’은 2027년까지 연구 혁신을 위해 955억 유로(1,020억 달러)를 지원하겠다고 약속했으며, 포토닉스와 나노의학에 특화된 프로그램이 대학 및 임상 센터의 하이엔드 이미징 플랫폼 조달을 지속적으로 지원하고 있습니다.
아시아태평양은 여전히 가장 빠르게 성장하는 지역으로, 연평균 성장률(CAGR)은 6.74%로 예측됩니다. 현미경 기기 시장은 국내 반도체 및 생명과학 부문의 역량 강화를 우선시하는 정부 프로그램과 연계되어 있습니다. 중국의 정책 지원에 힘입어 현지 연구 센터와 산업 연구소는 로직, 메모리, 첨단 소재용 전자현미경 플랫폼 도입을 확대하고 있으며, 그 결과 TEM, SEM 및 관련 액세서리에 대한 안정적인 수주가 창출되고 있습니다. 이러한 주요 지역 이외에는 중동 및 아프리카가 다각화 전략의 일환으로 연구 인프라 확충을 추진하고 있습니다. 한편, 라틴아메리카에서는 활발한 연구 커뮤니티가 존재하지만, 예산상의 문제로 인해 단기적인 성장은 제한될 전망입니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.03According to Mordor Intelligence, the microscopy device market size is projected to be USD 10.23 billion in 2025, USD 10.82 billion in 2026, and reach USD 14.32 billion by 2031, growing at a CAGR of 5.76% from 2026 to 2031.
This report is Segmented by Microscopy Type (Electron Microscopy, Optical Microscopy, Scanning Probe Microscopy, Other Technologies), Application (Nanotechnology Research, Life Science, Semiconductor & Electronics, and More), End User (Hospitals, Clinics and Diagnostic Labs, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Microscopy Device Market Trends and Insights
Technological Advancements in Super-Resolution Optics & Quantum Sensing
Super-resolution techniques like STED, SIM, and PALM are breaking the diffraction barrier to reveal structures below 50 nanometers, which strengthens single-cell and neurodegeneration research as labs push to quantify protein interactions in living systems. Early adopters are layering quantum sensing based on nitrogen-vacancy centers in diamond to image magnetic fields, detect nanoscale defects in semiconductor wafers, and capture single-molecule events in biophysics. The microscopy device market is benefiting as buyers seek hybrid platforms that switch among widefield, confocal, and super-resolution modes within the same workflow to maximize throughput. Academic consortia and pharmaceutical companies in North America and Europe are leading purchases due to pipeline demands for target validation and high-content screening. Complexity in optical alignment and reliance on specific fluorophores still slow routine clinical use, creating a service and training opportunity for vendors with robust application support.
AI-Driven Automated Digital Pathology Adoption
Pathology networks are moving from manual microscopy to whole-slide imaging combined with convolutional neural networks that classify tissue, quantify biomarkers, and flag anomalies, and several models now show sensitivities exceeding 95% in indications with strong ground truth. In January 2026, the Central Silk Board in India highlighted an AI-enabled microscope initiative that helps farmers detect silkworm disease earlier, underscoring how applied AI microscopy is expanding beyond clinical settings into production environments. Oncology workloads are a catalyst because tumor microenvironment analysis requires quantifying immune infiltrates and vascular structures across gigapixel images at scale. The European Union's In Vitro Diagnostic Regulation mandates CE marking for AI-based diagnostic software, prompting vendors to run prospective clinical validation studies to align model performance with clinical endpoints. Hospitals and diagnostic labs are the fastest-growing end-user segment at a 6.60% CAGR through 2031, driven by pathologist labor constraints and the need to standardize multi-site interpretations to reduce variability in care
High Capital & Operating Costs of Devices
The upfront cost of high-end cryo-EM suites remains in the USD 5 million to USD 7 million range once facilities, shielding, and vibration isolation are included, and this delays access for many centers that depend on pooled grants. Annual operating expenses for aberration-corrected TEMs can reach USD 200,000, including maintenance, cryogens, and cleanroom utilities, which limits broader adoption even when equipment is partially subsidized. Shared-facility and leasing models soften the barrier, but scheduling, maintenance windows, and variable uptime add coordination costs for multi-institution use. For hospitals and diagnostic labs, budget ceilings slow digital pathology deployments even where throughput and standardization gains support a clear business case. The microscopy device market reflects these capital constraints in emerging economies, where currency risk and import duties add further headwinds to large-ticket equipment purchases.
Other drivers and restraints analyzed in the detailed report include:
- Government Nanotech & Life-Science R&D Funding Surge
- Semiconductor Gate-All-Around Node Miniaturization Needs
- Global Shortage of Hybrid Optics-Software Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electron microscopy is forecast to grow at 6.56% annually from 2026 to 2031, outpacing the broader microscopy device market, driven by compact cryo-EM systems. Adoption rises when structure-based drug design workflows require higher throughput and local control over sample preparation and data processing to shorten iteration cycles. In parallel, semiconductor fabs are increasing TEM and SEM tool counts to inspect nanosheet stacks, spacers, and hidden defects that are not visible with optical metrology at 2-nanometer-class nodes. Aberration-corrected optics and advanced detectors remain the differentiators for lattice-strain mapping and atomic-column resolution during logic and memory ramps. These factors are pushing electron platforms into a larger role across both process development and failure analysis as fabs seek greater statistical coverage and reliability in metrology.
Optical microscopy commanded 41.80% of % microscopy device market share in 2025, given its ubiquity in clinical workflows, teaching labs, and quality control environments that value ease of use and lower service overheads.
Complete Report Scope:
- By Microscopy Type
- Electron Microscopy
- Transmission Electron Microscopy (TEM)
- Scanning Electron Microscopy (SEM)
- Cryogenic Electron Microscopy (Cryo-EM)
- Optical Microscopy
- Bright-field & Phase-contrast
- Fluorescence & Confocal
- Super-resolution (STED, SIM, PALM)
- Scanning Probe Microscopy
- Atomic Force Microscopy (AFM)
- Scanning Tunneling Microscopy (STM)
- Other Technologies
- Electron Microscopy
- By Application
- Life Science
- Nanotechnology Research
- Semiconductor & Electronics
- Materials Science & Metallurgy
- Other Applications
- By End User
- Academic & Research Institutes
- Hospitals, Clinics & Diagnostic Labs
- Pharmaceutical & Biotechnology Companies
- Semiconductor & Electronics Manufacturers
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 39.25% of the microscopy device market share in 2025, as pharma R&D, academic research output, and semiconductor investments supported sustained procurement of optical and electron microscopy platforms. The CHIPS and Science Act allocates USD 52.7 billion across manufacturing incentives and research programs, which elevates demand for advanced metrology fleets at Intel and other operators building new lines in Arizona and Ohio. University labs in the United States and Canada continue to purchase cryo-EM and super-resolution systems with support from national programs that expanded in 2025, including Canada's Strategic Innovation Fund, which allocated CAD 450 million (USD 335 million) to research infrastructure. These factors anchor a stable replacement cycle and add new first-time buyers as hospitals scale digital pathology and standardize across networks. The microscopy device market in North America also benefits from a strong service ecosystem and vendor presence, which accelerates training and validation for regulated workflows.
Europe sustains a mature installed base shaped by public funding and harmonized regulations that emphasize clinical validation and sustainability. Horizon Europe committed EUR 95.5 billion (USD 102 billion) through 2027 for research and innovation, and dedicated photonics and nanomedicine streams continue to support procurement of high-end imaging platforms across universities and clinical centers.
Asia-Pacific remains the fastest-growing region, with a projected 6.74% CAGR, and the microscopy device market aligns with government programs that prioritize domestic semiconductor and life sciences capabilities. China's policy support helps local research centers and industrial labs scale adoption of electron platforms for logic, memory, and advanced materials, thereby generating consistent orders for TEM, SEM, and related accessories. Outside these hubs, the Middle East and Africa are scaling research infrastructure as part of diversification strategies. At the same time, Latin America faces budget headwinds that temper near-term growth despite active research communities.
- Ametek (Cameca)
- Andor Technology Ltd.
- Bruker
- Carl Zeiss
- Cytovale Inc.
- Danaher
- Delong Instruments
- Euromex Microscopes
- Hitachi
- JEOL Ltd.
- Keyence Corporation
- Labomed Inc.
- Motic Microscopes
- Nikon
- NTMDT
- Olympus
- Oxford Instruments (Asylum Research)
- Oxford Instruments
- Park Systems Corp.
- Tescan Orsay Holding
- Thermo Fisher Scientific
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Technological Advancements in Super-Resolution Optics & Quantum Sensing
- 4.2.2 AI-Driven Automated Digital Pathology Adoption
- 4.2.3 Government Nanotech & Life-Science R&D Funding Surge
- 4.2.4 Semiconductor Gate-All-Around Node Miniaturization Needs
- 4.2.5 Desktop Cryo-EM Democratizing Structure-Based Drug Design
- 4.2.6 Sustainability Push For Energy-Efficient, Modular Microscopes
- 4.3 Market Restraints
- 4.3.1 High Capital & Operating Costs of Devices
- 4.3.2 Global Shortage of Hybrid Optics-Software Talent
- 4.3.3 Precision-Optic Supply-Chain Bottlenecks (Germanium, Gallium)
- 4.3.4 Escalating IP-Litigation Risks in Cross-Border Tech Transfer
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Microscopy Type
- 5.1.1 Electron Microscopy
- 5.1.1.1 Transmission Electron Microscopy (TEM)
- 5.1.1.2 Scanning Electron Microscopy (SEM)
- 5.1.1.3 Cryogenic Electron Microscopy (Cryo-EM)
- 5.1.2 Optical Microscopy
- 5.1.2.1 Bright-field & Phase-contrast
- 5.1.2.2 Fluorescence & Confocal
- 5.1.2.3 Super-resolution (STED, SIM, PALM)
- 5.1.3 Scanning Probe Microscopy
- 5.1.3.1 Atomic Force Microscopy (AFM)
- 5.1.3.2 Scanning Tunneling Microscopy (STM)
- 5.1.4 Other Technologies
- 5.1.1 Electron Microscopy
- 5.2 By Application
- 5.2.1 Life Science
- 5.2.2 Nanotechnology Research
- 5.2.3 Semiconductor & Electronics
- 5.2.4 Materials Science & Metallurgy
- 5.2.5 Other Applications
- 5.3 By End User
- 5.3.1 Academic & Research Institutes
- 5.3.2 Hospitals, Clinics & Diagnostic Labs
- 5.3.3 Pharmaceutical & Biotechnology Companies
- 5.3.4 Semiconductor & Electronics Manufacturers
- 5.3.5 Others
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Ametek (Cameca)
- 6.3.2 Andor Technology Ltd.
- 6.3.3 Bruker Corporation
- 6.3.4 Carl Zeiss AG
- 6.3.5 Cytovale Inc.
- 6.3.6 Danaher Corporation (Leica Microsystems)
- 6.3.7 Delong Instruments
- 6.3.8 Euromex Microscopes
- 6.3.9 Hitachi High-Tech Corporation
- 6.3.10 JEOL Ltd.
- 6.3.11 Keyence Corporation
- 6.3.12 Labomed Inc.
- 6.3.13 Motic Microscopes
- 6.3.14 Nikon Corporation
- 6.3.15 NTMDT
- 6.3.16 Olympus Corporation
- 6.3.17 Oxford Instruments (Asylum Research)
- 6.3.18 Oxford Instruments PLC
- 6.3.19 Park Systems Corp.
- 6.3.20 Tescan Orsay Holding
- 6.3.21 Thermo Fisher Scientific Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


