|
시장보고서
상품코드
2121857
액체 생검 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Fluid Biopsy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
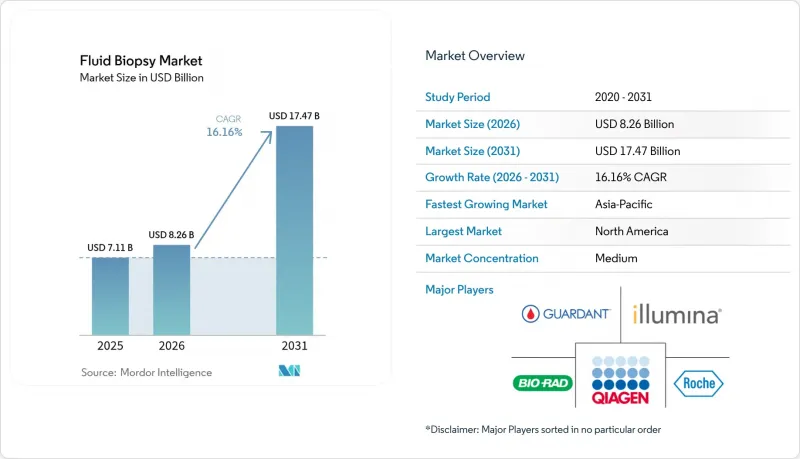
에 의하면, 2026년 체액 생검 시장 규모는 82억 6,000만 달러로 추정되며, 2025년 71억 1,000만 달러에서 2031년에는 174억 7,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 16.16%를 기록할 전망입니다.
본 보고서는 적응증(폐암, 유방암 등), 바이오마커 유형(순환 종양 세포 등), 제품 및 서비스(키트 및 시약 등), 기술(차세대 염기서열 분석(NGS) 등), 최종 사용자(검사 기관 등), 검체 유형(혈액, 소변 등),지역(북미 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 체액 생검 시장 동향 및 인사이트
비침습적 종양 진단법에 대한 선호도 증가
더 안전한 검사법을 원하는 환자들 수요가 암 검사 체계를 일신했습니다. 메디케어가 2025년부터 가디언트 헬스(Guardant Health)사의 ‘쉴드(Shield)’ 분석법을 보험 적용 대상으로 임베디드한 것은 정기 검진에서 체액 생검의 유용성을 입증하는 것이며, 재향군인부 수급자에 대한 접근성도 확대될 것입니다. 기저질환이 있는 경우 조직 생검으로 인한 합병증이 급증하기 때문에 고령 환자층이 가장 큰 혜택을 받게 될 것입니다. 혈액을 이용한 실시간 모니터링을 통해 종양 전문의는 영상 진단에 기반한 일정보다 더 빨리 치료법을 조정할 수 있게 되었으며, 체액 생검 시장의 솔루션은 기존 검사를 대체하는 것이 아니라 이를 보완하는 역할을 하고 있습니다. 검체 채취에는 채혈 기술만 필요하기 때문에 외래 진료소에서 이 검사가 빠르게 도입되고 있습니다. 이러한 추세는 분산형 검사에 대한 수요를 촉진하며, 시약을 통한 지속적인 수익의 기반이 되고 있습니다.
AI를 활용한 프래그먼트 오믹스가 조기 발견 정확도를 향상
현재 머신러닝 모델은 세포 유래 DNA에서 단편의 길이, 말단 모티프, 메틸화 패턴을 분석하여 비소세포폐암 임상시험에서 92%의 민감도와 90%의 특이도로 초기 종양을 식별하고 있습니다. 웨일 코넬 메디슨의 MRD-EDGE 프로토콜은 영상 진단상 재발이 나타나기 몇 달 전에 잔류 병변을 감지함으로써 선제적인 치료법 전환을 가능하게 합니다. 존스 홉킨스 대학의 ARTEMIS-DELFI 플랫폼은 췌장암의 치료 반응 지표를 실시간으로 제공하여, 기존에는 모니터링에서 누락되곤 했던 이 악성 종양에 대한 대응을 실현하고 있습니다. 이러한 진전을 통해 AI는 미래 체액 생검 시장 플랫폼의 핵심 인프라가 되고 있습니다. 전 세계 데이터 세트를 활용한 알고리즘의 지속적인 훈련을 통해, AI 네이티브 분석법과 기존 분석법 간의 성능 격차는 더욱 확대될 전망입니다.
높은 검사 비용과 보험 급여의 장벽
종합적인 체액 생검 패널의 비용은 1회당 평균 2,800달러로 여전히 고가이며, 이는 암 치료 예산이 제한된 의료 기관에서의 도입을 저해하고 있습니다. 의료 경제 모델에 따르면, 대장암 2차 선별 검사가 비용 대비 효과의 기준치에 도달하기 위해서는 가격이 3분의 2 수준으로 낮아져야 합니다. 보험사의 심사 주기는 여전히 길며, 분석적 타당성 데이터보다는 확고한 임상적 유용성에 대한 증거가 요구되고 있습니다. 신흥 시장에서는 수입 시약에 대한 예산 편성을 복잡하게 만드는 환율 변동 위험이 추가로 존재합니다. 확장 가능한 생산을 통해 두 자릿수 비용 절감이 실현되기 전까지는 일류 3차 의료기관 이외의 곳에서는 보급이 제한적일 가능성이 있습니다.
부문 분석
2025년에는 폐암 분야의 용도가 총 매출의 33.12%를 차지하며, EGFR, ALK 및 MET 억제제를 통한 치료 선택을 이끄는 여러 FDA 승인 동반 진단제를 통해 그 주도적 위치를 공고히 했습니다. 체액 생검 시장은 상세하게 매핑된 돌연변이 프로파일과 질병 진행 시 재검사의 임상적 필요성으로부터 혜택을 받고 있으며, 이는 시약 수요를 뒷받침하고 있습니다. 췌장암 프로그램은 초기 규모는 작지만, 며칠 이내에 실행 가능한 인사이트력을 제공하는 AI 기반 치료 반응 모니터링 플랫폼의 강점을 바탕으로 17.98%라는 놀라운 예측 연평균 성장률(CAGR)을 보이고 있습니다. 치료 선택 패널에 대한 보험사의 폭넓은 지원으로 인해, 병원들은 기준선 병기 분류 프로토콜에 체액 생검을 통합하도록 장려받고 있습니다.
실세계 데이터에 따르면, 유방암 및 대장암 의료진은 현재 영상 진단 주기 사이에 혈액 기반 모니터링을 추가하고 있으며, 이로 인해 평균 방사선 검사 이용률이 15% 감소했습니다. 전립선암 적응증 분야는 BRCA 양성 전이성 거세 저항성 전립선암에 대한 승인으로 검사 범위가 유전체 검사 실험실에서 비뇨기과 클리닉으로 확대됨에 따라 탄력을 받고 있습니다. 난소암 및 위암에 대한 임상시험은 멀티오믹스 검사를 통해 돌연변이 중심 패널에서는 발견되지 않는 후성유전학적 특징이 밝혀짐에 따라 꾸준히 진전되고 있습니다. 종양의 유형에 관계없이 도입이 진행되고 있는 것은 단일 적응증에 대한 보험 급여의 역풍으로부터 수익 주기를 완화시켜, 액체 생검 시장을 안정적인 성장 궤도에 계속 올려놓고 있습니다.
2025년 바이오마커 매출 중 ctDNA가 45.10%를 차지할 것으로 예상되며, 이는 지난 10년에 걸친 임상 검증과 규제 당국의 승인이 누적된 결과입니다. 그러나 지질막이 분석 대상 물질을 분해로부터 보호하고, 1기 진단에서 더 높은 분석 감도를 제공하기 때문에 소포 기반 검사는 연평균 성장률(CAGR) 18.82%로 확대되고 있습니다. 엑소좀 내의 단백질과 RNA 함유물을 조합하여 분석함으로써, 위양성 판별 정확도를 향상시키는 상호 보완적인 데이터를 얻을 수 있습니다. ctDNA와 소포 지표를 결합한 다항목 검사는 시술상의 위험을 수반하지 않으면서 양성 예측치를 영상 진단과 동등한 수준으로 끌어올리고 있습니다.
순환 종양 세포는 전이 진행을 페노타이핑하는 데 있어 틈새적인 중요성을 지니는 반면, 마이크로RNA 시그니처는 조직형에 의존하지 않는 프로그램을 보완합니다. 통합형 AI 파이프라인은 현재 프래그먼트 오믹스,메틸화, 그리고 소포 내용물 데이터를 융합하여 10mm 미만의 종양 부하에서도 원발 조직을 예측할 수 있게 하고 있습니다. 조기 발견을 중시하는 투자자들은 민감도에 대한 장벽이 해소되는 대로 스크리닝 코드셋에 대한 고액의 보험 급여가 예상된다는 점을 내다보고, 소포 관련 스타트업 기업에 자본을 투입하고 있습니다. 바이오마커 개발 경쟁은 수익원을 다각화하고 단일 분석 항목에 대한 의존도를 낮추는 동시에, 체액 생검 업계 전반의 혁신을 촉진하고 있습니다.
지역별 분석
북미는 2025년, FDA의 브레이크스루 패스웨이(Breakthrough Pathway), 관대한 메디케어 급여 범위, 그리고 학계와 산업계의 협력을 통한 긴밀한 생태계의 지원에 힘입어 전 세계 체액 생검 시장 매출의 38.20%를 차지했습니다. 미국의 종양학 네트워크가 검사 건수의 대부분을 차지하는 한편, 캐나다와 멕시코로 넘어가는 국경 간 환자들이 지역 수요를 끌어올리고 있습니다. 검체 취급 기준의 조화를 위한 지속적인 정책 노력은 검사실 간의 편차를 줄이고, 품질 지표와 연계된 보상 수준을 보호하는 것을 목적으로 하고 있습니다.
아시아태평양은 중국, 일본, 인도가 분자 종양학 예산을 확대함에 따라 2031년까지 19.05%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 중국이 2024년에 메틸화 기반 간암 검사법을 승인한 것은 국내 혁신을 촉진하려는 규제 당국의 의지를 뒷받침합니다. 일본에서 표적 치료용 동반 진단제의 최근 승인은 제품 주기를 가속화하는 규제 당국과 산업계 간의 긴밀한 협력을 반영하고 있습니다. 정부 주도의 제조 인센티브로 인해 현지 시약 비용이 절감되어 도입이 더욱 촉진되고 있습니다.
유럽은 성숙한 시장임에도 불구하고 여전히 성장을 지속하고 있습니다. 조화로운 체외진단약 규제와 지속적으로 축적되는 근거를 바탕으로, 각국의 보험사들은 시범 프로그램의 범위를 넘어 MRD 모니터링에 대한 보험 적용을 추진하고 있습니다. 독일, 프랑스, 영국에서는 통합적인 유전체 보고서를 중시하는 종합적인 암 센터가 시장 수요를 뒷받침하고 있습니다. 남유럽 및 스칸디나비아 국가들은 조달 비용을 절감하는 범유럽적 조달 체계를 통해 이에 뒤를 잇고 있습니다. 중동 및 아프리카, 남미는 여전히 초기 단계이지만, 임상시험 참여가 증가하고 있으며, 보험 환급 체계가 공식적으로 확립되면 장기적인 상업적 기회가 기대됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the fluid biopsy market size in 2026 is estimated at USD 8.26 billion, growing from 2025 value of USD 7.11 billion with 2031 projections showing USD 17.47 billion, growing at 16.16% CAGR over 2026-2031.
This report is Segmented by Indication (Lung Cancer, Breast Cancer, and More), Biomarker Type (Circulating Tumor Cells, and More), Product & Service (Kits & Reagents, and More), Technology (Next-Generation Sequencing (NGS), and More), End User (Reference Laboratories and More), Sample Type (Blood, Urine, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Fluid Biopsy Market Trends and Insights
Rising Preference for Non-Invasive Oncology Diagnostics
Patient demand for safer procedures has re-shaped cancer work-ups. Medicare's 2025 coverage of Guardant Health's Shield assay validates liquid biopsy utility for routine screening and extends access to Veterans Affairs beneficiaries. Elderly cohorts gain most because tissue biopsy complications rise sharply with comorbidities. Real-time blood-based monitoring allows oncologists to modify therapy sooner than imaging-based schedules, giving fluid biopsy market solutions a complementary role rather than a replacement one. Outpatient clinics adopt the tests quickly because sample collection requires only phlebotomy skills. The trend reinforces decentralized testing demand and underpins recurring reagent revenue.
AI-Driven Fragmentomics Boosting Early-Stage Detection Accuracy
Machine-learning models now interpret fragment length, end motif, and methylation patterns from cell-free DNA to identify early tumors with 92% sensitivity at 90% specificity in non-small cell lung cancer trials. Weill Cornell Medicine's MRD-EDGE protocol detects residual disease months before radiographic relapse, facilitating pre-emptive therapy switches. Johns Hopkins' ARTEMIS-DELFI platform provides real-time pancreatic cancer response metrics, addressing a malignancy that historically evaded surveillance. These advances make AI the core infrastructure for future fluid biopsy market platforms. Continuous algorithm training with global data sets will likely widen performance gaps between AI-native and conventional assays.
High Test Cost & Reimbursement Hurdles
Comprehensive liquid biopsy panels still average USD 2,800 per use, challenging adoption in systems with constrained oncology budgets. Health-economic models indicate prices must drop by two-thirds for second-line colorectal screening to reach cost-effectiveness thresholds. Payer review cycles remain lengthy, demanding robust clinical-utility evidence rather than analytical-validity data. Emerging markets face additional currency fluctuation risks that complicate budgeting for imported reagents. Until scalable manufacturing achieves double-digit cost reductions, uptake outside premium tertiary centers may remain modest.
Other drivers and restraints analyzed in the detailed report include:
- Sequencing-Cost Decline & NGS Workflow Automation
- Reimbursement Expansion for Minimal Residual-Disease Blood Tests
- Low ctDNA Yield in Early-Stage Tumors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, lung applications generated 33.12% of overall revenues, consolidating leadership through multiple FDA-cleared companion diagnostics that guide EGFR, ALK, and MET inhibitor therapy selections. The fluid biopsy market benefits from well-mapped mutation profiles and the clinical necessity of repeat testing at progression, which boosts reagent pull-through. Pancreatic programs, although starting smaller, post an impressive 17.98% forecast CAGR on the strength of AI-enabled response monitoring platforms that deliver actionable insight within days. Broad payer support for therapy-selection panels encourages hospitals to integrate liquid biopsy into baseline staging protocols.
Real-world data show breast and colorectal oncology teams now add blood-based surveillance between imaging cycles, cutting average radiology utilization by 15%. Prostate cancer indications gain traction after BRCA-positive metastatic castration-resistant approvals expanded testing beyond genomic labs to urology clinics. Ovarian and gastric trials progress steadily as multi-omics assays uncover epigenetic signatures absent in mutation-centric panels. Adoption diversity across tumor types helps cushion revenue cycles against single-indication reimbursement headwinds and keeps the fluid biopsy market on a stable expansion path.
ctDNA supplied 45.10% of the 2025 biomarker revenue, reflecting a decade of cumulative clinical validation and regulatory clearance. However, vesicle-based assays are scaling at a 18.82% CAGR because lipid membranes protect analytes from degradation, yielding higher analytical sensitivity in Stage I diagnoses. Combined protein and RNA cargo analysis inside exosomes supplies orthogonal data that improve false-positive discrimination. Multi-analyte tests pairing ctDNA with vesicle metrics push positive predictive values into imaging-equivalent ranges without procedural risks.
Circulating tumor cells hold niche relevance for phenotyping metastatic progression, while microRNA signatures supplement histology-agnostic programs. Integrative AI pipelines now fuse fragmentomics, methylation, and vesicle-cargo data, enabling tissue-of-origin predictions with sub-10-millimeter tumor burden. Investors prioritizing early-detection claims channel capital into vesicle startups, anticipating premium reimbursement for screening code sets once sensitivity hurdles are cleared. The biomarker race diversifies revenue streams, reducing single-analyte dependence and fostering innovation across the fluid biopsy industry.
Complete Report Scope:
- By Indication
- Lung Cancer
- Breast Cancer
- Colorectal Cancer
- Prostate Cancer
- Pancreatic Cancer
- Other Indications
- By Biomarker Type
- Circulating Tumour Cells (CTCs)
- Circulating Tumour DNA (ctDNA)
- Cell-free DNA (cfDNA)
- Extracellular Vesicles / Exosomes
- Other Biomarkers (miRNA, TEPs, proteins)
- By Product & Service
- Kits & Reagents
- Instruments & Platforms
- Software & Bioinformatics
- Testing Services
- By Technology
- Next-Generation Sequencing (NGS)
- Digital PCR / ddPCR
- Real-Time PCR
- Microarray & qPCR
- Other (Nanopore, Lab-on-Chip, etc.)
- By End User
- Reference Laboratories
- Hospital & Physician Labs
- Academic & Research Centers
- CROs & Biopharma
- By Sample Type
- Blood (Plasma/Serum)
- Urine
- Saliva / Sputum
- Cerebrospinal Fluid
- Other Body Fluids
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America controlled 38.20% of global fluid biopsy market revenue in 2025, supported by FDA breakthrough pathways, generous Medicare coverage, and a dense ecosystem of academic-industry collaborations. United States oncology networks absorb the majority of test volumes, while cross-border patients to Canada and Mexico augment regional demand. Ongoing policy efforts to harmonize sample-handling standards aim to reduce inter-lab variability and protect reimbursement levels tied to quality measures.
Asia-Pacific records the fastest 19.05% CAGR through 2031 as China, Japan, and India expand molecular oncology budgets. China's 2024 approval of a methylation-based liver cancer assay underscores regulatory willingness to catalyze domestic innovation. Japan's recent companion diagnostic endorsements for targeted therapies reflect sophisticated regulator-industry dialogue that accelerates product cycles. Government-linked manufacturing incentives lower localized reagent costs, further stimulating uptake.
Europe occupies a mature but still expanding position. Harmonized in-vitro diagnostic regulation, coupled with growing evidence packages, prompts national payers to reimburse MRD monitoring beyond pilot programs. Germany, France, and the United Kingdom anchor market demand through comprehensive cancer centers that value integrated genomic reports. Southern Europe and Scandinavia follow via pan-European procurement schemes that cut acquisition costs. Middle East, Africa, and South America remain nascent but demonstrate increasing trial participation, foreshadowing longer-term commercial opportunities once reimbursement pathways formalize.
- Guardant Health
- Roche
- Illumina
- Grail
- Bio-Rad Laboratories
- Qiagen N V
- Foundation Medicine
- Natera
- Thermo Fisher Scientific
- Exact Sciences
- NeoGenomics Laboratories
- Inivata
- Lucence Diagnostics
- Predicine Inc.
- LungLife AI
- Exosome Diagnostics
- Biocept
- Angle plc
- Adaptive Biotechnologies
- Singlera Genomics
- Oncocyte Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Preference For Non-Invasive Oncology Diagnostics
- 4.2.2 Rapid Increase In Global Cancer Incidence
- 4.2.3 Sequencing-Cost Decline & NGS Workflow Automation
- 4.2.4 Reimbursement Expansion For Minimal Residual-Disease (MRD) Blood Tests
- 4.2.5 AI-Driven Fragmentomics Boosting Early-Stage Detection Accuracy
- 4.2.6 Venture Capital Inflow To Decentralized Fluid-Biopsy Platforms
- 4.3 Market Restraints
- 4.3.1 High Test Cost & Reimbursement Hurdles
- 4.3.2 Emerging Optical-Biopsy & Imaging Substitutes
- 4.3.3 Pre-Analytical Sample-Handling Variability
- 4.3.4 Low ctDNA Yield In Early-Stage Tumors
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Indication
- 5.1.1 Lung Cancer
- 5.1.2 Breast Cancer
- 5.1.3 Colorectal Cancer
- 5.1.4 Prostate Cancer
- 5.1.5 Pancreatic Cancer
- 5.1.6 Other Indications
- 5.2 By Biomarker Type
- 5.2.1 Circulating Tumour Cells (CTCs)
- 5.2.2 Circulating Tumour DNA (ctDNA)
- 5.2.3 Cell-free DNA (cfDNA)
- 5.2.4 Extracellular Vesicles / Exosomes
- 5.2.5 Other Biomarkers (miRNA, TEPs, proteins)
- 5.3 By Product & Service
- 5.3.1 Kits & Reagents
- 5.3.2 Instruments & Platforms
- 5.3.3 Software & Bioinformatics
- 5.3.4 Testing Services
- 5.4 By Technology
- 5.4.1 Next-Generation Sequencing (NGS)
- 5.4.2 Digital PCR / ddPCR
- 5.4.3 Real-Time PCR
- 5.4.4 Microarray & qPCR
- 5.4.5 Other (Nanopore, Lab-on-Chip, etc.)
- 5.5 By End User
- 5.5.1 Reference Laboratories
- 5.5.2 Hospital & Physician Labs
- 5.5.3 Academic & Research Centers
- 5.5.4 CROs & Biopharma
- 5.6 By Sample Type
- 5.6.1 Blood (Plasma/Serum)
- 5.6.2 Urine
- 5.6.3 Saliva / Sputum
- 5.6.4 Cerebrospinal Fluid
- 5.6.5 Other Body Fluids
- 5.7 Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Australia
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Guardant Health
- 6.3.2 Roche Diagnostics
- 6.3.3 Illumina Inc.
- 6.3.4 Grail Inc.
- 6.3.5 Bio-Rad Laboratories
- 6.3.6 Qiagen N V
- 6.3.7 Foundation Medicine
- 6.3.8 Natera Inc.
- 6.3.9 Thermo Fisher Scientific
- 6.3.10 Exact Sciences
- 6.3.11 NeoGenomics Laboratories
- 6.3.12 Inivata Ltd
- 6.3.13 Lucence Diagnostics
- 6.3.14 Predicine Inc.
- 6.3.15 LungLife AI Inc.
- 6.3.16 Exosome Diagnostics
- 6.3.17 Biocept Inc.
- 6.3.18 Angle plc
- 6.3.19 Adaptive Biotechnologies
- 6.3.20 Singlera Genomics
- 6.3.21 Oncocyte Corporation
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment