|
시장보고서
상품코드
2121950
소규모 LNG : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Small-scale LNG - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
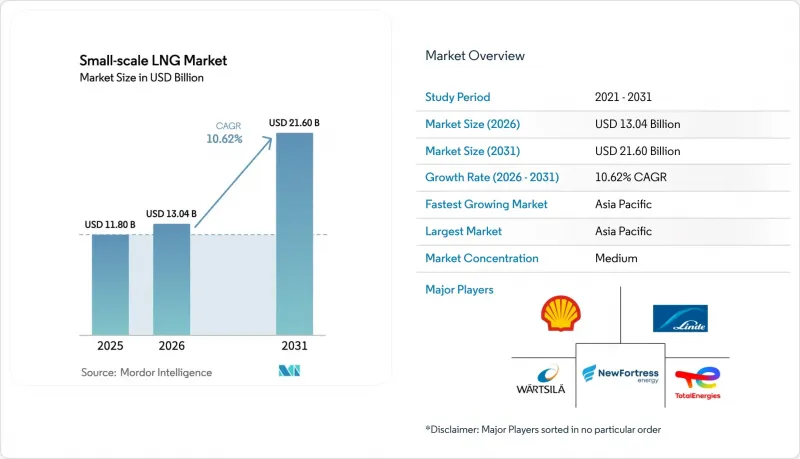
에 따르면 소규모 LNG 시장 규모는 2025년 118억 달러에서 2026년에는 130억 4,000만 달러로 확대하며, 2031년까지 216억 달러에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 10.62%로 성장할 것으로 전망되고 있습니다.
이 보고서는 유형(액화 터미널, 재기화 터미널), 공급 형태(트럭, 파이프라인 및 철도, 환적 및 벙커링, ISO 컨테이너),용도(수송, 발전 등), 최종사용자(유틸리티·독립발전사업자(IPP), 석유 및 가스 상류 사업자 등), 지역(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)별로 분류되어 있습니다.
전 세계 소규모 LNG 시장의 동향 및 인사이트
IMO 및 FuelEU Maritime에 의한 황 함량 상한선 강화가 선박용 LNG 벙커링 도입을 가속화하고 있습니다.
IMO의 0.50%라는 전 세계 황 함량 상한선 규제 및 유럽연합(EU)의 FuelEU Maritime 온실가스 규제로 인해 선박 연료의 경제성은 LNG 쪽으로 기울고 있습니다. 선주들은 LNG 추진으로의 전환을 통해 수백만 달러에 달하는 스크러버 개조 비용을 피하는 동시에 CO₂, SOx 및 미세먼지 배출을 줄일 수 있습니다. 2024년 말 기준, 전 세계 LNG 벙커링 선단은 61척에 달하며, 북서유럽, 지중해,아시아에 가장 큰 집적지가 있습니다. TotalEnergies는 2024년, 아라비아해를 항해하는 선박에 서비스를 제공하기 위해 오만의 두쿰 항에 전용 벙커 터미널을 개설했습니다. FuelEU Maritime가 메탄 슬립 산정을 의무화하고 있는 만큼, 각 엔진 제조사들은 미연소 메탄을 1% 미만으로 줄이는 고압 분사 시스템의 도입을 가속화하고 있습니다. 이러한 일련의 노력으로 소규모 LNG 시장에서 신뢰성 높은 인프라와 규제 안정성이 촉진되고 있습니다.
외딴 지역의 광산 및 오프그리드 전력용 모듈식 액화 플랜트의 급속한 확산
표준화된 마이크로 및 미니 액화 플랜트를 통해 파이프라인 연결 없이도 하루 10,000갤런에 불과한 소규모 처리 능력으로 스트랜드드 가스나 수반 가스를 수익화할 수 있게 됩니다. Chart Industries의 IPSMR(R) 공정은 LNG 1kg당 0.35kWh 미만의 전력을 소비하므로, 현장의 재생 가능 에너지나 발전기를 통한 전력 공급만으로도 오프그리드 사이트 운영이 가능합니다. 호주의 한 광산에서는 컨테이너형 LNG를 활용하여 1,000km 이상을 트럭으로 운송되던 디젤 연료를 대체함으로써, 연료 물류 비용을 40% 절감하고 있습니다. 인도네시아와 같은 도서 지역에서는 가스 자원이 풍부한 섬에서 인구 밀집 지역으로 ISO 탱크를 운송하는 가상 파이프라인에 의존하고 있으며, 수십억 달러 규모의 해저 파이프라인 건설을 피하고 있습니다. 연간 생산량(MTPA)이 0.05 미만인 플랜트에서는 보일오프가 여전히 과제로 남아 있지만, 증기를 부지내 발전기에 공급하는 하이브리드 솔루션을 통해 가스 가치의 최대 80%를 회수할 수 있습니다. 자본 비용이 낮아지고 오프그리드 수요가 증가함에 따라 모듈식 액화 기술은 소규모 LNG 시장의 장기적인 성장을 지원하고 있습니다.
러시아-우크라이나 분쟁으로 인해 현물 LNG의 지정학적 리스크 프리미엄이 상승
2022년 분쟁이 격화되면서 유럽으로 향하는 러시아산 파이프라인 가스 공급이 1550억 m³ 감소했고, LNG 현물 가격은 1MMBtu당 25달러까지 치솟았으나, 2024년 말까지 10-14달러 수준으로 안정되었습니다. 벙커링 및 지자체 부문의 소규모 구매자들은 공급업체들이 현물 가격 연동형 계약 조건을 밀어붙이는 가운데, 장기 고정 가격 계약을 확보하는 데 어려움을 겪고 있습니다. 아시아의 수입업자들은 유럽과 화물 확보를 놓고 치열한 경쟁을 벌이고 있으며, 그 결과 동남아시아 및 카리브해 지역에서의 공급이 재편되고 있습니다. Arctic LNG 2에 대한 제재로 인해 예상 생산량 19.8 MTPA가 상실됨에 따라 다른 생산자들은 가격 규율을 유지하려는 태도를 강화하고 있습니다. 구매자들은 가격 변동에 대비해 저장 능력을 강화하고 있지만, 저장 탱크 및 소형 FSRU 도입으로 인해 5,000만-1억 달러의 추가 자본이 필요하게 되어, 디젤 연료에 대한 LNG의 비용 우위가 훼손되고 있습니다. 이러한 불확실성으로 인해 소규모 LNG 시장의 단기적인 성장은 둔화되고 있습니다.
부문 분석
2025년, 액화 터미널은 소규모 LNG 시장의 62.3%를 차지하며, 이는 활용되지 않고 방치되어 있던 가스 자산을 경제적으로 수익화해야 할 필요성을 반영합니다. 많은 마이크로 플랜트는 연간 0.1 MTPA 미만으로 가동되고 있으며, 고효율 IPSMR® 기술을 채택하여 90% 이상의 액화 수율을 달성하고 있습니다. 소규모 플랜트는 바이오가스 정제, 플레어 가스 회수, 외딴 지역 전력 공급에 활용되는 반면, 미니 플랜트와 소규모 플랜트는 수출용 및 지역 허브로의 공급을 담당하고 있습니다. ISO 14001 준수는 환경적 감독을 강화하는 한편, 그린 파이낸스 활용을 가능하게 합니다. 자본 집약도는 연간 생산 능력 1톤당 400-800달러 범위이며, 이는 현재 프론티어 시장에서도 달성 가능한 수준입니다.
재기화 시장은 2031년까지 연평균 성장률(CAGR) 14.4%로 확대되고 있습니다. Hoegh Esperanza나 Hoegh Gannet과 같은 FSRU는 18개월 이내에 독일 가스망에 연간 100억 m³를 공급함으로써, 육상 시설의 5년에 달하는 건설 기간을 단축했습니다. 필리핀의 BW Mindanao FSRU는 루손 섬에 연간 5 MTPA를 공급하고 있으며, 이를 통해 2,400MW 규모의 석탄 화력 발전소를 폐쇄할 수 있게 되었습니다. 배출 규제 지역에서 의무화되어 있는 증기 회수 시스템은 300만-500만 달러의 추가 비용이 들지만, FuelEU 메탄 규정을 준수합니다. 일일 임대료가 8만-15만 달러인 임대형 FSRU는 고정식 터미널에는 없는 유연성을 구매자에게 제공하여 소규모 LNG 시장의 매력을 높이고 있습니다.
2025년에는 중국의 대형 LNG 차량을 주축으로 트럭을 통한 배송이 52.6%의 점유율을 차지했습니다. 표준 트레일러의 적재량은 20-25톤으로, 5MW 보일러를 2일간 가동하기에 충분한 양이며, 이를 통해 구매자는 파이프라인 용량 요금을 피할 수 있습니다. 2024년에 도입된 Hexagon Purus사의 복합재 실린더는 트레일러의 중량을 40% 줄여, 중량 제한이 있는 유럽 노선에서도 28톤을 적재할 수 있게 했습니다. ISO 컨테이너는 복합 운송을 지원하며, 하역 비용을 최대 30% 절감합니다.
2027년까지 18척의 새로운 벙커링 선박이 전 세계 선단에 합류함에 따라 환적 및 벙커링 시장은 연평균 성장률(CAGR) 14.7%로 확대되고 있습니다. 싱가포르는 2024년에 12개 벙커링 사업자에게 면허를 부여하여 처리량을 45만 톤으로 끌어올렸습니다. 북서유럽에는 29척의 벙커링 선박이 운항 중이며, 2024년에는 1,200회의 기항을 기록했습니다. 황 및 CO₂ 규제가 강화됨에 따라 선박 간 및 육상에서 선박으로의 연료 공급은 소규모 LNG 시장에서 급성장하는 거점으로 자리매김하고 있습니다.
지역별 분석
아시아태평양은 2025년에 소규모 LNG 시장의 47.9%를 차지하며, 2031년까지 연평균 성장률(CAGR) 15.9%로 성장하고 있습니다. 중국의 120만 대 LNG 트럭, 12개 신규 도시 가스 공급 지자체에 공급하는 인도네시아의 가상 파이프라인, 그리고 호주 외딴 지역 광산에서의 수요가 이 지역의 성장을 지원하고 있습니다. 일본의 소데가우라는 2024년에 트럭 적재 설비를 추가하고, 지바현의 공장에 대한 공급을 시작했습니다. 한편, 인도는 파이프라인망이 미치지 않는 주로 공급하기 위해 ISO 탱크를 통해 8만 톤을 수입했습니다. 유럽에서는 파이프라인 포화 상태가 액화 투자에 제동을 걸고 있지만, 이 지역은 벙커링 및 FSRU 분야에서 선도적인 입지를 차지하고 있습니다. 2025년부터 적용되는 FuelEU Maritime의 제재 조치로 인해 선주들은 LNG로의 전환을 강요받고 있으며, 2024년에는 29척의 벙커링 선박이 1,200회의 기항을 처리했습니다. 독일의 4기 FSRU가 러시아산 가스 공급량을 보충하여 현물 가격을 1MWh당 40유로 미만으로 억제하고 있습니다. 북유럽 국가들은 2024년에 바이오 LNG 점유율을 22%로 끌어올려, 탄소 음성 선박 연료로의 길을 제시했습니다.
북미에서는 풍부한 셰일가스 자원과 인플레이션 감축법(Inflation Reduction Act)에 따른 세액 공제를 활용하고 있습니다. Chart Industries가 양조장 및 에탄올 공장에 설치한 마이크로 액화 설비는 1갤런당 1.75달러의 인센티브 대상이며, 한편 캐나다에서는 철도를 통해 외딴 지역으로 LNG를 수송하고 있습니다. 멕시코에서는 2024년 개혁을 통해 수입 터미널이 제3자에게도 개방되어 향후 성장을 위한 기반이 마련되었습니다. 남미는 아직 발전 단계에 있지만 활발한 움직임이 보입니다. New Fortress Energy의 부유식 액화 플랜트는 브라질의 프레솔트층 가스를 대상으로 하며, 아르헨티나의 연간 0.5 MTPA 규모의 플랜트는 국내 및 칠레 시장에 공급됩니다. 칠레는 아타카마 광산에 LNG를 공급하고 있으며, 이를 통해 Codelco는 연간 1,800만 달러의 비용 절감을 실현하고 있습니다. 콜롬비아는 부에나벤투라 및 투마코로의 공급을 목적으로 태평양 연안 터미널 운영권을 부여했습니다.
중동 및 아프리카에서는 UAE와 카타르가 국내 벙커링 네트워크를 구축하고 있는 반면, 남아프리카공화국의 Coega FSRU는 연안 산업에 서비스를 제공하고 있습니다. 모잠비크의 Coral Sul은 LNG를 수출하고 있지만, 2026년부터는 연간 10만 톤의 LNG를 ISO 탱크를 통해 지역에 공급할 계획입니다. 나이지리아의 가상 파이프라인 구상은 ISO 탱크에 관한 표준화된 규정 제정을 기다리고 있습니다. 케냐와 탄자니아는 수입 터미널 자금 조달을 모색하고 있으나, 대출 측면에서 난관에 직면해 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the small-scale LNG market size is expected to increase from USD 11.80 billion in 2025 to USD 13.04 billion in 2026 and reach USD 21.60 billion by 2031, growing at a CAGR of 10.62% over 2026-2031.
This report is Segmented by Type (Liquefaction Terminal and Regasification Terminal), Mode of Supply (Truck, Pipeline and Rail, Transshipment and Bunkering, and ISO Container), Application (Transportation, Power Generation, and More), End-User (Utilities and IPPs, Oil and Gas Upstream Operators, and More), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Small-scale LNG Market Trends and Insights
Tightening IMO And FuelEU Maritime Sulphur Caps Accelerating Marine LNG Bunkering Adoption
The IMO's 0.50% global sulphur limit and the European Union's FuelEU Maritime greenhouse-gas rules are tilting bunker-fuel economics toward LNG. Shipowners can avoid multi-million-dollar scrubber retrofits and simultaneously reduce CO2, SOx, and particulate emissions by shifting to LNG propulsion. The global LNG bunker fleet reached 61 vessels by late 2024, with Northwest Europe, the Mediterranean, and Asia hosting the largest clusters. TotalEnergies opened a dedicated bunkering terminal at Oman's Port of Duqm in 2024 to serve ships transiting the Arabian Sea. FuelEU Maritime's requirement to account for methane slip is spurring engine makers to adopt high-pressure injection systems that cut unburned methane below 1%. These combined measures foster reliable infrastructure and regulatory certainty for the small-scale LNG market.
Rapid Build-out Of Modular Liquefaction Plants For Remote Mining And Off-Grid Power
Standardized micro and mini liquefiers allow stranded or associated gas to be monetized at capacities as low as 10,000 gallons per day without pipeline connections. Chart Industries' IPSMR(R) process consumes under 0.35 kWh per kilogram of LNG, making off-grid sites viable even when power is supplied by on-site renewables or gensets. Australian mines use containerized LNG to displace diesel trucked over 1,000 km, cutting fuel logistics costs by 40%. Indonesia's island geography relies on virtual pipelines that move ISO tanks from gas-rich islands to population centers, sidestepping multi-billion-dollar subsea lines. Boil-off remains a challenge for plants below 0.05 MTPA, but hybrid solutions, venting vapor to on-site generators, recover up to 80% of the gas's value. As capital costs fall and off-grid demand rises, modular liquefaction underpins long-term growth in the small-scale LNG market.
Russia-Ukraine Conflict Raising Geopolitical Risk Premium On Spot LNG
The 2022 escalation cut 155 billion m3 of Russian pipeline gas to Europe, elevating LNG spot prices to USD 25 per MMBtu before moderating to USD 10-14 by late 2024. Small buyers in bunkering and municipal sectors struggle to secure long-term fixed-price contracts as suppliers push for spot-linked terms. Asian importers compete with Europe for cargoes, diverting supply from Southeast Asia and the Caribbean. Sanctions on Arctic LNG 2 removed 19.8 MTPA of expected output, emboldening other producers to maintain pricing discipline. Buyers are adding storage to buffer volatility, but tanks or small FSRUs raise capital needs by USD 50-100 million, eroding LNG's cost edge over diesel. The resulting uncertainty tempers near-term growth in the small-scale LNG market.
Other drivers and restraints analyzed in the detailed report include:
- Heavy-Duty Truck Fleet Shift To LNG In China's "Blue Corridor" Program
- Tax Incentives For Small-Scale LNG Equipment Under The U.S. Inflation Reduction Act
- High Boil-Off And Re-Liquefaction Costs Below 0.05 MTPA Plants
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Liquefaction terminals captured 62.3% of the small-scale LNG market in 2025, reflecting the need to monetize stranded gas assets economically. Many micro-plants operate below 0.1 MTPA and use high-efficiency IPSMR(R) technology to reach 90-plus% liquefaction yield. Small units serve biogas upgrading, flare-gas capture, and remote power, while mini and small plants feed export or regional hubs. Compliance with ISO 14001 adds environmental oversight but unlocks green financing. Capital intensity ranges between USD 400 and USD 800 per tonne of annual capacity, a threshold now attainable for frontier markets.
Regasification capacity is accelerating at a 14.4% CAGR to 2031. FSRUs like Hoegh Esperanza and Hoegh Gannet added 10 billion m3 per year to Germany's grid within 18 months, bypassing five-year onshore timelines. The Philippines' BW Mindanao FSRU feeds 5 MTPA into Luzon, enabling the retirement of 2,400 MW of coal. Vapor-recovery systems, required in emission-control areas, add USD 3-5 million but align with FuelEU methane rules. With day-rates between USD 80,000 and USD 150,000, leased FSRUs give buyers flexibility unmatched by fixed terminals, broadening the appeal of the small-scale LNG market.
Truck delivery held a 52.6% share in 2025, anchored by China's heavy-duty LNG fleet. A standard trailer hauls 20-25 tonnes, sufficient for a 5 MW boiler for two days, letting buyers dodge pipeline capacity charges. Hexagon Purus's composite cylinders, introduced in 2024, cut trailer weight by 40%, enabling 28-tonne payloads on weight-restricted European routes. ISO containers support intermodal movements and cut handling costs by up to 30%.
Transshipment and bunkering are growing at a 14.7% CAGR as 18 new bunker vessels join the global fleet by 2027. Singapore licensed 12 bunkering operators in 2024, boosting volumes to 450,000 tonnes. Northwest Europe fields 29 bunker vessels that performed 1,200 ship calls in 2024. As sulfur and CO2 limits tighten, ship-to-ship and shore-to-ship fueling solidify as fast-growing nodes in the small-scale LNG market.
Complete Report Scope:
- By Type
- Liquefaction Terminal (Micro, Mini, and Small)
- Regasification Terminal (Onshore and Offshore FSRU)
- By Mode of Supply
- Truck
- Pipeline and Rail
- Transshipment and Bunkering (Ship-to-ship and Shore-to-ship)
- ISO Container
- By Application
- Transportation (Road and Marine Bunkering)
- Industrial Feedstock
- Power Generation
- Other Applications
- By End-User
- Utilities and Independent Power Producers (IPPs)
- Oil nd Gas Upstream Operators
- Manufacturing Industries
- Commercial and Municipal
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Qatar
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific owned 47.9% of the small-scale LNG market in 2025 and is growing at a 15.9% CAGR through 2031. China's 1.2 million LNG trucks, Indonesia's virtual pipelines supplying 12 new city-gas municipalities, and Australia's remote mining demand anchor regional growth. Japan's Sodegaura added truck-loading in 2024 to feed factories in Chiba, while India imported 80,000 tonnes via ISO tanks to reach states beyond pipeline corridors. Europe's pipeline saturation curbs liquefaction investment, yet the region leads in bunkering and FSRUs. FuelEU Maritime penalties starting in 2025 push shipowners toward LNG, and 29 bunker vessels handled 1,200 calls in 2024. Germany's four FSRUs replaced Russian gas volumes, keeping spot prices below EUR 40 per MWh. Nordic countries achieved a 22% bioLNG share in 2024, proving the pathway to carbon-negative shipping fuel.
North America leverages shale gas abundance and the Inflation Reduction Act credits. Chart Industries' micro-liquefiers at breweries and ethanol plants qualify for USD 1.75 per gallon-equivalent incentives, while Canadian rail moves LNG to remote communities. Mexico's 2024 reform opened import terminals to third parties, setting the stage for future growth. South America is nascent but active. New Fortress Energy's floating liquefiers target Brazil's pre-salt gas, and Argentina's 0.5 MTPA plant will serve domestic and Chilean markets. Chile dispatches LNG to Atacama mines, saving Codelco USD 18 million annually. Colombia awarded a terminal concession on its Pacific coast to supply Buenaventura and Tumaco.
In the Middle East and Africa, the UAE and Qatar build domestic bunkering networks, while South Africa's Coega FSRU serves the coastal industry. Mozambique's Coral Sul exports LNG but plans 100,000 tonnes per year for regional ISO-tank distribution starting 2026. Nigeria's virtual-pipeline concept awaits standardized ISO-tank rules. Kenya and Tanzania seek financing for import terminals but face credit hurdles.
- Linde plc
- Wartsila Oyj Abp
- Baker Hughes Co.
- Honeywell UOP
- Chart Industries Inc.
- Black & Veatch
- New Fortress Energy LLC
- Shell plc
- TotalEnergies SE
- Eni SpA
- PJSC Gazprom
- Novatek PJSC
- Gasum Oy
- Engie SA
- Anthony Veder Group NV
- Stolt-Nielsen Gas Ltd
- Eagle LNG Partners
- Guanghui Energy Co.
- Equinor ASA
- Pavilion Energy Pte Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening IMO & FuelEU Maritime Sulphur Caps Accelerating Marine LNG Bunkering Adoption (Europe)
- 4.2.2 Rapid Build-out of Modular Liquefaction Plants for Remote Mining & Off-Grid Power (Asia-Pacific)
- 4.2.3 Heavy-Duty Truck Fleet Shift to LNG in China's "Blue Corridor" Program
- 4.2.4 Caribbean & Central-American Micro-grid Conversions to LNG-to-Power
- 4.2.5 Tax Incentives for Small-Scale LNG Equipment under US Inflation Reduction Act
- 4.2.6 Nordic LNG Bus & Ferry Subsidy Schemes Driving Demand for Bunkering
- 4.3 Market Restraints
- 4.3.1 Sparse ISO-Tank Back-haul Logistics in Sub-Saharan Africa
- 4.3.2 High Boil-Off & Re-liquefaction Costs Below 0.05 MTPA Plants
- 4.3.3 Fragmented Permitting Framework for Mobile Liquefiers in Brazil
- 4.3.4 Russia-Ukraine Conflict Raising Geopolitical Risk Premium on Spot LNG
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Liquefaction Terminal (Micro, Mini, and Small)
- 5.1.2 Regasification Terminal (Onshore and Offshore FSRU)
- 5.2 By Mode of Supply
- 5.2.1 Truck
- 5.2.2 Pipeline and Rail
- 5.2.3 Transshipment and Bunkering (Ship-to-ship and Shore-to-ship)
- 5.2.4 ISO Container
- 5.3 By Application
- 5.3.1 Transportation (Road and Marine Bunkering)
- 5.3.2 Industrial Feedstock
- 5.3.3 Power Generation
- 5.3.4 Other Applications
- 5.4 By End-User
- 5.4.1 Utilities and Independent Power Producers (IPPs)
- 5.4.2 Oil nd Gas Upstream Operators
- 5.4.3 Manufacturing Industries
- 5.4.4 Commercial and Municipal
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Spain
- 5.5.2.5 Nordic Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Malaysia
- 5.5.3.6 Thailand
- 5.5.3.7 Indonesia
- 5.5.3.8 Vietnam
- 5.5.3.9 Australia
- 5.5.3.10 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Colombia
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Qatar
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Linde plc
- 6.4.2 Wartsila Oyj Abp
- 6.4.3 Baker Hughes Co.
- 6.4.4 Honeywell UOP
- 6.4.5 Chart Industries Inc.
- 6.4.6 Black & Veatch
- 6.4.7 New Fortress Energy LLC
- 6.4.8 Shell plc
- 6.4.9 TotalEnergies SE
- 6.4.10 Eni SpA
- 6.4.11 PJSC Gazprom
- 6.4.12 Novatek PJSC
- 6.4.13 Gasum Oy
- 6.4.14 Engie SA
- 6.4.15 Anthony Veder Group NV
- 6.4.16 Stolt-Nielsen Gas Ltd
- 6.4.17 Eagle LNG Partners
- 6.4.18 Guanghui Energy Co.
- 6.4.19 Equinor ASA
- 6.4.20 Pavilion Energy Pte Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment