

|
시장보고서
상품코드
2122022
레이더 시스템 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Radar Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
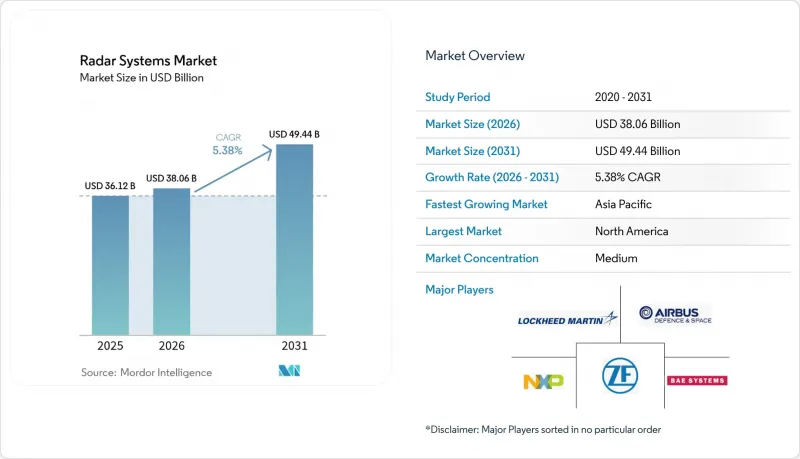
에 의하면, 레이더 시스템 시장 규모는 2025년 361억 2,000만 달러에서 2026년에는 380억 6,000만 달러에 이르고, 2026-2031년 CAGR 5.38%로 성장을 지속하여 2031년에는 494억 4,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 유형(연속파 및 펄스파), 구성 요소(안테나 모듈, 송수신 모듈,전력 증폭기, 신호 프로세서, 소프트웨어 및 서비스), 용도(항공기 탑재형, 지상형, 함정 탑재형), 최종 사용자 산업(항공, 해운, 자동차, 군 및 방위), 지역별로 분류되어 있습니다. 시장 예측은 달러(USD) 기준 금액으로 제시되어 있습니다.
세계 레이더 시스템 시장 동향 및 인사이트
전 세계 국방 예산의 확대
각국의 국방부는 차세대 센서에 대한 자금 투자를 지속하고 있습니다. 미국 국방부는 2025 회계연도에 저고도 공역·미사일 방어 센서에 17억 달러, 진행 중인 AN/SPY-6 생산에 5억 3,700만 달러를 배정했습니다. 유럽에서도 유사한 움직임이 나타나고 있으며, 라트비아와 슬로베니아는 통합 방공 체계를 강화하기 위해 1억 유로(1억 900만 달러) 상당의 HENSOLDT사 TRML-4D 시스템을 발주했습니다. 아시아태평양에서는 한화시스템의 KF-21 전투기 및 L-SAM II 미사일 배터리용 AESA 레이더 계약을 통해 국방 투자가 가속화되고 있습니다. NATO의 표준화 협정 등 다자간 프레임워크는 국경을 초월한 기술 유통을 원활하게 하고, 대량 조달을 통한 효율화를 뒷받침하고 있습니다.
자동차용 ADAS 레이더의 급속한 보급
각 자동차 제조업체들은 레이더 노드의 용도를 어댑티브 크루즈 컨트롤에서 360도 전방위 환경 인식으로 확대되고 있습니다. Arbe Robotics와 NVIDIA는 레벨 3 자율주행 요건을 충족하기 위해 고도와 속도를 매핑하는 4D 이미징 레이더 개발에 협력했습니다. NXP 세미컨덕터스는 Bitsensing과 제휴하여 여러 차종에 걸쳐 안전 기능의 해상도를 높이고 지연 시간을 줄이는 데 주력하고 있습니다. 규제 추진이 그 시급성을 더욱 높이고 있습니다. 유럽 규제에서는 모든 신차에 첨단 긴급 제동 시스템의 탑재가 의무화되어 있으며, 미국 국가도로교통안전국(NHTSA)도 유사한 제안을 발표했습니다. 77-81GHz 대역으로의 전환을 통해 더 높은 거리 분해능과 안테나 설치 면적의 소형화가 실현되어 대중 시장으로의 확대가 가능해집니다.
높은 초기 도입 비용과 수명 주기 비용
고성능 AESA 레이더는 예산을 압박하고 있습니다. 이집트의 AN/TPS-78 1기 도입 계약액은 3억 400만 달러에 달했으며, 코트디부아르의 GM200 레이더 비용은 5,000만 유로(5,450만 달러)였습니다. 조달 외에도 갈륨 질화물 모듈의 유지보수 및 전문적인 교정으로 인해 총 소유 비용이 장기화되고 있습니다. 머큐리 시스템즈(Mercury Systems)는 850만 달러 규모의 국방부 계약을 통해 레이더 어셈블리의 크기, 무게, 전력 소비를 80% 줄이는 것을 목표로 하고 있으며, 이는 수명 주기 비용 절감을 향한 업계의 움직임을 여실히 보여주고 있습니다.
부문 분석
2025년, 펄스파 방식은 AN/SPY-6 및 TPY-2와 같은 장거리 미사일 방어 레이더에 힘입어 레이더 시스템 시장 점유율의 60.48%를 차지했습니다. 펄스파 기술은 뛰어난 피크 출력과 레인지 게이트 식별 능력 덕분에 전략적 조기 경보 임무의 기반으로 계속 자리 잡고 있습니다. 한편, 연속파(CW) 방식은 자동차용 ADAS, 소형 UAV의 감지 및 회피 기능, 그리고 소형 해상 안전 설비에 대한 적합성을 반영하여 연평균 성장률(CAGR) 5.74%를 나타낼 것으로 예측됩니다. Arbe Robotics의 4D 이미징 레이더 솔루션은 주파수 변조 연속파(FMCW) 방식을 활용하여 고정밀 고도 데이터를 제공함으로써, 레벨 3 자율주행 프로그램 전반에 걸친 채택을 촉진하고 있습니다.
연속파 레이더는 크기, 무게, 전력 소비를 줄여 공간 제약이 있는 플랫폼에 쉽게 통합할 수 있게 해줍니다. 레오나르도(Leonardo)사의 ‘오스프리(Osprey)’ 시리즈는 무인 항공기용으로 낮은 SWaP 성능을 발휘하고 있습니다. 77-81GHz 대역의 규제상 주파수 할당은 연속파 방식의 자동차용 센서에 유리하게 작용하여 양산 시 경제성을 높이고 있습니다. 향후 5년 동안 자동차, 드론, 인프라에 대한 도입이 기존의 국방 지출을 초과함에 따라, 레이더 시스템 시장 매출에서 두 아키텍처 간의 비중 차이는 줄어들 것으로 예측됩니다.
2025년에는 안테나 모듈이 총 매출의 32.35%를 차지할 것으로 예상되며, 이는 동시 다중 임무 운용을 가능하게 하는 질화갈륨(GaN) 송수신 모듈에 의해 주도된 결과입니다. 위상 배열의 밀도가 높아짐에 따라, 안테나 타일에는 제어, 보정 및 상태 모니터링용 센서가 통합되어 서브시스템의 가치를 높이고 있습니다. 송수신 모듈 및 전력 증폭기 모듈은 더 높은 열 여유를 확보하기 위해 비소 갈륨에서 질화 갈륨으로 전환되고 있는 반면, 혼합 신호 RFIC의 집적화로 인해 기판 수가 감소하고 있습니다.
소프트웨어 및 서비스는 AI를 활용한 위협 분류, 레이더 데이터 분석, 클라우드 호스팅형 후처리에 힘입어 2031년까지 연평균 성장률(CAGR) 5.89%로 성장할 전망입니다. RTX사의 ‘Cognitive Aircraft Defense System’과 같은 AI 프레임워크는 전자기 환경에 대한 실시간 학습을 입증하고 있습니다. 조달이 ‘서비스형 기능(Capability-as-a-Service)’ 모델로 전환됨에 따라, 벤더들은 알고리즘 업데이트 및 사이버 보안 패치 제공을 통해 지속적인 수익을 확보하고 있습니다. FCC 인증 및 ISO-9001 품질 감사를 포함한 규제 준수는 전문 서비스에 대한 수요를 촉진하고, 생태계의 수익화를 가속화하고 있습니다.
지역별 분석
북미는 2025년 매출의 36.94%를 차지하고 있으며, 그 배경에는 미국 국방부의 2025 회계연도 8,498억 달러 예산 배정과 FAA(연방항공청)의 80억 달러 규모 레이더 업데이트 프로그램이 있습니다. 캐나다는 NORAD(북미항공우주방위사령부)의 업그레이드를 추진하고 있으며, 멕시코는 항공 교통 관리 및 연안 감시에 투자하고 있습니다. 자동차 분야의 도입은 미국 및 캐나다의 EV(전기차) 생산 확대와 병행하여 진행되며, 센서 수요를 뒷받침하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 6.09%를 기록하며 가장 빠르게 성장하는 지역입니다. 중국은 50기 이상의 X-밴드 위상 배열 기상 레이더를 배치하고, 남중국해의 CIIS(통합 정보 감시 시스템)를 위한 해상 감시에 투자하고 있습니다. 한국의 한화시스템은 KF-21 및 L-SAM II에 AESA 유닛을 공급하고 있으며, 일본은 전투기용 레이더 업그레이드를 가속화하고 있습니다. 77-81GHz 대역에 대한 규제 명확화에 힘입어, 국내 전기차 및 자율주행차 플랫폼에 자동차용 레이더 도입이 가속화되고 있습니다.
유럽에서는 NATO의 노력과 ‘단일 유럽 영공(Single European Sky)’의 현대화를 중심으로 착실한 보급이 진행되고 있습니다. 라트비아와 슬로베니아는 1억 유로(1억 900만 달러) 상당의 TRML-4D 유닛을 발주한 반면, 레오나르도사의 ECRS Mk2는 ‘타이푼’ 전투기에서 첫 비행을 완료했습니다. 탈레스(Thales)사의 GM400a 레이더는 발트 3국의 방어 체계를 강화하고 있습니다. 독일, 프랑스, 이탈리아에서 첨단 운전자 보조 시스템(ADAS)의 의무화로 인해 자동차용 레이더의 보급이 가속화되며, 다양한 부문에 걸친 수요가 더욱 증가하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the radar systems market size is expected to grow from USD 36.12 billion in 2025 to USD 38.06 billion in 2026 and is forecast to reach USD 49.44 billion by 2031 at 5.38% CAGR over 2026-2031.
This report is Segmented by Type (Continuous Wave, and Pulsated Wave), Component (Antenna Modules, Transmit-Receive Modules, Power Amplifiers, Signal Processors, and Software and Services), Application (Airborne, Land-Based, and Naval), End-User Industry (Aviation, Maritime, Automotive, and Military and Defense), and Geography. The Market Forecasts are Provided in Terms of Value USD.
Global Radar Systems Market Trends and Insights
Escalating Global Defense Budgets
Defense ministries continue to channel funding toward next-generation sensors. The United States Department of Defense allocated USD 1.7 billion for the Lower Tier Air and Missile Defense Sensor and USD 537 million for ongoing AN/SPY-6 production in fiscal-year 2025. Similar momentum is visible in Europe, where Latvia and Slovenia ordered HENSOLDT TRML-4D systems worth EUR 100 million (USD 109 million) to reinforce integrated air defense. Asia Pacific defense investment is accelerating through Hanwha Systems' AESA radar contracts for the KF-21 fighter and L-SAM II missile battery. Multilateral frameworks, such as NATO standardization agreements, ease cross-border technology flow and support volume procurement efficiencies.
Rapid Adoption of Automotive ADAS Radar
Automotive manufacturers are extending radar nodes from adaptive cruise control to full 360-degree perception. Arbe Robotics and NVIDIA cooperated on a 4D imaging radar that maps elevation and velocity for Level-3 autonomy requirements. NXP Semiconductors partnered with Bitsensing to raise resolution and reduce latency for safety functions across multiple vehicle classes. Regulatory push adds urgency: European rules mandate advanced emergency braking in all new cars, and the U.S. National Highway Traffic Safety Administration promulgated similar proposals. Transition to the 77-81 GHz band provides higher range resolution and smaller antenna footprints, enabling mass-market deployment.
High Upfront Acquisition and Lifecycle Costs
Premium AESA radars strain budgets. Egypt's order for a single AN/TPS-78 installation reached USD 304 million, and the Ivory Coast's GM200 radar cost EUR 50 million (USD 54.5 million). Beyond procurement, gallium nitride module maintenance and specialized calibration prolong the total cost of ownership. Mercury Systems is targeting an 80% reduction in radar assembly size, weight, and power under a USD 8.5 million Department of Defense contract, illustrating industry moves to compress lifecycle expense
Other drivers and restraints analyzed in the detailed report include:
- Air-Traffic Control Modernization Programmes
- Increasing Demand for Advanced Weather Surveillance
- Radio-Frequency Spectrum Congestion and Allocation Barriers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The pulsated wave category accounted for 60.48% of radar systems market share in 2025, supported by long-range missile defense radars such as AN/SPY-6 and TPY-2. Pulsated wave technology continues to anchor strategic early-warning missions due to its superior peak power and range-gate discrimination. Continuous wave designs, however, are forecast to register a 5.74% CAGR, reflecting their suitability for automotive ADAS, small UAV sense-and-avoid, and compact maritime safety installations. 4D imaging radar solutions from Arbe Robotics capitalize on frequency-modulated continuous wave modulation to deliver precise elevation data, promoting adoption across Level-3 autonomy programs.
Continuous wave radars reduce size, weight, and power, easing integration in space-constrained platforms. Leonardo's Osprey family demonstrates low-SWaP performance for unmanned aerial vehicles. Regulatory allocation in the 77-81 GHz band favors continuous wave automotive sensors, reinforcing volume production economics. Over the next five years, the radar systems market size revenue split between the two architectures is expected to narrow as automotive, drone, and infrastructure deployments outpace traditional defense spending.
Antenna modules anchored 32.35% of the overall revenue in 2025, propelled by gallium nitride transmit-receive modules enabling simultaneous multi-mission operations. As phased-array density climbs, antenna tiles integrate control, calibration, and health-monitoring sensors, boosting subsystem value. Transmit-receive and power amplifier modules transition from gallium arsenide to gallium nitride for higher thermal margins, while mixed-signal RFIC integration shrinks board count.
Software and services will rise at 5.89% CAGR through 2031, buoyed by AI-driven threat classification, radar-data analytics, and cloud-hosted post-processing. AI frameworks such as RTX Corporation's Cognitive Aircraft Defense System demonstrate real-time electromagnetic environment learning. As procurement migrates to capability-as-a-service models, vendors secure recurring revenue through algorithm updates and cybersecurity patches. Regulatory compliance, including FCC certification and ISO-9001 quality audits, stimulates demand for professional services, accelerating ecosystem monetization.
Complete Report Scope:
- By System Type
- Continuous Wave Radar Systems
- Pulsated Wave Radar Systems
- By Component
- Antenna Modules
- Transmit-Receive Modules
- Power Amplifiers and Oscillators
- Signal Processors and Controllers
- Software and Services
- By Application
- Airborne
- Land-based
- Naval
- By End-user Industry
- Aviation
- Maritime Applications
- Automotive
- Military and Defense
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- North America
Geography Analysis
North America held 36.94% of 2025 revenue, underpinned by the United States Department of Defense's USD 849.8 billion fiscal-year 2025 allocation and the FAA's USD 8 billion radar replacement program. Canada advances NORAD upgrades, while Mexico invests in air-traffic management and coastal surveillance. Automotive adoption grows in tandem with U.S. and Canadian EV manufacturing, supporting sensor demand.
Asia Pacific is the fastest-growing region at 6.09% CAGR. China fielded more than 50 X-band phased-array weather radars and invests in maritime surveillance for the South China Sea CIIS. South Korea's Hanwha Systems supplies AESA units to the KF-21 and L-SAM II, and Japan accelerates fighter radar upgrades. Automotive radar deployment accelerates on domestic electric and autonomous vehicle platforms, supported by regulatory clarity in the 77-81 GHz band.
Europe sees steady uptake, anchored by NATO commitments and Single European Sky modernization. Latvia and Slovenia ordered EUR 100 million (USD 109 million) of TRML-4D units, while Leonardo's ECRS Mk2 completed its first Typhoon flight. Thales GM400a radars bolster Baltic defense. Advanced driver-assistance mandates in Germany, France, and Italy accelerate automotive radar penetration, reinforcing cross-segment demand.
- Lockheed Martin Corporation
- RTX Corporation
- Thales Group
- Leonardo S.p.A.
- Saab AB
- Israel Aerospace Industries Ltd.
- Northrop Grumman Corporation
- BAE Systems plc
- Airbus SE
- General Dynamics Corporation
- NXP Semiconductors N.V.
- Infineon Technologies AG
- HENSOLDT AG
- Rohde and Schwarz GmbH and Co KG
- Teledyne FLIR LLC
- Mitsubishi Electric Corporation
- Honeywell International Inc.
- Bharat Electronics Limited
- Fujitsu Limited
- Indra Sistemas S.A.
- Reutech Radar Systems (Pty) Ltd.
- Terma A/S
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Technological Outlook
- 4.3 Impact of Macroeconomic Factors
- 4.4 Market Drivers
- 4.4.1 Escalating global defence budgets
- 4.4.2 Rapid adoption of automotive ADAS radar
- 4.4.3 Air-traffic control modernisation programmes
- 4.4.4 Increasing demand for advanced weather surveillance
- 4.4.5 Miniaturised radar for small-UAV integration
- 4.4.6 AI-enabled digital beamforming-based radars
- 4.5 Market Restraints
- 4.5.1 High upfront acquisition and lifecycle costs
- 4.5.2 Radio-frequency spectrum congestion and allocation barriers
- 4.5.3 Supply-chain tightness for GaN power devices
- 4.5.4 Cyber-security vulnerabilities in network-connected radar nodes
- 4.6 Industry Ecosystem Analysis
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By System Type
- 5.1.1 Continuous Wave Radar Systems
- 5.1.2 Pulsated Wave Radar Systems
- 5.2 By Component
- 5.2.1 Antenna Modules
- 5.2.2 Transmit-Receive Modules
- 5.2.3 Power Amplifiers and Oscillators
- 5.2.4 Signal Processors and Controllers
- 5.2.5 Software and Services
- 5.3 By Application
- 5.3.1 Airborne
- 5.3.2 Land-based
- 5.3.3 Naval
- 5.4 By End-user Industry
- 5.4.1 Aviation
- 5.4.2 Maritime Applications
- 5.4.3 Automotive
- 5.4.4 Military and Defense
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia Pacific
- 5.5.4 Middle East
- 5.5.4.1 Saudi Arabia
- 5.5.4.2 United Arab Emirates
- 5.5.4.3 Turkey
- 5.5.4.4 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Egypt
- 5.5.5.3 Nigeria
- 5.5.5.4 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Colombia
- 5.5.6.4 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes global level overview, market level overview, core segments, financials as available, strategic information, market rank/share for key companies, products and services, and recent developments)
- 6.4.1 Lockheed Martin Corporation
- 6.4.2 RTX Corporation
- 6.4.3 Thales Group
- 6.4.4 Leonardo S.p.A.
- 6.4.5 Saab AB
- 6.4.6 Israel Aerospace Industries Ltd.
- 6.4.7 Northrop Grumman Corporation
- 6.4.8 BAE Systems plc
- 6.4.9 Airbus SE
- 6.4.10 General Dynamics Corporation
- 6.4.11 NXP Semiconductors N.V.
- 6.4.12 Infineon Technologies AG
- 6.4.13 HENSOLDT AG
- 6.4.14 Rohde and Schwarz GmbH and Co KG
- 6.4.15 Teledyne FLIR LLC
- 6.4.16 Mitsubishi Electric Corporation
- 6.4.17 Honeywell International Inc.
- 6.4.18 Bharat Electronics Limited
- 6.4.19 Fujitsu Limited
- 6.4.20 Indra Sistemas S.A.
- 6.4.21 Reutech Radar Systems (Pty) Ltd.
- 6.4.22 Terma A/S
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


