

|
시장보고서
상품코드
2122184
약물감시 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Pharmacovigilance - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
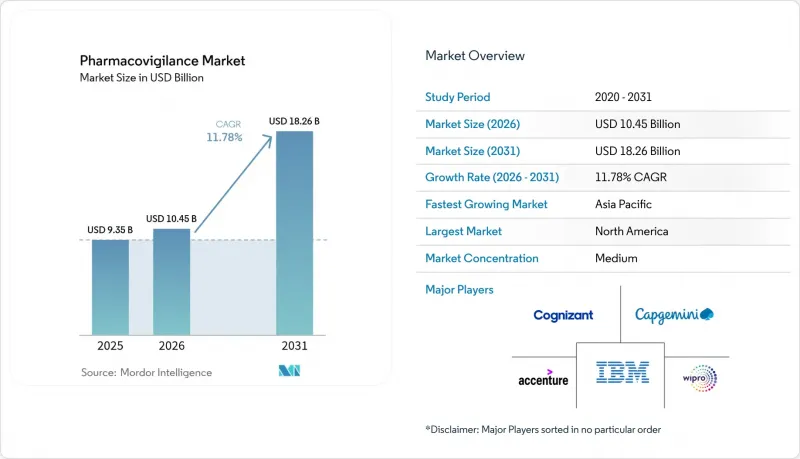
에 따르면 약물감시 시장 규모는 2025년에 93억 5,000만 달러로 평가되며, 2026년 104억 5,000만 달러에서 2031년까지 182억 6,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 11.78%에 달할 전망입니다.
이 보고서는 임상시험 단계(전임상, 제1상, 제2상 등), 서비스 제공자(사내, 외부 위탁), 보고 유형(자발적 보고, 강화된 이상반응 보고 등), 최종사용자(병원, 제약회사 등) 및 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
글로벌 의약품 안전성 감시 시장의 동향 및 인사이트
의약품 소비량 증가 및 개발 파이프라인 확대
FDA는 2024년에 50개의 신규 분자 실체를 승인했습니다. 이는 획기적인 승인이 모든 임상시험 의뢰자에게 시판 후 안전성에 대한 책임을 어떻게 확대하는지를 여실히 보여줍니다. 유전자 치료, CAR-T 치료 및 복합 제제는 제품 수명 주기 전반에 걸쳐 세심한 모니터링이 필요한 고유한 위험 프로필을 보입니다. 조건부 승인으로 인해 RWD(Real World Data)(RWE)에 대한 기대가 더욱 높아지면서, 예산은 지속적인 모니터링 인프라로 재배정되고 있습니다. 이러한 추세로 인해 의약품 안전성 모니터링 팀은 장기적인 확장 주기에 갇히게 되었으며, 임상 개발 단계를 넘어 업무량이 지속적으로 증가하고 있습니다.
약물 이상반응(ADR) 발생률 증가
유럽의약품청(EMA)의 의약품 안전성 위험 평가 위원회(PRAC)는 최근 이차성 악성 종양의 가능성이 확인됨에 따라 CAR-T 치료를 받은 환자에 대한 평생 모니터링의 중요성을 강조했습니다. 고령층에서의 다제 병용은 약물 상호작용을 증가시켜 ADR 발생 건수를 끌어올리고 있습니다. 팬데믹 상황에서의 백신 접종 확대는 수주 내에 수백만 건의 안전성 보고를 처리할 수 있는 대규모 신호 탐지 네트워크의 중요성을 입증했습니다.
사이버 보안 및 데이터 개인정보 보호 위험
기밀성이 높은 환자 데이터를 클라우드에 배포하면 보안 시스템이 랜섬웨어나 국가 주체의 침입 위협에 노출됩니다. 최근 의료 분야에서 발생한 정보 유출 사건으로 인해 여러 후원사가 전자 건강 기록(EHR)과의 연동을 일시 중단할 수밖에 없었으며, 감사를 통해 안전 신호의 변조가 이루어지지 않았음이 확인되었습니다. 일반 데이터 보호 규정(GDPR) 및 유사한 법률에서는 데이터 최소화 및 현지화 전략을 의무화하고 있지만, 이는 글로벌 분석 목표와 상충될 수 있습니다.
부문 분석
2025년, 4상 임상시험은 의약품 안전성 모니터링 시장의 32.05%를 차지하며, 혁신적인 치료법에 대한 평생 모니터링을 요구하는 규제 당국의 필요성을 반영하고 있습니다. 위험 기반의 초기 단계 분석 덕분에, 전임상 안전성 평가와 관련된 의약품 안전성 모니터링 시장 규모는 연평균 성장률(CAGR) 12.88%로 확대될 것으로 예측됩니다. 적응형 임상시험 설계는 2상 및 3상 임상시험 기간을 단축하지만, 제품이 일반 환자층에 널리 보급되면 고정밀 신호 탐지의 중요성이 커집니다. 개정된 ICH E6(R3) 지침에 따라 후원사는 모든 단계에 걸쳐 ‘품질 설계(QbD)’ 지표를 통합해야 하며, 인간에 대한 첫 투여부터 추적 가능한 안전성 데이터의 수집이 보장됩니다.
이에 대응하여 의약품 안전성 모니터링 시장에서는 분산형 임상시험과 환자 직접 샘플링, 웨어러블 센서를 통합하는 움직임이 진행되고 있습니다. AI 모델은 첫 번째 환자에게 투여하기 전에 오프타겟 효과를 시뮬레이션하여, 기업이 위험 관리 계획 수립에 앞서 나갈 수 있는 환경을 조성하고 있습니다. 조건부 승인이 증가함에 따라 승인 후 안전성 연구(PASS) 예산은 기존의 3상 임상시험 지출을 상회하게 되며, 4상 임상시험이 장기적인 전망에서 주도적인 위치를 계속 차지하게 될 것입니다.
2025년에는 계약 아웃소싱이 총 수익의 54.88%를 차지하고, 2031년까지 연평균 13.48%의 성장률을 기록할 것으로 예측되어, 의약품 안전성 모니터링 시장에서 최대 점유율을 유지할 전망입니다. 사내 부서는 중요한 의사결정권을 유지하면서도 일상적인 업무를 CRO 플랫폼에 위탁하는 하이브리드 모델에 대한 의존도를 높이고 있습니다. 파렉셀과 팔란티아 간에 체결된 다년간의 AI 제휴와 같은 전략적 제휴는 기술을 활용하는 CRO가 어떻게 경쟁 우위를 구축하고 있는지를 여실히 보여줍니다.
현재 의약품 안전성 모니터링 업계에서는 확장성이 뛰어난 데이터 레이크, 과학 문헌을 위한 자연 언어 처리(NLP), 그리고 데이터 수집에 있으며, 로봇을 활용한 프로세스 자동화가 중시되고 있습니다. 그 결과, 대형 제약사들조차 인도, 아일랜드, 동유럽의 해외 허브로 업무를 이전하고, 분산되어 있던 공급업체 리스트을 통합하며, AI 투자 로드맵을 보장하는 포괄적인 서비스 계약을 체결하고 있습니다.
지역별 분석
북미는 높은 연구개발(R&D) 집중도, 전자건강기록(EHR)의 높은 보급률, 그리고 명확한 규제 요건 덕분에 2025년에 의약품 안전성 모니터링 시장의 43.62%를 차지했습니다. FDA가 단계적 검증 프레임워크를 발표함에 따라 AI 시범 프로젝트가 빠르게 수용되었으며, 이 지역은 디지털 의약품 안전성 모니터링의 세계적 표준으로서의 입지를 확립하고 있습니다.
유럽은 이에 이어 EudraVigilance 네트워크를 지원하는 성숙한 법규와, 알고리즘의 투명성을 요구하면서도 혁신을 장려하는 새로운 AI 관련 검토 문서가 마련되어 있습니다. 첨단 치료 의약품(ATMP)에 대한 관심이 높아짐에 따라 전문적인 모니터링 수요가 발생하고 있으며, 2030년까지 투자가 지속될 것으로 예상됩니다. EU에 기반을 둔 PASS의 의약품 안전성 감시 시장 규모는 희귀질환 치료제 승인 건수의 증가에 따라 확대되고 있습니다.
아시아태평양은 중국의 규제 개혁과 인도의 임상시험 환경 확대가 맞물려, 세계 최고 수준인 연평균 성장률(CAGR) 13.12%를 기록할 것으로 예측됩니다. 아세안(ASEAN) 국가들은 표시 기준 및 전자 신청 기준을 통일하여, 여러 국가에 걸친 안전성 캠페인을 간소화하고 있습니다. 국내 생명공학 제조에 대한 투자는 지역 밀착형 사례 처리 허브에 대한 수요를 자극하고 있습니다. 중동 및 아프리카 및 남미에서는 의약품 수입량과 신흥 제조 클러스터의 확대에 따라 의약품 안전성 감시 인프라가 정비되어 추가적인 성장이 예상됩니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the pharmacovigilance market size was valued at USD 9.35 billion in 2025 and estimated to grow from USD 10.45 billion in 2026 to reach USD 18.26 billion by 2031, at a CAGR of 11.78% during the forecast period (2026-2031).
This report is Segmented by Clinical Trial Phase (Preclinical, Phase I, Phase II, and More), Service Provider (In-House, Contract Outsourcing), Type of Reporting (Spontaneous Reporting, Intensified ADR Reporting, and More), End User (Hospitals, Pharmaceutical Companies, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Pharmacovigilance Market Trends and Insights
Increasing Drug Consumption & Development Pipeline
The FDA cleared 50 new molecular entities in 2024, underscoring how breakthrough approvals widen post-marketing safety duties for every sponsor. Gene therapies, CAR-T treatments and combination products pose unique risk profiles that require vigilant monitoring throughout the product life cycle. Conditional approvals further heighten real-world evidence (RWE) expectations, redirecting budgets toward continuous surveillance infrastructures. These dynamics lock pharmacovigilance teams into a long-term expansion cycle that sustains workload growth beyond clinical development.
Growing Incidence Of Adverse Drug Reactions (ADRs)
The European Medicines Agency (EMA) Pharmacovigilance Risk Assessment Committee (PRAC) recently emphasized lifelong monitoring for CAR-T recipients after observing potential secondary malignancies. Polypharmacy in elderly populations multiplies drug-drug interactions, pushing ADR case volumes higher. The pandemic-era vaccine rollout validated the importance of large-scale signal-detection networks capable of processing millions of safety reports within weeks.
Cyber-Security & Data-Privacy Risks
Cloud deployment of sensitive patient data exposes safety systems to ransomware and nation-state intrusions. Recent healthcare breaches forced several sponsors to suspend EHR integrations while audits ensured no safety signal manipulation occurred. General Data Protection Regulation (GDPR) and similar laws mandate data-minimization and localization strategies that sometimes conflict with global analytics ambitions.
Other drivers and restraints analyzed in the detailed report include:
- Outsourcing Of PV Services To CRO/BPO Vendors
- AI-Enabled Signal Detection & Predictive Analytics
- Shortage Of Specialised PV Talent & High Staff Turnover
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Phase IV studies held 32.05% of pharmacovigilance market share in 2025, reflecting regulators' demand for life-long monitoring of innovative therapies. The pharmacovigilance market size attached to pre-clinical safety assessments is projected to expand at a 12.88% CAGR thanks to risk-based early-phase analytics. Adaptive trial designs shorten Phases II and III, but heighten the importance of high-fidelity signal detection once products reach broad populations. Updated ICH E6(R3) guidelines compel sponsors to embed quality-by-design metrics across all phases, ensuring traceable safety data capture from first-in-human dosing.
The pharmacovigilance market responds by integrating decentralized trials with direct-to-patient sampling and wearable sensors. AI models simulate off-target effects before first-patient dosing, giving companies a head start in risk-management planning. As conditional approvals rise, Post-Authorization Safety Studies (PASS) budgets eclipse traditional Phase III spends, locking Phase IV dominance into the long-term outlook.
Contract outsourcing controlled 54.88% of overall revenue in 2025 and is forecast to grow at 13.48% through 2031, sustaining the largest slice of the pharmacovigilance market. In-house units retain critical decision-making but increasingly rely on hybrid models where CRO platforms process routine tasks. Strategic alliances such as Parexel's multi-year AI pact with Palantir exemplify how tech-enhanced CROs cultivate competitive edge.
The pharmacovigilance industry now values scalable data lakes, natural language processing (NLP) for scientific literature and robotic process automation in intake. As a result, even large pharmaceutical companies migrate workloads to external hubs in India, Ireland and Eastern Europe, consolidating fragmented vendor lists into master service agreements that guarantee AI investment roadmaps.
Complete Report Scope:
- By Clinical Trial Phase
- Pre-clinical
- Phase I
- Phase II
- Phase III
- Phase IV
- By Service Provider
- In-house
- Contract Outsourcing
- By Type of Reporting
- Spontaneous Reporting
- Intensified ADR Reporting
- Targeted Spontaneous Reporting
- Cohort Event Monitoring
- EHR Mining
- By End-User
- Hospitals
- Pharmaceutical Companies
- CROs & Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 43.62% of the pharmacovigilance market in 2025 due to high R&D intensity, advanced EHR penetration and clear regulatory expectations. AI pilots gain rapid acceptance as the FDA publishes step-wise validation frameworks, positioning the region as the global reference for digital pharmacovigilance.
Europe follows with mature legislation underpinning the EudraVigilance network and new AI reflection papers that encourage innovation while demanding algorithm transparency. Focus on Advanced Therapy Medicinal Products brings specialized monitoring needs, sustaining investment through 2030. The pharmacovigilance market size for EU-based PASS grows alongside orphan-drug approvals.
Asia-Pacific is projected to log a 13.12% CAGR, the fastest worldwide, as China's regulatory reforms and India's expanded clinical-trial landscape converge. ASEAN nations align labeling and electronic submission standards, simplifying multi-country safety campaigns. Investments in domestic biotech manufacturing stimulate demand for localized case-processing hubs. Middle East & Africa and South America add incremental growth where pharmacovigilance infrastructure scales with pharmaceutical import volumes and emerging manufacturing clusters.
- Accenture
- Aris Global
- BioClinica (NOW Clario)
- Capgemini
- Cognizant
- IBM
- ICON
- IQVIA
- ITClinical
- LabCorp
- Linical Accelovance
- Parexel International
- UBC (United BioSource)
- TAKE Solutions (Navitas Life Sciences)
- Wipro
- Oracle Health Sciences
- Ennov
- Extedo
- Clarivate (Drug Safety Triager)
- SGS Life Sciences
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Drug Consumption & Development Pipeline
- 4.2.2 Growing Incidence Of Adverse Drug Reactions (ADRS)
- 4.2.3 Outsourcing Of Pv Services To CRO/BPO Vendors
- 4.2.4 AI-Enabled Signal Detection & Predictive Analytics
- 4.2.5 Expansion Of Real-World Evidence (RWE) Platforms
- 4.2.6 Stringent Regulatory Mandates For Proactive Post-Marketing Safety Surveillance
- 4.3 Market Restraints
- 4.3.1 Cyber-Security & Data-Privacy Risks
- 4.3.2 Lack Of Global Regulatory Harmonisation & Data Standards
- 4.3.3 Shortage Of Specialised PV Talent & High Staff Turnover
- 4.3.4 Complexity Of Combination & ATMP Therapies
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Clinical Trial Phase
- 5.1.1 Pre-clinical
- 5.1.2 Phase I
- 5.1.3 Phase II
- 5.1.4 Phase III
- 5.1.5 Phase IV
- 5.2 By Service Provider
- 5.2.1 In-house
- 5.2.2 Contract Outsourcing
- 5.3 By Type of Reporting
- 5.3.1 Spontaneous Reporting
- 5.3.2 Intensified ADR Reporting
- 5.3.3 Targeted Spontaneous Reporting
- 5.3.4 Cohort Event Monitoring
- 5.3.5 EHR Mining
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.2 Pharmaceutical Companies
- 5.4.3 CROs & Other End-Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Accenture
- 6.3.2 ArisGlobal
- 6.3.3 BioClinica (NOW Clario)
- 6.3.4 Capgemini
- 6.3.5 Cognizant
- 6.3.6 IBM
- 6.3.7 ICON plc
- 6.3.8 IQVIA
- 6.3.9 ITClinical
- 6.3.10 Labcorp
- 6.3.11 Linical Accelovance
- 6.3.12 Parexel
- 6.3.13 UBC (United BioSource)
- 6.3.14 TAKE Solutions (Navitas Life Sciences)
- 6.3.15 Wipro
- 6.3.16 Oracle Health Sciences
- 6.3.17 Ennov
- 6.3.18 Extedo
- 6.3.19 Clarivate (Drug Safety Triager)
- 6.3.20 SGS Life Sciences
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


