

|
시장보고서
상품코드
2122237
정형외과용 보조기 및 지지대 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Orthopedic Braces And Supports - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
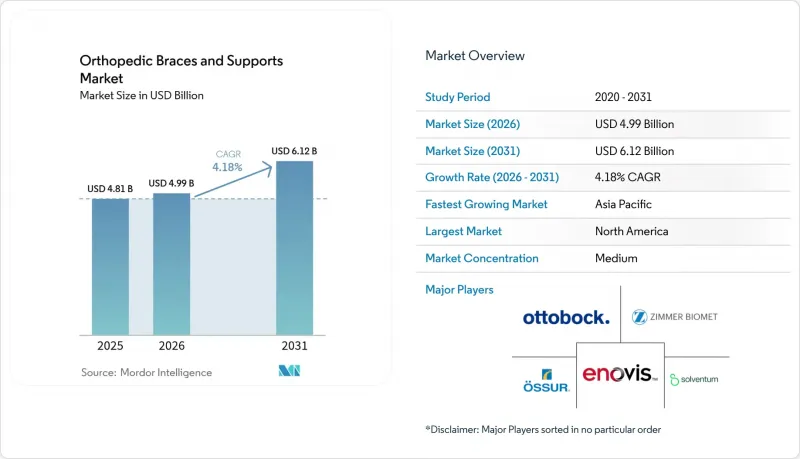
에 따르면 정형외과용 보조기·서포터 시장 규모는 2025년에 48억 1,000만 달러로 평가되며, 2026년 49억 9,000만 달러에서 2031년까지 61억 2,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 4.18%에 달할 전망입니다.
이 보고서는 제품 유형(무릎, 발목·발, 등·척추, 상지, 고관절·골반, 기타), 용도(인대 손상, 예방 관리, 수술 후 재활, 퇴행성 관절염, 기타 질환), 최종사용자(병원, 클리닉, 재택 간호,스포츠 센터) 및 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
전 세계 정형외과용 보조기 및 지지대 시장의 동향 및 인사이트
퇴행성 관절염 및 근골격계 질환(MSD) 유병률 증가
전 세계 퇴행성 관절염 유병률은 1990-2020년 사이 113% 증가했으며, 2050년까지 10억 건에 달할 것으로 예측되며, 무릎 및 고관절용 보조기에 대해 대규모의 지속적인 사용자 기반이 확보될 전망입니다. 아시아 및 라틴아메리카의 중소득 국가에서는 신규 사례의 대부분을 차지할 것으로 예상되며, 저비용 슬리브형 보조기가 주류를 이루는 반면, 북미의 성숙한 보험사에서는 맞춤형 하중 완화형 보조기에 대한 보험 적용이 이루어지고 있습니다. 2024년, 미국 질병통제예방센터(CDC)는 5,850만 명의 미국 성인이 관절염 진단을 받았음을 확인했으며, 이는 예측 가능한 보조기 교체 주기를 지원합니다. 가격대별로 제품 포트폴리오를 구분하는 공급업체는 자비 부담 수요와 보험이 적용되는 프리미엄 수요를 모두 확보할 수 있습니다. 이처럼 질환으로 인한 기본적인 교체 수요가 정형외과용 보조기·서포터 시장의 기반을 이루고 있습니다.
고령화의 진행
2025년까지 일본 인구의 29%가 65세 이상이 될 것으로 예상되며, 로봇식 보행 보조기와 호환되는 경량 발목 및 발 보조기의 필요성이 부각되고 있습니다. 전 세계에서 보아도 60세 이상 인구는 2025년에 14억 명에 달하며, 2050년까지 21억 명에 달할 전망입니다. 고령자는 1인당 보조기 소비율이 높은 반면, 보험사는 고액의 수술을 미루는 예방적 보조기 사용을 권장하고 있습니다. 유럽의 부양비율은 2025년 34%에서 2050년까지 57%로 상승하여 재정적 압박을 가중시키고 있으며, 이로 인해 이동 능력을 유지하기 위한 재택 지원에 대한 정책적 지원이 확대되고 있습니다.
첨단 보조기기의 높은 비용
맞춤형 하중 분산 보조기는 600-800달러, 스마트 보조기는 1,200달러를 넘는 가격대로 형성되어 있으며, 인도, 인도네시아, 브라질에서는 본인 부담으로 구매하는 소비자들에게는 감당하기 어려운 가격입니다. WHO 데이터에 따르면 35개 중저소득국(LMIC)에서 본인 부담금이 의료비의 50%를 초과하고 있으며, 고가 제품의 보급에는 한계가 있습니다. 오서(Osser)사의 폴리프로필렌 소재 ‘셀렉트(Select)’ 시리즈처럼, 재료비를 40% 절감한 단계적 제품 라인업은 이러한 격차를 해소하는 것을 목표로 하고 있습니다.
부문 분석
2025년, 무릎 보호대는 전방십자인대(ACL) 손상 및 무릎 내측 퇴행성 관절염의 광범위한 발생에 힘입어 정형외과용 보조기 및 지지대 시장에서 36.11%라는 압도적인 점유율을 유지했습니다. 그러나 어깨 및 팔꿈치 서포터를 필두로 한 상지용 기기는 2031년까지 연평균 성장률(CAGR) 6.06%로 성장할 것으로 예측되어, 다른 모든 카테고리를 능가할 전망입니다. 미국내 회전근개 재건술은 2024년에 전년 대비 8% 증가하여, 외전용 쿠션 및 슬링에 대한 지속적인 수요를 견인하고 있습니다. 또한 청소년 야구 지침에 따라 예방적 팔꿈치 보호대 착용이 더욱 보편화되면서 교체 주기가 연장되고 있습니다.
발목 및 발 보조기 시장은 저비용 탄성 슬리브와 발목 하수증용 맞춤형 발목 및 발 보조기 사이에서 양극화가 진행되고 있습니다. Zimmer Biomet사가 2025년에 Paragon 28사를 인수한 것은 해당 기업이 사지 전문 분야의 성장에 주력하고 있음을 보여줍니다. 요추·천추 부위 보조기의 경우, CMS(미국 의료보험서비스센터)의 급여 요건이 엄격해지면서 승인까지 걸리는 기간이 길어지고 있습니다. 틈새 시장인 고관절·골반용 솔루션은 여전히 수술 후 프로토콜에 얽매여 있으며, 퇴행성 관절염에 대한 보급은 제한적입니다.
지역별 분석
아시아태평양은 2026-2031년까지 연평균 성장률(CAGR) 7.27%를 기록할 것으로 예측되며, 다른 어떤 지역보다 높은 성장률을 보일 것으로 전망됩니다. 중국은 2024년에 클래스 II 보조기 심사 기간을 9개월로 단축하고, 서류 요건을 ISO 13485에 부합하도록 함으로써 다국적 기업의 시장 진입 장벽을 낮췄습니다. 인도의 ‘생산 연계 인센티브(PLI)’ 제도는 국내 매출 증가분에 대해 5%의 리베이트를 제공하여 글로벌 브랜드가 현지에서 생산 라인을 구축하도록 장려하고 있습니다. 일본의 초고령화 사회는 로봇 외골격과 호환되는 경량·슬림형 기기의 채택을 지원하며, 스마트 브레이스 분야의 발전을 촉진하고 있습니다.
북미는 메디케어의 DMEPOS 환급 제도를 기반으로 2025년에도 39.78%의 점유율을 유지했으나, 2028년부터 시작되는 전국적인 경쟁 입찰로 인해 향후 이익률 압박에 직면할 전망입니다. 유럽은 환급 제도에 따라 분열되어 있습니다. 웨일스에서는 2024년에 도입된 760만 파운드 규모의 체계를 통해 조달 비용을 12% 절감하는 동시에 프로세스 표준화도 도모했습니다. 중동에서는 주요 행사를 앞두고 스포츠 클리닉에 대한 투자가 진행되고 있습니다. 한편, 남미는 다른 길을 걷고 있습니다. 브라질에서는 SUS(브라질 공적 의료제도)에 의한 환급 범위가 확대되고 있는 반면, 아르헨티나에서는 통화 규제 속에서 현지 생산에 대한 유연한 지원을 우선시하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the orthopedic braces and supports market size was valued at USD 4.81 billion in 2025 and is estimated to grow from USD 4.99 billion in 2026 to reach USD 6.12 billion by 2031, at a CAGR of 4.18% during the forecast period (2026-2031).
This report is Segmented by Product Type (Knee, Ankle & Foot, Back & Spine, Upper-Extremity, Hip & Pelvic, Others), Application (Ligament Injury, Preventive Care, Post-Op Rehabilitation, Osteoarthritis, Other Conditions), End User (Hospitals, Clinics, Homecare, Sports Centers), and Geography (North America, Europe, Asia-Pacific, MEA, South America). Market Forecasts are in Value (USD).
Global Orthopedic Braces And Supports Market Trends and Insights
Rising Prevalence of Osteoarthritis & MSDs
Global osteoarthritis prevalence climbed 113% between 1990 and 2020 and is projected to reach 1 billion cases by 2050, ensuring a large, recurring user base for knee and hip bracing. Middle-income Asia and Latin America will supply most net new cases, favoring low-cost sleeves, whereas mature payers in North America reimburse custom unloaders. In 2024 the CDC confirmed 58.5 million U.S. adults carried an arthritis diagnosis, underpinning a predictable brace replacement cycle. Vendors that segment portfolios by price tier can capture both cash-pay demand and reimbursed premium demand. Disease-driven baseline turnover thus anchors the orthopedic braces and supports market.
Growing Geriatric Population
By 2025, 29% of Japan's population was aged 65 and older, underscoring the need for lightweight ankle-foot orthoses compatible with robotic gait aids. Globally, the 60-plus cohort hit 1.4 billion in 2025 and will reach 2.1 billion by 2050. Older adults consume braces at higher per-capita rates, yet payers encourage preventive bracing that delays costly surgery. Europe's dependency ratio, climbing from 34% in 2025 to 57% by 2050, heightens fiscal pressure, spurring policy support for home-based supports that maintain mobility.
High Cost of Sophisticated Braces
Custom unloaders cost USD 600-800, while smart braces top USD 1,200, pricing out self-pay buyers in India, Indonesia, and Brazil. WHO data show out-of-pocket spending exceeds 50% of health expenditure in 35 LMICs, capping premium penetration. Tiered offerings, such as Ossur's polypropylene "Select" line, which trims bill-of-materials by 40%, aim to bridge the gap.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Sports-Related Injuries
- Advancements in Lightweight Materials
- Reimbursement Hurdles for OTC Products
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Knee braces retained a commanding 36.11% share of the orthopedic braces and supports market in 2025, buoyed by widespread ACL injuries and medial knee osteoarthritis. However, upper-extremity devices, led by shoulder and elbow supports, are forecast to grow at a 6.06% CAGR through 2031, outstripping all other categories. Rotator cuff repairs in the United States rose 8% year-on-year in 2024, driving sustained demand for abduction pillows and slings. Youth baseball guidelines further normalize prophylactic elbow bracing, extending replacement cycles.
Ankle and foot bracing is polarizing between low-cost elastic sleeves and custom ankle-foot orthoses for drop-foot. Zimmer Biomet's 2025 acquisition of Paragon 28 underlines its bet on specialty extremity growth. Lumbar-sacral orthoses face tighter CMS coverage, lengthening approval timelines. Niche hip and pelvic solutions remain tethered to post-surgery protocols and have limited uptake for osteoarthritis.
Complete Report Scope:
- By Product Type
- Knee Braces & Supports
- Ankle & Foot Braces
- Back & Spine Braces
- Upper-extremity Braces
- Hip & Pelvic Braces
- Others
- By Application
- Ligament Injury
- Preventive Care
- Post-operative Rehabilitation
- Osteoarthritis
- Other Chronic Conditions
- By End User
- Hospitals & Surgical Centers
- Orthopedic Clinics
- Homecare Settings
- Sports & Rehabilitation Centers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific is projected to post a 7.27% CAGR from 2026-2031, outpacing every other region. China cut Class II orthotic review times to nine months in 2024, aligning documentation with ISO 13485 and lowering barriers for multinationals. India's Production Linked Incentive scheme offers a 5% rebate on incremental domestic sales, encouraging global brands to set up local production lines. Japan's super-aged society drives adoption of light, low-profile devices compatible with robotic exoskeletons, reinforcing the smart-brace frontier.
North America, anchored by Medicare DMEPOS reimbursement, retained a 39.78% share in 2025 but faces future margin compression from nationwide competitive bidding starting in 2028. Europe fragments along reimbursement lines; Wales' GBP 7.6 million framework in 2024 sliced procurement costs 12% while standardizing pathways. The Middle East invests in sports clinics ahead of major events, whereas South America charts divergent paths: Brazil expands SUS reimbursement, while Argentina prioritizes locally made elastic supports amid currency curbs.
- 3M
- Alcare Co., Ltd.
- Bauerfeind
- Bird & Cronin
- Breg
- BSN Medical
- DePuy Synthes (J&J)
- DeRoyal Industries
- Dynatronics Corp.
- Enovis (DJO)
- Lohmann & Rauscher
- medi
- Ossur
- Ottobock
- Reh4Mat
- Thuasne
- Trulife
- Tynor Orthotics
- United Ortho
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Osteoarthritis & MSDs
- 4.2.2 Growing Geriatric Population
- 4.2.3 Increasing Sports-Related Injuries
- 4.2.4 Advancements in Lightweight Materials
- 4.2.5 Iot-Enabled Smart Braces Adoption
- 4.2.6 Direct-To-Consumer E-Commerce Channels
- 4.3 Market Restraints
- 4.3.1 High Cost of Sophisticated Braces
- 4.3.2 Reimbursement Hurdles for OTC Products
- 4.3.3 Proliferation of Counterfeit Products
- 4.3.4 Patient Non-Compliance Due to Discomfort
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Knee Braces & Supports
- 5.1.2 Ankle & Foot Braces
- 5.1.3 Back & Spine Braces
- 5.1.4 Upper-extremity Braces
- 5.1.5 Hip & Pelvic Braces
- 5.1.6 Others
- 5.2 By Application
- 5.2.1 Ligament Injury
- 5.2.2 Preventive Care
- 5.2.3 Post-operative Rehabilitation
- 5.2.4 Osteoarthritis
- 5.2.5 Other Chronic Conditions
- 5.3 By End User
- 5.3.1 Hospitals & Surgical Centers
- 5.3.2 Orthopedic Clinics
- 5.3.3 Homecare Settings
- 5.3.4 Sports & Rehabilitation Centers
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 3M
- 6.3.2 Alcare Co., Ltd.
- 6.3.3 Bauerfeind AG
- 6.3.4 Bird & Cronin
- 6.3.5 Breg, Inc.
- 6.3.6 BSN Medical (Essity)
- 6.3.7 DePuy Synthes (J&J)
- 6.3.8 DeRoyal Industries
- 6.3.9 Dynatronics Corp.
- 6.3.10 Enovis (DJO)
- 6.3.11 Lohmann & Rauscher
- 6.3.12 Medi GmbH & Co. KG
- 6.3.13 Ossur
- 6.3.14 Ottobock SE & Co. KGaA
- 6.3.15 Reh4Mat
- 6.3.16 Thuasne
- 6.3.17 Trulife
- 6.3.18 Tynor Orthotics
- 6.3.19 United Ortho
- 6.3.20 Zimmer Biomet
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


