

|
시장보고서
상품코드
2122263
파우치 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Pouch Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
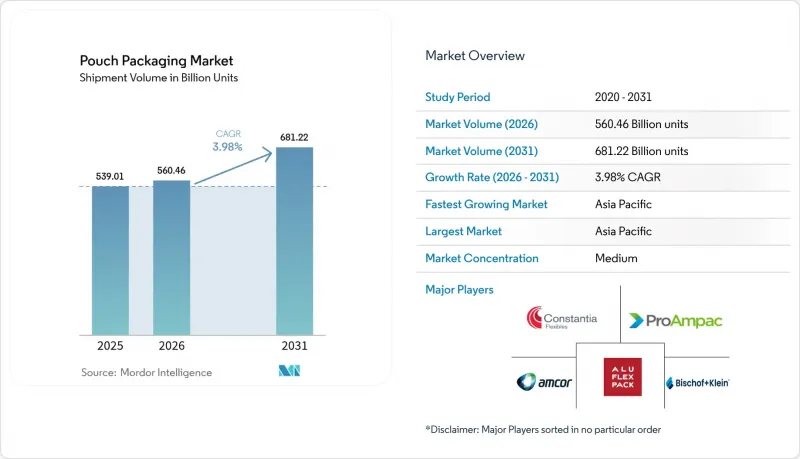
에 의하면, 파우치 포장 시장 규모는 2025년에 5,390억 1,000만 달러로 평가되었고, 2026년 5,604억 6,000만 달러에서 2031년까지 6,812억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 3.98%를 기록할 전망입니다.
본 보고서는 소재별(플라스틱, 종이, 알루미늄 포일, 생분해성/퇴비화 가능), 제품 유형별(플랫, 스탠드업, 주입구 부착, 레토르트,무균, 스틱팩/사셰, 롤스톡/기성 파우치), 마개 유형별(지퍼, 주입구/캡, 기타), 최종 사용자 산업별(식품, 음료, 의료 및 의약품, 기타), 지역별로 분류되어 있습니다. 시장 예측은 수량(개) 기준으로 제시되어 있습니다.
전 세계 파우치 포장 시장 동향 및 인사이트
비용 효율적인 포장 및 브랜드 차별화에 대한 수요 증가
소비재의 이익률에 대한 인플레이션 압력이 강해지는 가운데, 진열 매력을 해치지 않으면서도 재료 사용량을 줄일 수 있는 포장 형태에 대한 수요가 높아지고 있습니다. 파우치는 일반적으로 동등한 경질 포장에 비해 기재 사용량을 70% 절감할 수 있으며, 고해상도 그래픽을 구현할 수 있는 넓은 인쇄 면적을 갖추고 있습니다. ProAmpac의 2024년 보고서에 따르면, 가정 쓰레기로 재활용 가능한 파우치는 브랜드 소유주에게 15-20%의 원자재 비용 절감 효과를 가져다주고 있습니다. 중소 브랜드들은 이러한 경제성을 활용하여 다국적 기업과 동등한 시각적 임팩트를 실현하고 있으며, 시장의 하위 세분화를 촉진함과 동시에 가격에 민감한 카테고리에서 판매량의 추가적인 증가를 뒷받침하고 있습니다.
편의식품 및 즉석식품 소비의 급증
도시화의 진전과 가구 규모 축소에 따라, 연질 포장에 최적화된 1인분용/전자레인지용 조리 식품에 대한 의존도가 높아지고 있습니다. 미국 농무부(USDA)의 데이터에 따르면, 중국 2선 도시의 조리 식품 시장은 연평균 12%의 성장률을 보이고 있으며, 균일한 가열 및 증기 배출 기능을 갖춘 파우치가 시장 점유율을 확대되고 있습니다. ‘Once Upon a Farm’과 같은 고급 이유식 메이커들은 유통기한을 연장하고, 뛰어난 기능으로 가격 프리미엄을 정당화할 수 있는 주입구가 달린 파우치를 활용하고 있습니다.
심화되는 환경 문제 및 재활용 과제
연질 필름의 재활용 인프라는 PET 병이나 금속 캔에 비해 훨씬 뒤처져 있어, 각 브랜드는 생산자 책임 확대 제도(EPR)에 따른 비용 부담을 안고 있습니다. 연질 포장 협회에 따르면, 미국에서는 연질 필름의 고작 4%만이 기계적 재활용을 거치고 있으며, 각 컨버터 기업들은 고액의 회수 체계 비용을 부담할 수밖에 없는 상황입니다. 한편, 제안되고 있는 PFAS(퍼플루오로알킬 물질) 금지 조치는 식품 안전에 필수적인 배리어 화학 물질을 위협하고 있으며, 이러한 불확실성으로 인해 신규 생산 라인에 대한 설비 투자가 주춤하고 있습니다.
부문 분석
2025년, 파우치 포장 시장에서 플라스틱의 점유율은 60.72%를 유지했습니다. 이는 폴리에틸렌과 폴리프로필렌의 저렴한 가격과 우수한 가공성이 뒷받침하고 있습니다. 그러나 규제 당국이 폐기 후 처리 솔루션이 기존 방식의 비용 대비 성능을 능가하는 미래를 시사함에 따라, 바이오 및 퇴비화 가능한 소재는 연평균 성장률(CAGR) 6.05%로 점유율을 확대되고 있습니다. 주요 컨버터 기업들은 식물 유래 수지에 산소 차단 능력 면에서 EVOH에 필적하는 나노피브리일화 셀룰로오스를 기반으로 한 배리어 코팅을 결합하고 있습니다.
파우치 포장 시장에서는 제품의 보호 성능을 유지하면서 재활용성을 확보하는 단일 소재의 기술 혁신이 높이 평가받고 있습니다. 2024년에는 구조를 단순화한 특허 출원이 40% 증가하여, 재료 과학 부문에서의 경쟁이 치열해지고 있음을 엿볼 수 있습니다. 용해제 및 무용제 라미네이션 기술에 투자하는 각 컨버터 기업들은 2030년 기한에 앞서 EU의 재활용률 기준을 충족하는 체제를 갖추고 있습니다. 한편, 산소 투과율을 거의 제로로 억제해야 하는 고급 용도에서는 알루미늄 포일 사용량이 안정적이지만, 두께를 얇게 만들기 위한 노력은 계속되고 있습니다.
플랫형은 여전히 파우치 포장 시장 규모의 36.33%를 차지하고 있으며, 건식 식품 부문에서 확고히 자리 잡은 용도를 반영하고 있습니다. 그러나 소매업체들이 혼잡한 진열대에서 ‘수직 간판 효과’를 높이 평가함에 따라 스탠드업 파우치는 연평균 성장률(CAGR) 5.43%로 성장하고 있습니다. 각 브랜드는 스낵 견과류나 반려동물용 스낵과 같은 상품화된 카테고리에서도 거싯이 있는 바닥면이나 사진처럼 사실적인 인쇄를 활용하여 프리미엄 가치를 어필하고 있습니다.
기능 특화형 제품군도 증가하고 있습니다. 레토르트 파우치는 상온 보관이 가능한 레토르트 식품을 가능하게 하고, 무균 라미네이트는 음료 부문에서의 기회를 모색하고 있으며, 스틱 팩은 1회분용 영양보조식품 시장을 장악하고 있습니다. 롤 스톡에서 충전까지의 통합 워크플로는 대량 생산되는 SKU에서 비용 면에서의 우위를 가져다주는 반면, 기성 형태는 소량 생산에 적합합니다. 브라질에서 Gualapack이 제공하는 라미네이트, 사출 성형, 충진을 통합한 솔루션은 종단간 관리를 통해 불량률을 낮추면서 시장 출시 시간을 단축하는 좋은 사례가 되고 있습니다.
지역별 분석
아시아태평양은 2025년에 파우치 포장 시장 점유율의 39.54%를 차지하며 1위를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 6.74%를 나타낼 것으로 전망됩니다. 조직화된 소매업과 엄격한 식품 안전법의 지원에 힘입어 중국에서 가공 식품으로의 급속한 전환이 수요를 견조하게 유지하고 있습니다. 인도에서는 현대적인 소매업의 확장이 물량 증가를 주도하고 있는 반면, 한국의 K-뷰티 생태계는 유연한 화장품 포장을 전 세계로 수출하고 있습니다. 각 지역의 컨버터들은 버진 수지 공급원과의 지리적 근접성 및 비용 경쟁력이 있는 노동력이라는 이점을 누리고 있으며, 다국적 브랜드 소유주들이 포장 사양의 세계 표준화를 요구하는 상황 속에서도 지역 밀착형 공급망을 강화하고 있습니다.
북미에서는 프리미엄화와 전자상거래 대응에 중점을 둔 성숙한 수요 동향이 나타나고 있습니다. 경량 설계는 부피 중량 과금제 하에서 운송 비용 절감으로 이어져, 소매업체들이 자사 브랜드 파우치를 채택하는 움직임을 뒷받침하고 있습니다. 유럽에서는 재활용 가능성을 위한 규제 움직임이 단일 소재 제품의 도입을 가속화하고 있으며, 수명 주기 지표에서 연질 포장이 경질 유리나 다층 판지보다 더 높은 위치를 차지하고 있습니다. 스칸디나비아 시장에서는 연질 필름용 보증금 제도가 시범적으로 도입되어, EU 전체 도입을 위한 데이터가 제공되고 있습니다.
남미, 중동 및 아프리카는 전반적으로 신흥 시장으로서 성장 잠재력을 지니고 있습니다. 브라질 유제품 산업에서는 콜드체인의 에너지 절약 효과를 이유로 요거트 음료용 주입구가 달린 파우치를 채택하고 있습니다. 걸프협력회의(GCC) 회원국에서는 사막 지대의 물류 환경을 견딜 수 있는 파우치 포장 레토르트 식품이 수입되고 있으며, 아프리카의 메가시티에서는 합리적인 가격의 일용품으로 소형 파우치 형태가 이용되고 있습니다. 인프라 측면의 과제는 여전히 남아 있지만, 인구 동향의 호조와 가처분 소득 증가로 인해 선진 지역과의 격차는 점차 좁혀질 것으로 보입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트의 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the pouch packaging market size was valued at USD 539.01 billion in 2025 and estimated to grow from USD 560.46 billion in 2026 to reach USD 681.22 billion by 2031, at a CAGR of 3.98% during the forecast period (2026-2031).
This report is Segmented by Material (Plastics, Paper, Aluminum Foil, Bio-degradable/Compostable), Product Type (Flat, Stand-Up, Spouted, Retort, Aseptic, Stick-Pack/Sachet, Rollstock/Premade Pouch), Closure Type (Zipper, Spout and Cap, and More), End-User Industry (Food, Beverage, Medical and Pharmaceutical, and More), and Geography. The Market Forecasts are Provided in Terms of Volume (Units).
Global Pouch Packaging Market Trends and Insights
Rising Demand for Cost-Effective Packaging and Brand Differentiation
Inflationary pressure on consumer goods margins intensifies the search for packaging formats that cut material usage without compromising shelf appeal. Pouches typically use 70% less substrate than comparable rigid packs and provide a larger printable surface that supports high-resolution graphics. ProAmpac's 2024 report shows curbside-recyclable pouches delivering 15-20% material cost savings for brand owners. Smaller brands leverage these economics to match the visual impact of multinationals, fostering market fragmentation and stimulating additional unit volumes across price-sensitive categories.
Surge in Convenience and Ready-to-Eat Food Consumption
Rising urbanization and smaller household sizes translate into greater reliance on single-serve, microwave-ready meals best suited to flexible formats. USDA data indicates 12% annual growth in ready meals across China's tier-2 cities, with pouches gaining share due to uniform heating and steam venting capabilities. Premium baby-food players such as Once Upon a Farm capitalize on spouted pouches that extend shelf life and justify price premiums through superior functionality.
Escalating Environmental and Recycling Challenges
Flexible-film recycling infrastructure lags far behind that of PET bottles or metal cans, exposing brands to Extended Producer Responsibility fees. The Flexible Packaging Association notes only 4% of flexible films are mechanically recycled in the United States, leaving converters to fund costly take-back schemes. Meanwhile, proposed PFAS bans threaten barrier chemistries vital for food safety, creating uncertainty that slows capital spending on new lines.
Other drivers and restraints analyzed in the detailed report include:
- Sustainability-Driven Shift Toward Lightweight Flexible Packs
- Acceleration of E-Commerce and Direct-to-Consumer Logistics
- Volatility in Plastic-Resin Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics retained a 60.72% pouch packaging market share in 2025, anchored by the affordability and processability of polyethylene and polypropylene. Yet bio-based and compostable materials are gaining a 6.05% CAGR foothold as regulators signal a future where end-of-life solutions trump historic cost-performance ratios. Leading converters integrate plant-derived resins with barrier coatings based on nanofibrillated cellulose that rival EVOH in oxygen-blocking capacity.
The pouch packaging market rewards mono-material breakthroughs that ensure recyclability while maintaining product protection. Patent filings for simplified structures rose 40% in 2024, demonstrating a material-science arms race. Converters investing in compatibilizers and solvent-free lamination position themselves to meet EU recyclability quotas ahead of the 2030 deadline. Meanwhile, aluminum foil usage holds steady in premium applications that demand near-zero oxygen ingress, though downgauging efforts continue.
Flat formats still constitute 36.33% of the pouch packaging market size, reflecting entrenched applications in dry goods. Stand-up pouches, however, outpace at a 5.43% CAGR as retailers reward the vertical billboard effect on crowded shelves. Brands exploit gusseted bases and photo-realistic printing to signal premium value, even in commoditized categories such as snack nuts or pet treats.
Function-specific variants proliferate. Retort pouches enable shelf-stable ready meals, aseptic laminates chase beverage opportunities, and stick packs dominate single-serve nutraceuticals. Integrated rollstock-to-fill workflows deliver cost advantages for high-volume SKUs, whereas premade formats suit small batch runs. Gualapack's integrated laminate, injection, and filling solution in Brazil exemplifies how end-to-end control lowers failure rates while accelerating time to market.
Complete Report Scope:
- By Material
- Plastics
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polyvinyl Chloride resin (PVC)
- Other Plastics
- Paper
- Aluminum Foil
- Bio-degradable/Compostable
- Plastics
- By Product Type
- Flat (Pillow and Side-Seal)
- Stand-Up
- Spouted
- Retort
- Aseptic
- Stick-Pack / Sachet
- Rollstock / Premade Pouch
- By Closure Type
- Zipper
- Spout and Cap
- Tear-Notch
- Slider
- Other Closure Type
- By End-User Industry
- Food
- Candy and Confectionery
- Frozen Foods
- Fresh Produce
- Dairy Products
- Dry Foods and Cereals
- Meat, Poultry and Seafood
- Pet Food
- Other Foods (Sauces, Condiments, Spreads)
- Beverage
- Alcoholic
- Non-Alcoholic
- Medical and Pharmaceutical
- Personal Care and Cosmetics
- Home Care and Household
- Other End-User Industry
- Food
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific led with 39.54% of the pouch packaging market share in 2025 and is forecast to record a 6.74% CAGR to 2031. China's rapid shift toward packaged foods, propelled by organized retail and stringent food-safety laws, keeps demand buoyant. India's modern trade expansion drives volume gains, while South Korea's K-Beauty ecosystem exports flexible cosmetic packs worldwide. Regional converters benefit from proximity to virgin resin suppliers and cost-competitive labor, reinforcing localized supply chains even as multinational brand owners demand global harmonization of pack specifications.
North America exhibits a mature demand profile focused on premiumization and e-commerce readiness. Lightweight designs translate into shipping cost savings under dimensional-weight tariffs, pushing retailers toward house-brand pouch adoption. Europe's regulatory drive toward recyclability accelerates mono-material rollouts, positioning flexible packs ahead of rigid glass and multilayer cartons on lifecycle metrics. Scandinavian markets pilot deposit schemes for flexible films, providing data for broader EU implementation.
South America and the Middle East, and Africa collectively offer emerging upside. Brazil's dairy sector adopts spouted pouches for yogurt drinks, citing cold-chain energy savings. Gulf Cooperation Council nations import pouch-packed ready meals that withstand desert logistics, and African megacities rely on small-sachet formats for affordable daily necessities. Infrastructure hurdles remain, yet demographic momentum and rising disposable incomes will progressively close the gap with developed regions.
- Amcor plc
- Mondi plc
- ProAmpac Intermediate, Inc.
- Constantia Flexibles Group GmbH
- Huhtamaki Oyj
- Sealed Air Corporation
- Sonoco Products Company
- Coveris Management GmbH
- Bischof + Klein SE and Co. KG
- FlexPak Services, LLC
- Goglio SpA
- Scholle IPN Corporation
- Gualapack SpA
- Aluflexpack AG
- Flair Flexible Packaging Corporation
- Hood Packaging Corporation
- Toppan Printing Co., Ltd.
- Winpak Ltd.
- Glenroy, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for cost-effective packaging and brand differentiation
- 4.2.2 Surge in convenience and ready-to-eat food consumption
- 4.2.3 Sustainability-driven shift toward lightweight flexible packs
- 4.2.4 Acceleration of e-commerce and direct-to-consumer logistics
- 4.2.5 Expansion of spouted pouches in industrial bulk applications
- 4.2.6 High-barrier mono-material film breakthroughs enabling recyclability
- 4.3 Market Restraints
- 4.3.1 Escalating environmental and recycling challenges
- 4.3.2 Volatility in plastic-resin feedstock prices
- 4.3.3 Competition from emerging fiber-based flexible formats
- 4.3.4 Supply constraints for bio-based high-barrier resins
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 The Impact of Macroeconomic Factors on the Market
- 4.9 Recycling and Sustainability Landscape
5 MARKET SIZE AND GROWTH FORECASTS(VALUE)
- 5.1 By Material
- 5.1.1 Plastics
- 5.1.1.1 Polyethylene (PE)
- 5.1.1.2 Polypropylene (PP)
- 5.1.1.3 Polyethylene Terephthalate (PET)
- 5.1.1.4 Polyvinyl Chloride resin (PVC)
- 5.1.1.5 Other Plastics
- 5.1.2 Paper
- 5.1.3 Aluminum Foil
- 5.1.4 Bio-degradable/Compostable
- 5.1.1 Plastics
- 5.2 By Product Type
- 5.2.1 Flat (Pillow and Side-Seal)
- 5.2.2 Stand-Up
- 5.2.3 Spouted
- 5.2.4 Retort
- 5.2.5 Aseptic
- 5.2.6 Stick-Pack / Sachet
- 5.2.7 Rollstock / Premade Pouch
- 5.3 By Closure Type
- 5.3.1 Zipper
- 5.3.2 Spout and Cap
- 5.3.3 Tear-Notch
- 5.3.4 Slider
- 5.3.5 Other Closure Type
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.1.1 Candy and Confectionery
- 5.4.1.2 Frozen Foods
- 5.4.1.3 Fresh Produce
- 5.4.1.4 Dairy Products
- 5.4.1.5 Dry Foods and Cereals
- 5.4.1.6 Meat, Poultry and Seafood
- 5.4.1.7 Pet Food
- 5.4.1.8 Other Foods (Sauces, Condiments, Spreads)
- 5.4.2 Beverage
- 5.4.2.1 Alcoholic
- 5.4.2.2 Non-Alcoholic
- 5.4.3 Medical and Pharmaceutical
- 5.4.4 Personal Care and Cosmetics
- 5.4.5 Home Care and Household
- 5.4.6 Other End-User Industry
- 5.4.1 Food
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Kenya
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Mondi plc
- 6.4.3 ProAmpac Intermediate, Inc.
- 6.4.4 Constantia Flexibles Group GmbH
- 6.4.5 Huhtamaki Oyj
- 6.4.6 Sealed Air Corporation
- 6.4.7 Sonoco Products Company
- 6.4.8 Coveris Management GmbH
- 6.4.9 Bischof + Klein SE and Co. KG
- 6.4.10 FlexPak Services, LLC
- 6.4.11 Goglio SpA
- 6.4.12 Scholle IPN Corporation
- 6.4.13 Gualapack SpA
- 6.4.14 Aluflexpack AG
- 6.4.15 Flair Flexible Packaging Corporation
- 6.4.16 Hood Packaging Corporation
- 6.4.17 Toppan Printing Co., Ltd.
- 6.4.18 Winpak Ltd.
- 6.4.19 Glenroy, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


