|
시장보고서
상품코드
2122267
헬스케어 포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Healthcare Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
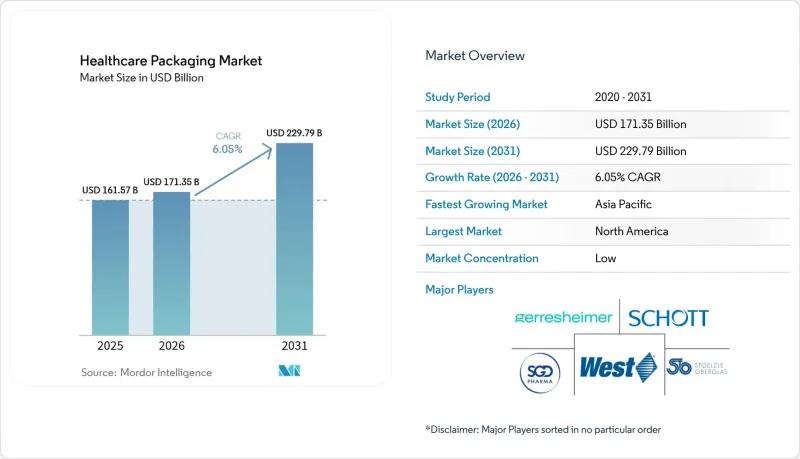
에 의하면, 헬스케어 포장 시장 규모는 2025년 1,615억 7,000만 달러로 평가되었고, 2026년에는 1,713억 5,000만 달러로 추정되고, 2026-2031년 CAGR 6.05%로 성장을 지속할 전망이며, 2031년까지 2,297억 9,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 소재별(유리, 플라스틱 등), 제품 유형별(병·용기, 바이알·앰플, 카트리지·프리필드 주사기 등), 포장 단계별(1차 포장, 2차 포장, 3차 포장), 최종 사용자별(제약 제조업체, 의료기기 OEM 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 헬스케어 포장 시장 동향 및 인사이트
셀프케어 및 가정용 진단 기기 수요 급증
당뇨병 관리 기기에 대한 의료 기술 분야의 연간 설비 투자액은 2024년에 70억 9,000만 달러에 달한 것으로 평가되었으며, 이 중 27억 달러는 소매 판매에 적합한 무균 포장이 필요한 지속 혈당 모니터에 할당될 것으로 보입니다. BD사의 ‘PIVO Pro’ 및 ‘MiniDraw’ 출시로 보아, 각 브랜드는 현재 병원 수준의 무균성을 확보하면서도 통신 판매에 적합한 크기의 변조 방지 파우치를 사양으로 채택하고 있음을 알 수 있습니다. 메드트로닉(Medtronic)사의 FDA 승인을 받은 ‘InPen-Simplera’ 스마트 MDI 시스템은 포장이 약제뿐만 아니라 내장된 전자 기기 및 관련 앱도 보호해야 한다는 점을 여실히 보여주고 있습니다. 그 결과, 헬스케어 포장 시장은 어린이가 열기 어렵지만 노인도 사용하기 쉬운 캡, 센서용 다층 캐비티, 원격 의료 워크플로우에 맞춘 QR 코드 지원 사용 설명서로 전환되고 있습니다. 재택 간호 도입이 가속화됨에 따라 헬스케어 포장 시장은 견조한 성장 궤도를 유지하고 있습니다.
일련번호 부여 및 위조 방지 관련 규제
2024년 11월 미국에서 DSCSA가 전면 시행됨에 따라, 데이터 교환 시 오류율이 최대 30%에 달하고 코드 불일치가 발생할 경우, 하루에 11만 팩이 격리 조치될 위험이 발생했습니다. 제약사들이 코딩, 집계, 검증 각 공정을 외부에 위탁함에 따라 카디널 헬스(Cardinal Health)사의 턴키형 일련번호 부여 서비스에 대한 수요가 확대되었습니다. BD사의 iDFill RFID 주사기는 1차 포장 단계에 식별자를 내장함으로써, 기업이 2차 라벨을 생략하고 라인 속도를 향상시킬 수 있음을 보여줍니다. 사람과 기계 모두에서 판독 가능한 코드를 의무화하는 유럽의 FMD 규제는 헬스케어 포장 시장이 디지털 인프라에 투자하도록 더욱 부추기고 있습니다. 일련 번호 부여의 복잡성이 증가함에 따라, 하드웨어, 소프트웨어 및 검증된 클라우드 서비스를 패키지로 제공할 수 있는 공급업체들이 시장 점유율을 확대되고 있습니다.
석유 유래 수지의 가격 변동
라이온델바셀의 휴스턴 정유시설 가동 중단과 포모사의 새로운 폴리프로필렌 공장 가동 시작으로 인해 프로파일렌 공급이 부족해졌으며, 아르고스(Argus)는 2025년에 두 자릿수 가격 상승을 예측했습니다. 2025년 3월, 엔지니어링 수지의 비용이 다시 상승하여 컨버터의 이익률을 압박했습니다. FDA가 검증한 재료 코드를 준수해야 하는 의료 브랜드는 수지를 신속하게 교체할 수 없기 때문에 소규모 컨버터들은 자금 조달에 어려움을 겪고 있습니다. 헬스케어 포장 시장에서는 대기업들이 장기 헤지 및 복수 공급업체로부터의 조달을 활용하여 가격 변동의 영향을 완화하는 한편, 차단 기능 저하를 초래할 위험 없이 두께를 얇게 할 수 있는 고차단성 모노폴리프로필렌(PP) 라미네이트 소재에 대한 평가를 진행하고 있습니다.
부문 분석
2025년에도 플라스틱은 헬스케어 포장 시장 점유율의 69.55%를 계속 차지했으며, 이는 타의 추종을 불허하는 비용 효율성과 유연한 가공 범위를 반영한 것입니다. 한편, 유리는 이온 용출이 전혀 없는 용기가 필요한 바이오의약품에 힘입어 연평균 성장률(CAGR) 9.88%로 점유율을 확대되고 있습니다. SCHOTT Pharma가 노스캐롤라이나주에 건설하는 3억 7,100만 달러 규모의 공장은 401개의 일자리를 창출하고, GLP-1 주사제용 붕규산 유리 주사기 생산 능력을 확대할 예정이며, 이는 고품질 바이알에 대한 장기적인 신뢰를 뒷받침하는 것입니다. mRNA, 유전자 편집, 세포 치료가 임상 단계를 벗어나면서 바이알, 카트리지, 주사기 등 고부가가치 유리 용기의 헬스케어 포장 시장 규모는 확대될 것입니다.
첨단 플라스틱은 흡입기, 유연한 수액백, 점안약용 스포이트 분야에서 여전히 우위를 유지하고 있지만, 특정 불소 수지 코팅에 대한 PFAS 규제로 인해 수지 배합 제조업체들은 새로운 배리어 화학 물질을 개발할 수밖에 없는 상황에 처해 있습니다. TekniPlex사의 투명하고 재활용 가능한 블리스터 라미네이트와 같은 하이브리드 솔루션은 PET와 EVOH를 결합함으로써, 기존에는 알루미늄 포일에서만 가능했던 수증기 투과율 목표를 달성하고 있습니다. EU의 재활용 가능성 관련 규제 덕분에 2차 포장 분야에서 판지가 점차 보급되고 있지만, 의약품과 직접 접촉하는 1차 포장층으로의 보급은 여전히 제한적입니다. 가압식 약물 전달 에어로졸에는 여전히 금속이 사용되고 있지만, 유럽 시장에서 추진제의 단계적 폐지에 따라 현재 초기 시험 단계에 있는 조류 유래 바이오 소재에 새로운 시장 기회가 생겨나고 있습니다. 전반적으로, 원자재의 다양화로 인해 헬스케어 포장 시장은 치료 분야에 따라 최적의 용기가 결정되는 보다 복잡한 시장 상황으로 전환되고 있습니다.
2025년 시점에서 병과 용기는 헬스케어 포장 시장에서 39.78%의 점유율을 유지한 반면, 블리스터 팩은 연평균 성장률(CAGR) 8.29%로 급성장하고 있습니다. 암콜(Amcol)의 재활용 지원 ‘AmSky’ 시스템은 PVC를 HDPE로 대체함으로써 온실가스 배출량을 70% 줄이면서도, 습기에 민감한 혈압강하제 정제에 요구되는 차단 성능을 유지하고 있습니다. NFC 태그가 탑재된 컴플라이언스용 블리스터 카드는 현재 복약 상황을 기록하고, 임상의에게 복약 준수 대시보드에 데이터를 제공합니다. 동결건조 API에는 여전히 바이알이나 앰플이 필수적이지만, 스테바나트(Stevanart)사의 ‘EZ-fill’ 플랫폼을 통해 니프로(Nipro)사는 충전 준비 완료형(D2F) 유리 바이알을 상품화할 수 있었으며, 이를 통해 전환 시간을 80% 단축했습니다.
웨어러블 주사기와 결합된 카트리지는 고점도 생물학적 제제에 대응하기 위해 8mm의 얇은 벽 두께를 가진 캐뉼라로 전환되고 있습니다. 파우치는 소비자 직접 판매용 진단 키트에서 표준으로 자리 잡았으며, 얇은 형태의 우편함 배송 방식을 가능하게 하고 있습니다. ‘기타’ 카테고리는 확대되고 있으며, 스마트팩에는 건조제 파우치에 RFID 센서가 내장되어 습도 변동이 발생할 경우 약사에게 경고를 보내도록 되어 있습니다. 결국, 헬스케어 포장 시장에서는 각 포맷의 역할이 분자의 민감도, 투여 계획, 그리고 새로운 전자상거래 주문 처리 기준에 따라 결정되는 폼 팩터의 계층 구조가 정착되고 있습니다.
지역별 분석
북미는 2025년에 헬스케어 포장 시장의 36.10%를 차지한 것으로 평가되었으며, 이는 높은 수익률을 보이는 코딩 장비의 도입을 의무화하는 FDA의 일련번호 부여 규정에 힘입은 것입니다. 공급망 혼란은 계속되고 있으며, 공급업체의 80%가 품귀 현상이 심화될 것으로 예상하고 있으며, 중규모 시스템의 경우 연간 350만 달러의 추가 비용이 발생할 것으로 전망됩니다. BD의 25억 달러 규모 국내 생산 능력 확충은 무역 혼란으로부터 헬스케어 포장 시장을 보호하려는 ‘리쇼어링’ 논리를 뒷받침하고 있습니다. 그러나 의료기기에 대한 관세가 현재 25%에 달함에 따라, 각 컨버터 기업들은 멕시코와 캐나다 양국에서 금형을 조달하도록 권장받고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 인도, 중국, 아세안(ASEAN)의 제네릭 의약품 확대와 공중 보건에 대한 자금 투자를 배경으로 연평균 성장률(CAGR) 8.94%로 성장을 지속하고, 있습니다. 암코어(Amcor)의 피닉스 플렉서블스(Phoenix Flexibles) 인수로 인해 인도 내 클린룸에서의 라미네이트 생산 능력이 두 배로 늘어나며, 공급 현지화를 위한 노력이 드러났습니다. 일본의 ‘Health 2025’ 전시회에서는 저온 검증 완료된 바이알이 필요한 재생의료용 패키징이 주목을 받았습니다. 토판(Toppan)과 DNP는 섬유 기반의 무균 팩을 전시하며, 해당 지역에서 순환형 소재로의 전환을 시사했습니다. 유럽에서는 규제 변동에도 불구하고 견조한 생산량을 유지하고 있습니다. 향후 도입될 재활용 의무화는 기존의 다층 호일에는 과제가 될 수 있지만, 바이오 배리어 층에 대한 연구 개발 자금 투자를 촉진하고 있습니다. 독일은 유리 주사기 생산량에서 압도적인 점유율을 차지하고 있지만, 생산 능력의 제약으로 인해 스페인 및 체코 공화국에 대한 투자가 촉진되고 있습니다. 중동 및 아프리카에서는 사우디아라비아와 이집트에서 제네릭 의약품의 주요 제조 거점이 지속적으로 확대되면서 GMP 등급 필름에 대한 새로운 수요가 발생하고 있습니다. 남미에서는 한 자릿수 중반대의 성장률을 기록하고 있으며, 브라질의 ANVISA는 전자 리플릿을 도입하고 상자 크기를 축소하여 물류 비용을 절감하고 있습니다. 이러한 동향들이 맞물리면서 모든 대륙에서 헬스케어 포장 시장 규모가 확대되는 동시에, 다국적 컨버터의 위험 포트폴리오 다각화도 진행되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the healthcare packaging market size is expected to grow from USD 161.57 billion in 2025 to USD 171.35 billion in 2026 and is forecast to reach USD 229.79 billion by 2031 at 6.05% CAGR over 2026-2031.
This report is Segmented by Material (Glass, Plastics, and More), Product Type (Bottles and Containers, Vials and Ampoules, Cartridges and Pre-Filled Syringes, and More), Packaging Level (Primary, Secondary, Tertiary), End-User (Pharmaceutical Manufacturing, Medical-Device OEMs, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Healthcare Packaging Market Trends and Insights
Demand Surge in Self-Care and Home-Diagnostic Devices
Annual med-tech capital spending on diabetes care devices hit USD 7.09 billion in 2024, with USD 2.7 billion earmarked for continuous glucose monitors that require retail-ready sterile packaging. BD's PIVO Pro and MiniDraw launches show how brands now spec tamper-proof pouches sized for mail-order fulfillment while ensuring hospital-grade sterility. Medtronic's FDA-cleared InPen-Simplera Smart MDI system underscores that packaging must protect not only the drug but also the embedded electronics and companion apps. The healthcare packaging market, therefore, pivots toward child-resistant yet senior-friendly closures, multi-layer cavities for sensors, and QR-enabled instructions that match telehealth workflows. Intensified home-care adoption keeps the healthcare packaging market on a robust growth arc.
Serialization and Anti-Counterfeit Mandates
Full enforcement of the U.S. DSCSA in November 2024 triggered up to 30% error rates in data exchanges, risking daily quarantines of 110,000 packs when codes mis-match.Cardinal Health's turnkey serialization service pipeline grew as drug makers outsourced coding, aggregation, and validation steps. BD's iDFill RFID syringe shows that embedding identifiers at the primary level lets companies dispense with secondary labels and accelerate line speeds. European FMD rules requiring dual human- and machine-readable codes further push the healthcare packaging market toward digital infrastructure investment. Suppliers able to bundle hardware, software, and validated cloud services gain share as serialization complexity mounts.
Petro-based Resin Price Volatility
The shutdown of LyondellBasell's Houston refinery and the commissioning of Formosa's new polypropylene plant tightened propylene supply, with Argus expecting double-digit price hikes in 2025. Engineering-resin costs climbed again in March 2025, eroding converter margins. Healthcare brands tied to FDA-validated material codes cannot switch resins quickly, so smaller converters face liquidity crunches. The healthcare packaging market sees larger players using long-term hedging and multi-sourcing to blunt volatility, while they evaluate higher-barrier mono-PP laminates that permit down-gauging without risking barrier failure.
Other drivers and restraints analyzed in the detailed report include:
- Aging Population and Chronic-Disease Prevalence
- Sustainability-Driven Material Substitution
- Complex Multi-Jurisdictional Waste-Disposal Rules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics continued to account for 69.55% of healthcare packaging market share in 2025, reflecting unmatched cost efficiency and flexible processing windows. Conversely, glass is advancing at a 9.88% CAGR, buoyed by biologics that require zero-ion-leach containers. SCHOTT Pharma's USD 371 million North Carolina plant will add 401 jobs and expand borosilicate syringe capacity for GLP-1 injectables, evidencing long-term confidence in premium vials. The healthcare packaging market size for high-value glass formats-vials, cartridges, syringes-will expand as mRNA, gene-editing, and cell therapies exit the clinic.
Advanced plastics retain dominance in inhalers, flexible IV bags, and ophthalmic droppers, but PFAS restrictions on certain fluoropolymer coatings force resin formulators to develop new barrier chemistries. Hybrid solutions, such as TekniPlex's clear recyclable blister laminate, combine PET with EVOH to reach moisture-vapour-transmission targets traditionally reserved for foil. Paperboard is making headway in secondary wraps thanks to EU recyclability mandates, yet its penetration into primary drug contact layers remains limited. Metals continue to serve pressurized drug delivery aerosols, but propellant phase-out in European markets is opening white-space for algae-based biomaterials now in early testing. Collectively, raw-material diversification positions the healthcare packaging market for a nuanced landscape where therapeutic class determines container of choice.
Bottles and containers retained a 39.78% slice of the healthcare packaging market in 2025, but blister packs are sprinting ahead with an 8.29% CAGR. Amcor's recycle-ready AmSky system substitutes PVC with HDPE, reducing greenhouse-gas emissions by 70% yet keeping the barrier specs demanded for moisture-sensitive antihypertensive tablets. Compliance blister cards featuring NFC tags now capture ingestion events, feeding adherence dashboards for clinicians. Vials and ampoules remain compulsory for lyophilized APIs, although Stevanato's EZ-fill platform allowed Nipro to commercialize D2F ready-to-fill glass vials that cut change-over time by 80%.
Cartridges paired with wearable injectors are pivoting toward 8-mm thin-wall cannulas to handle high-viscosity biologics. Pouches have become the go-to for direct-to-consumer diagnostics kits, enabling low-profile letter-box shipping formats. The "other" category is swelling as smart packs embed desiccant pouches with RFID sensors that alert pharmacists when humidity excursions occur. Ultimately, the healthcare packaging market embraces a form-factor hierarchy where each format's role is dictated by molecule sensitivity, dosage regimen, and emerging e-commerce fulfilment norms.
Complete Report Scope:
- By Material
- Glass
- Plastics
- Paper and Paperboard
- Metals and Foils
- By Product Type
- Bottles and Containers
- Vials and Ampoules
- Cartridges and Pre-filled Syringes
- Blister Packs
- Pouches and Bags
- Other ProductType
- By Packaging Level
- Primary Packaging
- Secondary Packaging
- Tertiary Packaging
- By End-user
- Pharmaceutical Manufacturing
- Medical-Device OEMs
- Nutraceuticals and OTC
- Home-Healthcare Providers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America controlled 36.10% of healthcare packaging market share in 2025, supported by FDA serialization rules that compel high-margin coding equipment. Supply-chain turbulence persists; 80% of providers expect shortages to intensify, adding up to USD 3.5 million in annual costs for medium-sized systems. BD's USD 2.5 billion domestic capacity build underscores a reshoring logic that protects the healthcare packaging market from trade disruptions. However, tariffs on medical devices now reaching 25% incentivize converters to dual-source tooling from Mexico and Canada.
Asia-Pacific is the fastest-growing region, charting a 8.94% CAGR on the back of generics expansion and public-health funding in India, China, and ASEAN. Amcor's acquisition of Phoenix Flexibles doubled its cleanroom lamination capacity in India, demonstrating commitment to localize supply. Japan's Health 2025 expo spotlighted regenerative-medicine packaging that demands cryo-validated vials. TOPPAN and DNP showcased fiber-based sterile packs, signaling a regional tilt toward circular materials. Europe maintains strong throughput despite regulatory churn. The upcoming recyclability mandate challenges legacy multilayer foils, yet drives R&D funding for bio-based barrier layers. Germany captures disproportionate share of glass syringe output, but capacity constraints spur investments in Spain and the Czech Republic. Middle East & Africa continue to expand basic generic drug plants in Saudi Arabia and Egypt, opening greenfield demand for GMP-grade films. South America posts mid-single-digit growth; Brazil's ANVISA introduced e-leaflets that lower carton size, trimming logistics costs. Collectively these dynamics widen the healthcare packaging market size across every continent while diversifying the risk portfolio for multinational converters.
- Amcor plc
- Gerresheimer AG
- SCHOTT AG
- Corning Incorporated
- West Pharmaceutical Services
- AptarGroup Inc.
- Becton Dickinson & Co.
- SGD Pharma
- Nipro Corporation
- Piramal Glass
- Oliver Healthcare Packaging
- Smurfit WestRock
- Sealed Air Corp.
- Sonoco Products Co.
- Catalent Inc.
- Beatson Clark PLC
- Shandong Medicinal Glass
- Sisecam Group
- Arab Pharmaceutical Glass Co.
- Stolzle-Oberglas GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand surge in self-care and home-diagnostic devices
- 4.2.2 Serialization and anti-counterfeit mandates
- 4.2.3 Aging population and chronic-disease prevalence
- 4.2.4 Sustainability-driven material substitution
- 4.2.5 Cryogenic packaging for cell and gene therapies
- 4.2.6 Smart packs with RFID / NFC for adherence tracking
- 4.3 Market Restraints
- 4.3.1 Petro-based resin price volatility
- 4.3.2 Complex multi-jurisdictional waste-disposal rules
- 4.3.3 Medical-grade glass capacity bottlenecks
- 4.3.4 Cyber-security risks in connected packaging
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Glass
- 5.1.2 Plastics
- 5.1.3 Paper and Paperboard
- 5.1.4 Metals and Foils
- 5.2 By Product Type
- 5.2.1 Bottles and Containers
- 5.2.2 Vials and Ampoules
- 5.2.3 Cartridges and Pre-filled Syringes
- 5.2.4 Blister Packs
- 5.2.5 Pouches and Bags
- 5.2.6 Other ProductType
- 5.3 By Packaging Level
- 5.3.1 Primary Packaging
- 5.3.2 Secondary Packaging
- 5.3.3 Tertiary Packaging
- 5.4 By End-user
- 5.4.1 Pharmaceutical Manufacturing
- 5.4.2 Medical-Device OEMs
- 5.4.3 Nutraceuticals and OTC
- 5.4.4 Home-Healthcare Providers
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia and New Zealand
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 United Arab Emirates
- 5.5.4.1.2 Saudi Arabia
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Nigeria
- 5.5.4.2.3 Egypt
- 5.5.4.2.4 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Gerresheimer AG
- 6.4.3 SCHOTT AG
- 6.4.4 Corning Incorporated
- 6.4.5 West Pharmaceutical Services
- 6.4.6 AptarGroup Inc.
- 6.4.7 Becton Dickinson & Co.
- 6.4.8 SGD Pharma
- 6.4.9 Nipro Corporation
- 6.4.10 Piramal Glass
- 6.4.11 Oliver Healthcare Packaging
- 6.4.12 Smurfit WestRock
- 6.4.13 Sealed Air Corp.
- 6.4.14 Sonoco Products Co.
- 6.4.15 Catalent Inc.
- 6.4.16 Beatson Clark PLC
- 6.4.17 Shandong Medicinal Glass
- 6.4.18 Sisecam Group
- 6.4.19 Arab Pharmaceutical Glass Co.
- 6.4.20 Stolzle-Oberglas GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment