|
시장보고서
상품코드
2122291
신경망 소프트웨어 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Neural Network Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
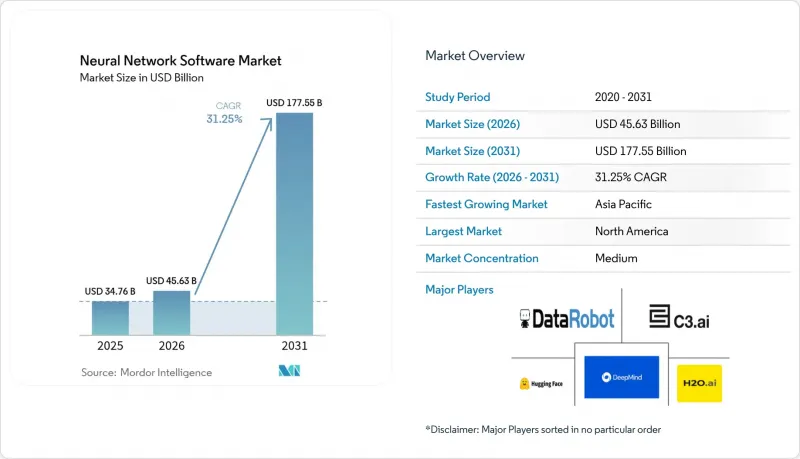
에 의하면, 2026년 신경망 소프트웨어 시장 규모는 456억 3,000만 달러로 추정되고, 2025년 347억 6,000만 달러에서 확대해, 2031년에는 1,775억 5,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 31.25%를 나타낼 전망입니다.
본 보고서는 구성 요소별(소프트웨어 도구, 플랫폼, 서비스), 도입 형태별(클라우드, 온프레미스, 하이브리드), 유형별(데이터 마이닝 및 아카이빙, 분석 소프트웨어 등), 용도별(부정 감지, 하드웨어 진단, 재무 예측 등), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 헬스케어 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 신경망 소프트웨어 시장 동향 및 인사이트
클라우드 기반 AI 플랫폼이 접근성 민주화를 촉진
중견 기업들이 자본 측면의 장벽을 해소하는 매니지드 플랫폼을 채택함에 따라, 2025년에는 기업의 생성형 AI 지출이 30% 증가할 전망입니다. 레드햇의 뉴럴 매직 인수로 인해, 해당 기업의 하이브리드 클라우드 제품군에 최적화된 추론 라이브러리가 추가되어 프라이빗 클러스터 내에서 효율적인 도입이 가능해졌습니다. Rackspace의 ‘AI Anywhere’ 서비스는 미리 구축된 모델을 예측 가능한 구독 요금과 함께 제공하여, 사내에 전문 지식이 없는 기업도 복잡한 신경망 아키텍처를 활용할 수 있게 해줍니다. 구글의 ‘Gemini’ 제품군은 텍스트에서 이미지나 동영상을 생성하는 API를 표준 클라우드 콘솔에 통합함으로써 보급을 더욱 확대하고 있으며, 개발자가 전용 인프라를 마련하지 않고도 멀티모달 추론을 테스트할 수 있게 하고 있습니다. 이러한 플랫폼의 동향으로 인해 가치 실현까지 걸리는 시간이 단축되었으며, 신경망 소프트웨어 시장이 새로운 기업 사용자층으로 확대되고 있습니다.
예측 분석에 대한 기업 수요 증가
신경망을 활용한 고장 예측 정확도가 94%에 달함에 따라, 제조업체들은 사후 대응형 유지보수에서 예방적 유지보수로 전환하고 있습니다. BMW의 레겐스부르크 공장에서는 기존 부품 데이터를 분석하여 연간 500분 이상의 조립 라인 정지를 미연에 방지하고 있으며, 산업 분야에서 높은 ROI를 입증하고 있습니다. 제너럴 모터스(GM)는 IoT 센서와 AI 기반 스케줄링 엔진을 연동한 결과, 예기치 못한 가동 중단 시간을 15% 줄이고 연간 2,000만 달러의 비용 절감을 실현했습니다. 금융 기관에서도 유사한 이점을 확인할 수 있으며, 하이브리드 딥러닝 모델을 통해 부정 결제의 98.7%를 감지하고 있습니다. 이러한 명확한 경제적 이익으로 인해 소프트웨어 조달 주기가 가속화되고 있으며, 벤더의 신속한 도입 지원에 대한 기대가 높아지고 있습니다.
딥러닝·MLOps 인재 부족
AI를 도입한 기업 중 전담 MLOps 엔지니어를 고용하고 있는 곳은 고작 28%에 불과하며, 2024년에는 유럽 고용주의 75%가 AI 관련 직종 채용에 어려움을 겪고 있어 뿌리 깊은 기술 격차가 부각되고 있습니다. 현재 주요 기술 기업들은 재교육 속도를 높이기 위해 인증 교육 과정을 제공하고 있지만, 교육 과정은 급속한 프레임워크 변화에 따라가지 못하고 있습니다. 모델을 운영에 적용할 수 있는 충분한 실무 인력이 부족하여 도입까지의 기간이 길어지고 있으며, 서비스 수익이 증가하고 수요가 확대되고 있음에도 불구하고 신경망 소프트웨어 시장의 단기적 성장에는 한계가 나타나고 있습니다.
부문 분석
소프트웨어 프레임워크, 라이브러리 및 AutoML 제품군은 2025년 매출의 53.85%를 차지했으며, 신경망 소프트웨어 시장의 구조적 핵심으로서의 역할을 강조하고 있습니다. TensorFlow, PyTorch, JAX와 같은 주요 개발 키트는 여전히 필수적이지만, 구매자들 사이에서는 실험 주기를 단축하는 턴키형 모듈에 대한 수요가 증가하고 있습니다. 기업들이 통합, 튜닝, 라이프사이클 관리를 외부에 위탁함에 따라, 전문 컨설팅 및 관리형 운영을 포함한 서비스는 연평균 성장률(CAGR) 34.15%로 확대되고 있습니다.
클라우드 제공업체들이 실제 가동까지의 시간을 단축하기 위해 구독 패키지에 AI 전문가를 포함시킨 결과, 2025년에는 관리형 서비스가 신경망 소프트웨어 시장 규모의 34.2%에 해당하는 증가분을 차지했습니다. 전문 서비스 팀은 의료 영상의 규정 준수 등 산업별 고유한 요구 사항을 충족시키고 있으며, 이로 인해 서비스 점유율은 더욱 확대되고 있습니다. 예측 기간 동안 벤더 간의 차별화는 단순한 라이선싱이 아닌, 해당 분야의 전문성과 성과 기반 가격 책정에 달려 있을 것입니다.
2025년, 퍼블릭 클라우드는 신경망 소프트웨어 시장 점유율의 60.65%를 유지했습니다. 이는 하이퍼스케일러가 훈련 및 추론을 위한 탄력적인 컴퓨팅을 제공하고 있기 때문입니다. 기업들은 온디맨드 방식으로 GPU 클러스터를 활용하여 초기 자본 지출을 피하고 있습니다. 그러나 데이터 주권, 지연 시간, 규제 요건과 같은 요인으로 인해 성장은 하이브리드 배포로 전환되고 있으며, 2031년까지 연평균 성장률(CAGR)은 33.6%로 예측됩니다.
하이브리드 아키텍처에서는 모델 훈련을 확장 가능한 퍼블릭 환경에서 수행하는 한편, 데이터는 온프레미스 또는 프라이빗 클라우드에 보관됩니다. 금융 서비스 및 의료 사업자들은 기밀 데이터를 보호하면서 클라우드의 확장성을 활용하기 위해 이러한 토폴로지를 채택하고 있습니다. 기밀 컴퓨팅 및 페더레이티드 러닝의 활용 확대는 하이브리드에 대한 수요를 더욱 높일 것이며, 벤더의 자원 계획에 새로운 변화를 가져올 것입니다.
지역별 분석
북미는 확립된 벤처 캐피털 생태계, 선진적인 클라우드 인프라, 그리고 풍부한 인재 풀을 배경으로 2025년에는 매출의 37.65%를 차지했습니다. OpenAI가 연간 경상 수익을 2배인 100억 달러로 확대한 것은 상업적 성숙도를 여실히 보여주고 있으며, 한편 하이퍼스케일러 기업들은 매니지드 AI 포트폴리오를 지속적으로 확충하고 있습니다. 캐나다는 몬트리올과 토론토의 학술 클러스터를 활용하고 있지만, 반도체 제조에 있어 아시아에 대한 의존도가 자국 주도 컴퓨팅 분야의 야망을 제한하고 있습니다. 멕시코는 니어쇼어링을 활용하고, 물류 및 자동차 생산에 신경망 솔루션을 통합함으로써 지역 공급망을 강화하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 34.6%를 나타낼 것으로 예측되며, 중국, 일본, 인도, 한국이 국가 AI 클라우드를 도입함에 따라 신경망 소프트웨어 시장 규모는 2031년까지 724억 달러로 급증할 것으로 전망됩니다. 중국은 44개 주요 연구개발 분야 중 37개 분야에서 선도적 위치를 차지하고 있으며, 산업용 AI 업그레이드를 위해 국가 자금을 투입하고 있습니다. 일본은 OpenAI의 첫 인도-태평양 지역 사무소를 개설했으며, 이는 언어의 미묘한 뉘앙스와 데이터 소재지 관련 법규를 존중하는 기업용 GPT 솔루션에 대한 현지 수요가 뒷받침되고 있음을 보여줍니다. 인도는 정부 주도의 샌드박스를 통해 스타트업을 육성하고 있는 반면, 호주와 싱가포르는 안전성과 거버넌스에 관한 연구에 투자하고 있어 지역 전체에 걸쳐 다양한 기회가 창출되고 있습니다.
유럽은 주권 AI 프로젝트를 통해 기술적 자립을 추구하고 있습니다. NVIDIA는 유럽의 데이터센터 파트너에게 3,000 엑사플롭스를 초과하는 Blackwell 클러스터를 공급하며, 규제 대상 AI 워크로드를 뒷받침하는 대륙 규모의 기반을 형성하고 있습니다. 독일의 산업용 AI 클라우드와 프랑스의 통신 사업자 주도 모델 호스팅 허브가 이러한 움직임에 더욱 깊이를 더하고 있습니다. 그러나 인력 부족은 여전히 지속되고 있으며, 고용주의 75%가 AI 관련 직책에 인력을 확보하지 못하고 있어, 이는 임금 상승과 국경을 넘는 인력 이동을 초래하고 있습니다. 엄격한 GDPR(EU 개인정보보호규정) 및 향후 시행될 AI 법의 요건으로 인해 거버넌스 도구를 제공하는 벤더들이 유리한 입지를 차지하며 조달 우선순위를 형성하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 동향
AJY 26.09.07According to Mordor Intelligence, neural network software market size in 2026 is estimated at USD 45.63 billion, growing from 2025 value of USD 34.76 billion with 2031 projections showing USD 177.55 billion, growing at 31.25% CAGR over 2026-2031.
This report is Segmented by Component (Software Tools, Platform, and Services), Deployment Mode (Cloud, On-Premise, and Hybrid), Type (Data Mining and Archiving, Analytical Software, and More), Application (Fraud Detection, Hardware Diagnostics, Financial Forecasting, and More), End-User Vertical (BFSI, Healthcare, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Neural Network Software Market Trends and Insights
Cloud-based AI Platforms Democratize Access
Enterprise generative-AI spending is rising 30% in 2025 as mid-market firms adopt managed platforms that remove capital barriers. Red Hat's purchase of Neural Magic adds optimized inference libraries to its hybrid cloud suite, enabling efficient deployments within private clusters. Rackspace's AI Anywhere service packages pre-built models with predictable subscription pricing, making complex neural network architectures attainable for firms lacking in-house expertise. Google's Gemini family extends democratization by embedding text-to-image and video generation APIs inside standard cloud consoles, letting developers test multimodal inference without bespoke infrastructure. These platform moves reduce time-to-value and expand the neural network software market across new corporate adopters.
Rising Enterprise Demand for Predictive Analytics
Manufacturers are shifting from reactive to proactive maintenance as neural networks reach 94% accuracy in fault prediction. BMW's Regensburg plant prevents over 500 minutes of annual assembly disruption by analyzing existing component data, confirming strong ROI in industrial contexts. General Motors cut unexpected downtime by 15% and saved USD 20 million yearly after linking IoT sensors with AI-driven scheduling engines. Financial institutions see parallel benefits, with hybrid deep-learning models catching 98.7% of fraudulent payments. Such clear economic gains accelerate software procurement cycles and raise expectations for rapid deployment support from vendors.
Shortage of Deep-Learning MLOps Talent
Only 28% of AI adopters employ dedicated MLOps engineers, and 75% of European employers struggled to fill AI roles in 2024, spotlighting a persistent skills gap. Tech giants now deliver certification curricula to accelerate reskilling, yet curricula cannot match rapid framework changes. Without sufficient practitioners to operationalize models, deployment timelines lengthen and service revenues climb, capping short-term neural network software market gains even as demand grows.
Other drivers and restraints analyzed in the detailed report include:
- Growing Availability of Big Data and GPUs
- Foundation Models Create New Toolchain Demand
- Data-Privacy and Governance Burdens
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software frameworks, libraries, and AutoML suites delivered 53.85% of 2025 revenue, underscoring their role as the structural backbone of the neural network software market. Core development kits such as TensorFlow, PyTorch, and JAX remain essential, yet buyers increasingly demand turnkey modules that shorten experimentation cycles. Services, including professional consulting and managed operations, are rising at 34.15% CAGR as firms outsource integration, tuning, and lifecycle management.
Managed services captured incremental gains equal to 34.2% of the neural network software market size in 2025 as cloud providers embedded AI specialists within subscription packages to accelerate time-to-production. Professional service teams respond to sector-specific needs-e.g., healthcare imaging compliance-further boosting service share. Over the forecast window, vendor differentiation will hinge on domain depth and outcome-based pricing rather than licensing alone.
Public cloud retained 60.65% of the neural network software market share in 2025 because hyperscalers offer elastic compute for training and inference. Enterprises leverage GPU clusters on demand, avoiding up-front capital outlays. Yet sovereignty, latency, and regulatory requirements are shifting growth toward hybrid deployments, forecast at 33.6% CAGR to 2031.
Hybrid architectures let data reside on-premise or in private clouds while model training happens in scalable public environments. Financial services and healthcare operators adopt this topology to protect sensitive data while exploiting cloud scale. The growing use of confidential computing and federated learning will amplify hybrid demand, reshaping resource planning for vendors.
Complete Report Scope:
- By Component
- Software Tools
- Frameworks and Libraries
- AutoML Platforms
- Platform (PaaS)
- Services
- Managed Services
- Professional Services
- Software Tools
- By Deployment Mode
- Cloud
- On-premise
- Hybrid
- By Type
- Data Mining and Archiving
- Analytical Software
- Optimization Software
- Visualization Software
- By Application
- Fraud Detection
- Hardware Diagnostics
- Financial Forecasting
- Image Optimization
- Predictive Maintenance
- Natural Language Processing
- Speech Recognition
- Others
- By End-user Vertical
- BFSI
- Healthcare
- Retail and E-Commerce
- Defense and Government
- Media and Entertainment
- Logistics and Transportation
- Energy and Utilities
- Manufacturing
- Other End-user Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Singapore
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 37.65% revenue in 2025 due to an established venture-capital ecosystem, advanced cloud infrastructure, and dense talent pools. OpenAI doubling annual recurring revenue to USD 10 billion highlights commercial maturity, while hyperscalers continually widen managed-AI portfolios. Canada leverages academic clusters in Montreal and Toronto, yet chip fabrication dependence on Asia limits sovereign compute ambitions. Mexico leverages nearshoring to integrate neural network solutions in logistics and automotive production, strengthening regional supply chains.
Asia-Pacific is forecast to grow at 34.6% CAGR, with the neural network software market size jumping to USD 72.4 billion by 2031 as China, Japan, India, and South Korea implement national AI clouds. China leads 37 of 44 critical R&D disciplines, channelling state financing toward industrial AI upgrades. Japan hosts OpenAI's first Indo-Pacific office, confirming local demand for enterprise GPT solutions that respect linguistic nuance and data-residency laws. India nurtures start-ups through government sandboxes, while Australia and Singapore invest in safety and governance research, creating diversified regional opportunities.
Europe pursues technological autonomy through sovereign-AI projects. NVIDIA is supplying over 3,000 exaflops of Blackwell clusters to European data-center partners, forming a continental spine for regulated AI workloads. Germany's industrial AI cloud and France's telco-led model-hosting hubs add depth. However, talent shortages persist, with 75% of employers unable to staff AI roles, driving wage inflation and cross-border migration. Strict GDPR and forthcoming AI-Act requirements favor vendors offering governance tooling, shaping procurement priorities.
- DataRobot Inc.
- H2O.ai Inc.
- C3.ai Inc.
- Hugging Face Inc.
- DeepMind Technologies Ltd.
- OpenAI Inc.
- Clarifai Inc.
- GMDH LLC
- Neural Designer (Artelnics S.L.)
- Alyuda Research LLC
- Neural Technologies Ltd.
- Neuralware LLC
- AND Corporation
- Abacus.ai
- OctoML Inc.
- Databricks Inc.
- Seldon Technologies Ltd.
- Weights and Biases Inc.
- Comet ML Inc.
- Run:AI Labs Ltd.
- Lightning AI Inc.
- KNIME AG
- RapidMiner Inc.
- LatticeFlow AG
- Pachyderm Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-based AI platforms democratize neural networks
- 4.2.2 Rising enterprise demand for predictive analytics
- 4.2.3 Growing availability of big-data and GPUs
- 4.2.4 Foundation models create new toolchain demand
- 4.2.5 Open-source model marketplaces accelerate adoption
- 4.2.6 Sovereign-AI initiatives need local NN stacks
- 4.3 Market Restraints
- 4.3.1 Shortage of deep-learning MLOps talent
- 4.3.2 Data-privacy and governance burdens
- 4.3.3 GPU supply-chain volatility inflates costs
- 4.3.4 Energy and ESG scrutiny of training workloads
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Component
- 5.1.1 Software Tools
- 5.1.1.1 Frameworks and Libraries
- 5.1.1.2 AutoML Platforms
- 5.1.2 Platform (PaaS)
- 5.1.3 Services
- 5.1.3.1 Managed Services
- 5.1.3.2 Professional Services
- 5.1.1 Software Tools
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-premise
- 5.2.3 Hybrid
- 5.3 By Type
- 5.3.1 Data Mining and Archiving
- 5.3.2 Analytical Software
- 5.3.3 Optimization Software
- 5.3.4 Visualization Software
- 5.4 By Application
- 5.4.1 Fraud Detection
- 5.4.2 Hardware Diagnostics
- 5.4.3 Financial Forecasting
- 5.4.4 Image Optimization
- 5.4.5 Predictive Maintenance
- 5.4.6 Natural Language Processing
- 5.4.7 Speech Recognition
- 5.4.8 Others
- 5.5 By End-user Vertical
- 5.5.1 BFSI
- 5.5.2 Healthcare
- 5.5.3 Retail and E-Commerce
- 5.5.4 Defense and Government
- 5.5.5 Media and Entertainment
- 5.5.6 Logistics and Transportation
- 5.5.7 Energy and Utilities
- 5.5.8 Manufacturing
- 5.5.9 Other End-user Verticals
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Malaysia
- 5.6.4.6 Singapore
- 5.6.4.7 Australia
- 5.6.4.8 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 DataRobot Inc.
- 6.4.2 H2O.ai Inc.
- 6.4.3 C3.ai Inc.
- 6.4.4 Hugging Face Inc.
- 6.4.5 DeepMind Technologies Ltd.
- 6.4.6 OpenAI Inc.
- 6.4.7 Clarifai Inc.
- 6.4.8 GMDH LLC
- 6.4.9 Neural Designer (Artelnics S.L.)
- 6.4.10 Alyuda Research LLC
- 6.4.11 Neural Technologies Ltd.
- 6.4.12 Neuralware LLC
- 6.4.13 AND Corporation
- 6.4.14 Abacus.ai
- 6.4.15 OctoML Inc.
- 6.4.16 Databricks Inc.
- 6.4.17 Seldon Technologies Ltd.
- 6.4.18 Weights and Biases Inc.
- 6.4.19 Comet ML Inc.
- 6.4.20 Run:AI Labs Ltd.
- 6.4.21 Lightning AI Inc.
- 6.4.22 KNIME AG
- 6.4.23 RapidMiner Inc.
- 6.4.24 LatticeFlow AG
- 6.4.25 Pachyderm Inc.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment