

|
시장보고서
상품코드
2122303
프라이버시 필터 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Privacy Filters - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
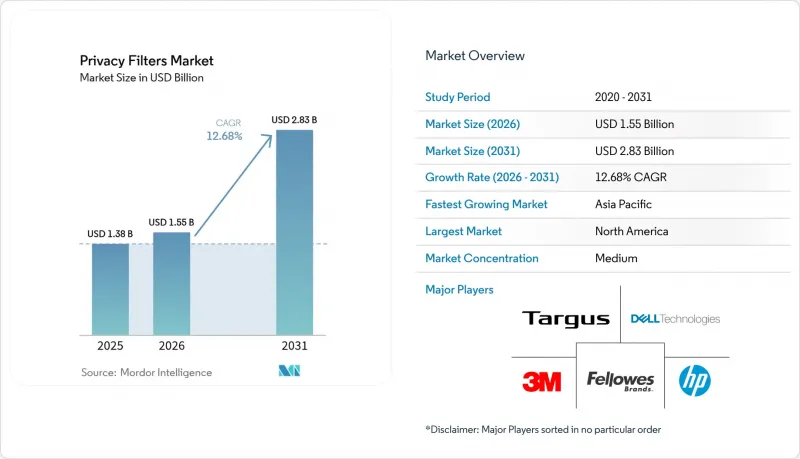
에 의하면, 프라이버시 필터 시장 규모는 2025년 13억 8,000만 달러로 평가되었고, 2026년에는 15억 5,000만 달러로 추정되고, 2026-2031년 CAGR 12.68%로 성장을 지속할 전망이며, 2031년까지 28억 3,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형별(양방향 프라이버시 필터 등), 소재 기술별(마이크로 루버 필름 필터 등), 디바이스 크기별(15-24인치 화면, 24인치 이상 화면 등), 최종 사용자별(기업 사무실, 금융 서비스 등), 유통 채널별(온라인 소매, 오프라인 소매, OEM 직접 탑재) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 프라이버시 필터 시장 동향 및 인사이트
기업 환경에서의 데이터 개인정보 보호 규제 강화
유럽연합(EU) 규제 당국은 2024년, GDPR(EU 개인정보보호규정) 위반에 대해 41억 유로(44억 달러)의 벌금을 부과했으며, 그 중 18%는 화면상의 데이터 노출과 관련된 사례였습니다. 미국 연방거래위원회(FTC)는 그램-리치-브라이리법(GLB법)의 안전장치 규정을 개정하여, 화면 엿보기에 대한 문서화된 관리 조치를 의무화했습니다. 캐나다, 멕시코, 아랍에미리트(UAE) 당국도 유사한 규제를 제정함에 따라, 다국적 기업들은 감사의 일관성을 확보하기 위해 전 세계 사무실에 프라이버시 필터를 도입하기 시작했습니다. 현재 조달 부서에서는 보안 예산에 암호화 및 다단계 인증과 함께 광학식 스크린도 예산 항목으로 편성하고 있습니다. 이러한 규제의 통합으로 인해 벌금이 증가하고 감사 주기가 단축되는 가운데, 프라이버시 필터 시장은 급격한 확산 곡선을 그리고 있습니다.
원격 근무 및 하이브리드 근무의 확대 추세
하이브리드 근무로 인해 보안 경계가 모호해지면서, 직원들은 카페나 전철 안, 공용 공간 등에서 기밀 데이터를 다루게 되었습니다. 공공장소에서 화면이 노출되면 위험이 높아지지만, 시각적 프라이버시 보호 액세서리를 제공하는 고용주는 3분의 1에 그치고 있어, 직원들이 자비로 구매하는 2차 수요의 물결을 일으키고 있습니다. 온라인 소매업은 이러한 분산된 주문에 대응하고 있으며, 2024년에는 45.63%의 채널 점유율을 유지하고 있습니다. 항공사, 철도 사업자, 호텔 체인은 좌석 등받이나 로비 키오스크에 내장형 프라이버시 패널을 추가하기 시작했으며, 이는 모빌리티가 프라이버시 필터 시장을 기존의 데스크 환경을 넘어 확장시키고 있음을 보여줍니다.
선진국 시장에서 데스크톱 모니터 교체 주기의 장기화
모니터의 수명이 연장됨에 따라, 기존에는 프라이버시 필터 판매를 견인하던 교체 계기가 줄어들고 있으며, 특히 24인치를 초과하는 화면 크기에서 이러한 경향이 두드러집니다. 모바일 팀을 위해 노트북을 우선시하는 조직들은 데스크톱 도입을 미루고 있어, 당분간 목표 시장 규모가 축소되고 있습니다. 각 벤더사는 노후화된 기기를 대상으로 한 사후 장착 키트나 자석식 프레임으로 대응하고 있지만, 모바일 기기로의 구조적인 전환으로 인해 프라이버시 필터 시장의 레거시 부문에서의 성장은 둔화되고 있습니다.
부문 분석
4방향 설계는 모든 방향에서 차광이 가능하여 오픈 플랜 사무실, 트레이딩 플로어, 공공 키오스크 등의 요구를 충족시키고 있습니다. 모든 방향의 시선으로부터의 보호가 요구되므로, 4방향 제품의 프라이버시 필터 시장 규모는 급속히 확대될 전망입니다. 2025년에도 2방향 모델은 여전히 매출의 49.10%를 차지했지만, 핫데스크 이용이 확대됨에 따라 그 우위는 점차 약화되고 있습니다. 각 벤더사는 터치스크린 지원, 화면 밝기를 유지하면서 인체공학적 기준을 충족하는 블루라이트 저감 코팅 등을 통해 차별화를 꾀하고 있습니다.
일렉트로크로믹 방식의 채택은 현재로서는 틈새 시장이지만, 설치의 번거로움을 줄이고 협업 모드와 프라이버시 모드 간의 즉각적인 전환을 가능하게 합니다. 국방 및 금융 부문이 초기 도입자로 나서면서, 기존 제품보다 3배에 달하는 프리미엄 가격대의 타당성이 입증되고 있습니다. 각 OEM 업체들이 패널 조립 단계에서 마이크로 루버나 일렉트로크로믹 층을 통합하게 됨에 따라, 애프터마켓의 클립온형 제품에 대한 수요는 광범위한 기기에 대응하기보다는 특정 이용 사례에 특화된 쪽으로 전환될 것으로 예상되며, 이는 프라이버시 필터 시장의 향후 판매 채널 구성을 재편하게 될 것입니다.
3M사의 독자적인 광 제어 기술을 기반으로 한 마이크로 루버 필름은 2025년에 매출의 60.73%를 차지했습니다. 이는 화면의 밝기와 선명도 간의 균형을 고려했을 때 여전히 벤치마크로 자리 잡고 있습니다. 그러나 나노 구조 메타서페이스는 명암비를 유지하면서 두께를 30% 줄이는 데 성공했으며, 이는 초슬림 노트북이나 폴더블 기기에 있어 이점이 됩니다. 연평균 성장률(CAGR)이 13.35%를 나타낼 것으로 예측되는 나노기술의 채택은 기기의 경량화와 재활용 공정의 간소화를 약속하며, EU의 순환 경제 행동 계획에서 지적된 폴리카보네이트 폐기물에 대한 우려를 해소할 것입니다.
일렉트로크로믹 폴리머는 동적 불투명도 제어를 실현하는 한편, 회로와 관련된 폐기 문제도 야기합니다. 현재 소재 선정은 환경 정책과 밀접하게 연관되어 있으며, 바이오 폴리카보네이트는 확대 생산자 책임(EPR) 지침 준수를 목표로 하는 유럽의 구매자들로부터 주목을 받고 있습니다. 이러한 변화는 광학 필름 제조업체와 디스플레이 제조 공장 간의 업스트림 단계에서 협력 기회를 창출하며, 프라이버시 필터 시장 전체의 부품 가격을 안정화시키는 장기 공급 계약의 토대가 됩니다.
지역별 분석
북미는 HIPAA(의료보험 이동성 및 책임에 관한 법률)의 의무 조항과 시각적 프라이버시를 필수 보호 조치로 규정하는 개정된 그램-리치-브라이리 법의 시행에 힘입어 2025년 매출의 33.20%를 차지했습니다. 높은 기기 보급률과 제로 트러스트형 사이버 보안의 도입이 기초 수요를 더욱 확대시키고 있습니다. 연방 정부 기관은 각 현지 사무소에서 프라이버시 스크린의 표준화를 추진하고 있으며, 캘리포니아주 프라이버시권법 등 주 정부의 프라이버시 관련 법규로 인해 민간 기업들은 법 집행에 따른 처벌을 피하기 위해 구매를 서두르고 있습니다.
아시아태평양은 중국의 ‘개인정보 보호법’ 및 인도의 ‘디지털 개인 데이터 보호법’ 시행으로 인해 규정 준수 기준이 강화됨에 따라, 2031년까지 13.62%라는 가장 높은 성장률을 나타낼 것으로 예측됩니다. IT 인프라의 급속한 확산, 노트북 보급률 향상, 그리고 정부 주도의 디지털화 프로젝트에 힘입어 도입 대수가 증가하고 있습니다. 대만과 한국에 제조 공장을 둔 각 OEM 기업들은 조립 공정에 개인정보 보호 기능을 통합하고 있으며, 이를 통해 해당 지역 내 구매자들의 수입 비용이 절감되고 있습니다.
유럽에서는 GDPR(EU 개인정보보호규정)에 따른 엄격한 처벌이 적용되고 있어, 프라이버시 필터는 수백만 유로 규모의 벌금에 대한 일종의 보험 역할을 하고 있습니다. 디스플레이 인체공학에 관한 ISO 규격은 재활용 가능한 소재를 요구하는 환경 정책의 추진과 맞물려, 조달 기준을 나노 구조 필름으로 이끌고 있는 요인이 되고 있습니다. UAE나 사우디아라비아 등 중동 국가에서는 GDPR(EU 개인정보보호규정)의 틀이 반영되어 있으며, 은행 및 공공 부문의 디지털 서비스에서 도입이 촉진되고 있습니다. 아프리카와 남미에서는 새로운 수요가 나타나고 있습니다. 남아프리카공화국의 POPIA와 브라질의 LGPD는 다국적 기업이 준수해야 할 법적 기준을 확립하여 초기 단계에서의 도입을 촉진하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the privacy filters market size is expected to grow from USD 1.38 billion in 2025 to USD 1.55 billion in 2026 and is forecast to reach USD 2.83 billion by 2031 at 12.68% CAGR over 2026-2031.
This report is Segmented by Product Type (2-Way Privacy Filters, and More), Material Technology (Microlouver Film Filters, and More), Device Size (15-24 Inch Screens, Above 24 Inch Screens, and More), End-User (Corporate Offices, Financial Services, and More), Distribution Channel (Online Retail, Offline Retail, Direct OEM Integration), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Privacy Filters Market Trends and Insights
Growing Data Privacy Regulations in Corporate Environments
European Union regulators imposed fines of EUR 4.1 billion (USD 4.4 billion) in 2024 for GDPR violations, with 18% of cases involving visual data exposure. The U.S. Federal Trade Commission revised the Gramm-Leach-Bliley Safeguards Rule to require documented controls against screen eavesdropping. Canada, Mexico, and UAE authorities enacted parallel mandates, prompting multinational firms to adopt privacy filters across global offices for audit uniformity. Procurement teams now list optical screens alongside encryption and multifactor authentication in security budgets. This regulatory alignment keeps the privacy filters market on a steep adoption curve as fines escalate and audit cycles shorten.
Rising Remote and Hybrid Working Trends
Hybrid work blurs the perimeter; employees handle sensitive data in cafes, on trains, and in shared spaces. Screen exposure in public venues heightens the risk, yet only one-third of employers supply visual privacy accessories, creating a secondary demand wave from staff who self-purchase. Online retail fulfills these fragmented orders, sustaining 45.63% channel share in 2024. Airlines, rail operators, and hospitality chains have begun adding embedded privacy panels to seat-backs and lobby kiosks, demonstrating how mobility expands the privacy filters market beyond the traditional desk environment.
Declining Desktop Monitor Refresh Cycles in Developed Markets
Extended monitor lifespans cut replacement-trigger events that historically drove privacy-filter sales, especially for screens larger than 24 inches. Organizations prioritizing laptops for mobile teams defer desktop rollouts, shrinking the immediate addressable base. Vendors respond with retrofit kits and magnetic frames aimed at aging fleets; however, the structural tilt toward mobile devices tempers growth in the legacy segment of the privacy filter market.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Laptop and Tablet Shipments Globally
- Expanding Healthcare IT Investments
- Price Sensitivity Among Consumer Buyers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
4-way designs enable omnidirectional shielding, meeting the demands of open-plan offices, trading floors, and public kiosks. The privacy filters market size for 4-way products is poised to expand rapidly because viewing angles from all sides require protection. In 2025, two-way models still accounted for 49.10% of revenue, yet their dominance is waning as hot desking grows. Vendors differentiate through touch-screen compatibility and blue-light reduction coatings that preserve image brightness while meeting ergonomic norms.
Electrochromic implementations, though currently niche, reduce attachment friction and support instant toggling between collaboration and privacy modes. The defense and finance sectors are early adopters, validating premium price points that reach three times the cost of conventional units. As OEMs embed microlouver or electrochromic layers at panel assembly, aftermarket clip-on demand is expected to shift toward specialized use cases rather than broad fleet coverage, reshaping future channel mix in the privacy filters market.
Microlouver film, underpinned by 3M's proprietary light-control technology, captured 60.73% revenue in 2025. It remains the benchmark for clarity versus the trade-off of dimming. However, nanostructure metasurfaces demonstrated 30% thickness reduction while sustaining contrast, an advantage for ultrathin laptops and foldables. Nanotech adoption, with a forecast near 13.35% CAGR, promises lighter devices and simplified recycling pathways, addressing polycarbonate waste concerns highlighted in the EU Circular Economy Action Plan.
Electrochromic polymers introduce dynamic opacity control but also pose disposal issues related to circuitry. Material selection now intertwines with environmental policy; bio-based polycarbonates are attracting European buyers seeking to comply with extended producer responsibility directives. Such shifts create opportunities for upstream partnerships between optical-film makers and display fabs, anchoring long-term supply agreements that stabilize component pricing across the privacy filter market.
Complete Report Scope:
- By Product Type
- 2-Way Privacy Filters
- 4-Way Privacy Filters
- Touch-Screen Optimized Filters
- Integrated OEM Privacy Displays
- By Material Technology
- Microlouver Film Filters
- Nanotechnology-Based Filters
- Electrochromic Switchable Filters
- By Device Size
- Less than or equal to 15 Inch Screens
- 15-24 Inch Screens
- Above 24 Inch Screens
- By End-User Industry
- Corporate Offices
- Healthcare Facilities
- Financial Services
- Government Agencies
- Educational Institutions
- By Distribution Channel
- Online Retail
- Offline Retail
- Direct OEM Integration
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 33.20% of 2025 revenue, propelled by HIPAA mandates and updated Gramm-Leach-Bliley rules that classify visual privacy as a required safeguard. High device ownership and the adoption of zero-trust cybersecurity amplify baseline demand. Federal agencies standardize privacy screens across their field offices, and state privacy statutes, such as the California Privacy Rights Act, spur private-sector purchases to avoid enforcement penalties.
The Asia-Pacific region is expected to register the fastest growth at 13.62% through 2031, as the implementation of China's Personal Information Protection Law and India's Digital Personal Data Protection Act raises compliance thresholds. Rapid IT infrastructure rollouts, increasing laptop penetration, and government digitization projects expand the install base. OEMs with fabs in Taiwan and South Korea integrate privacy layers during assembly, reducing import costs for regional buyers.
Europe enforces stringent GDPR penalties, positioning privacy filters as a form of insurance against multi-million-euro fines. ISO standards on display ergonomics converge with green policy pushes for recyclable materials, influencing procurement criteria toward nanostructured films. Middle East nations, such as the UAE and Saudi Arabia, mirror GDPR frameworks, fueling adoption in banking and public-sector digital services. Africa and South America exhibit emerging demand; South Africa's POPIA and Brazil's LGPD establish legal baselines that multinational firms must adhere to, facilitating early-stage deployments.
List of Companies Covered in this Report:
- 3M Company
- Targus International LLC
- Kensington Computer Products Group, a division of ACCO Brands Corporation
- Fellowes Inc.
- HP Inc.
- Dell Technologies Inc.
- V7 - Ingram Micro Inc.
- ViewSonic Corporation
- Lenovo Group Limited
- ZAGG Inc.
- PanzerGlass A/S
- Tech Armor LLC
- Amazon Basics (Amazon.com Inc.)
- Belkin International Inc.
- DMC Co. Ltd.
- Dicota GmbH
- Klear Screen LLC
- GlareGuard Screen Protectors LLC
- MOSISO (Mosiso LAB, Inc.)
- JCPal Technology Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Data Privacy Regulations in Corporate Environments
- 4.2.2 Rising Remote and Hybrid Working Trends
- 4.2.3 Increasing Laptop and Tablet Shipments Globally
- 4.2.4 Expanding Healthcare IT Investments
- 4.2.5 Integration of Privacy Filters into OEM Display Manufacturing Lines
- 4.2.6 Adoption of Smart Electrochromic Privacy Technologies for Defense Applications
- 4.3 Market Restraints
- 4.3.1 Declining Desktop Monitor Refresh Cycles in Developed Markets
- 4.3.2 Price Sensitivity Among Consumer Buyers
- 4.3.3 Compatibility Challenges with Curved and Foldable Displays
- 4.3.4 Environmental Concerns Over Disposal of Polycarbonate-Based Filters
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 2-Way Privacy Filters
- 5.1.2 4-Way Privacy Filters
- 5.1.3 Touch-Screen Optimized Filters
- 5.1.4 Integrated OEM Privacy Displays
- 5.2 By Material Technology
- 5.2.1 Microlouver Film Filters
- 5.2.2 Nanotechnology-Based Filters
- 5.2.3 Electrochromic Switchable Filters
- 5.3 By Device Size
- 5.3.1 Less than or equal to 15 Inch Screens
- 5.3.2 15-24 Inch Screens
- 5.3.3 Above 24 Inch Screens
- 5.4 By End-User Industry
- 5.4.1 Corporate Offices
- 5.4.2 Healthcare Facilities
- 5.4.3 Financial Services
- 5.4.4 Government Agencies
- 5.4.5 Educational Institutions
- 5.5 By Distribution Channel
- 5.5.1 Online Retail
- 5.5.2 Offline Retail
- 5.5.3 Direct OEM Integration
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Russia
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 Middle East
- 5.6.4.1.1 Saudi Arabia
- 5.6.4.1.2 United Arab Emirates
- 5.6.4.1.3 Rest of Middle East
- 5.6.4.2 Africa
- 5.6.4.2.1 South Africa
- 5.6.4.2.2 Egypt
- 5.6.4.2.3 Rest of Africa
- 5.6.4.1 Middle East
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 3M Company
- 6.4.2 Targus International LLC
- 6.4.3 Kensington Computer Products Group, a division of ACCO Brands Corporation
- 6.4.4 Fellowes Inc.
- 6.4.5 HP Inc.
- 6.4.6 Dell Technologies Inc.
- 6.4.7 V7 - Ingram Micro Inc.
- 6.4.8 ViewSonic Corporation
- 6.4.9 Lenovo Group Limited
- 6.4.10 ZAGG Inc.
- 6.4.11 PanzerGlass A/S
- 6.4.12 Tech Armor LLC
- 6.4.13 Amazon Basics (Amazon.com Inc.)
- 6.4.14 Belkin International Inc.
- 6.4.15 DMC Co. Ltd.
- 6.4.16 Dicota GmbH
- 6.4.17 Klear Screen LLC
- 6.4.18 GlareGuard Screen Protectors LLC
- 6.4.19 MOSISO (Mosiso LAB, Inc.)
- 6.4.20 JCPal Technology Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


