|
시장보고서
상품코드
2122309
가정용 라우터 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Residential Routers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 가정용 라우터 시장 규모는 2025년에 132억 1,000만 달러, 2026년에 145억 8,000만 달러로 평가되었고 2031년까지 226억 2,000만 달러에 이를 것으로 예측되며, 2026-2031년까지 CAGR은 9.18%를 기록할 전망입니다.
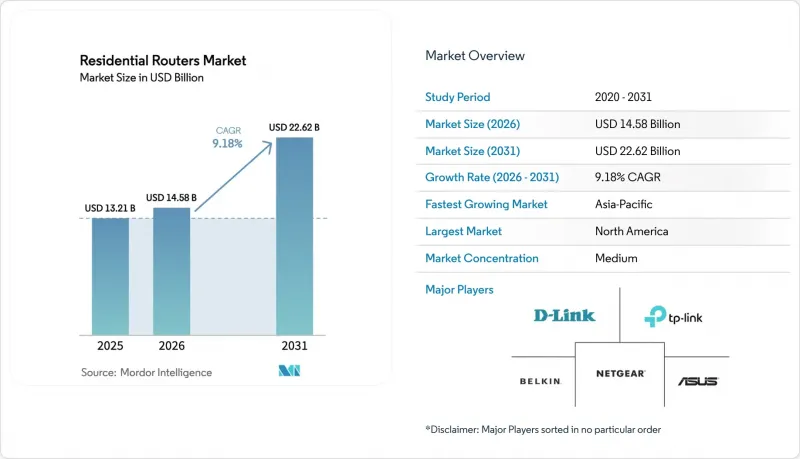
본 보고서는 연결 유형별(유선, 무선), Wi-Fi 규격 세대별(Wi-Fi 4, Wi-Fi 5, 기타), 제품 폼 팩터별(독립형 라우터, 메시 Wi-Fi 시스템, 기타),유통 채널별(소매, 온라인/전자상거래, 기타), 최종 사용자 가구 유형별(단독 주택, 다세대 주택(MDU), 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 가정용 라우터 시장 동향 및 인사이트
스마트 홈 및 IoT 기기의 보급
2025년까지 북미에서는 가구당 연결 기기 수가 17대, 유럽에서는 12대에 달했습니다. 이러한 포화 상태로 인해, 원래 10대 이하의 동시 연결을 가정하고 설계된 구형 라우터는 점차 시대에 뒤처지고 있습니다. 4K 동영상 동시 스트리밍, 스마트 온도 조절기 폴링, 보안 카메라 영상 업로드 중에 지연 현상을 겪는 가구에게 트라이밴드나 메쉬 시스템은 더 이상 사치품이 아니라 생활 필수품으로 간주되고 있습니다. 각 ISP 업체들은 이 문제를 해결하기 위해 신규 광회선 도입 시 Wi-Fi 6E 및 Wi-Fi 7 지원 게이트웨이를 번들로 제공하며, 가입자들을월10-15달러의 관리형 Wi-Fi 생태계에 묶어두고 있습니다. Matter를 통한 상호 운용성은 이제 표준이 되었으며, 각 제조업체는 Thread를 지원하는 보더 라우터 기능을 통합할 수밖에 없게 되었습니다. 이로 인해 플랫폼 중심의 신규 진출기업과 기존 하드웨어 브랜드 간의 경쟁은 하위 세분화되고 있습니다.
전 세계 IP 트래픽의 급증과 고속 광대역의 보급
세계 IP 트래픽은 2024년에 4.8 제타바이트에 도달할 것으로 예상되며, 2028년까지는 7.5 제타바이트를 넘어설 것으로 전망됩니다. 2025년에는 중국의 광섬유 보급률이 52%, 한국의 보급률이 48%를 넘어설 것으로 예상되며, 2.5Gbps 또는 10Gbps WAN 포트를 갖춘 라우터에 대한 수요가 증가하고 있습니다. 이에 대응하여 북미의 케이블 사업자들은 DOCSIS 4.0 게이트웨이에 Wi-Fi 7 무선 기능을 통합함으로써, 수익원을 하드웨어에서 지속적인 관리형 서비스 요금으로 전환했습니다. 인도에서는 BharatNet이 백본 용량을 25만 개의 마을까지 확대했으나, 25달러 미만의 라우터에는 펌웨어 업데이트를 위한 인프라가 구축되어 있지 않아 지방 사용자들은 봇넷의 위협에 노출되어 있습니다. 이러한 동향으로 인해 가정용 라우터 시장은 ISP가 관리하는 게이트웨이와 프리미엄 애호가용 기기 사이에서 양극화가 진행되고 있습니다.
심화되는 사이버 보안 및 개인정보 보호 위험
2024년에 성공한 IoT 봇넷 침해 사건의 75%는 라우터를 대상으로 했습니다. EU의 ‘사이버 복원력 법(Cyber Resilience Act)’은 현재 5년간의 보안 업데이트 의무화를 규정하고 있으며, 이로 인해 부품 원가가 3-5달러 증가하여 낮은 이익률을 기록하는 브랜드들은 곤경에 처해 있습니다. 미국에서는 FCC의 자발적인 사이버 보안 라벨이 충분히 활용되지 못하고 있는 상황이 지속되고 있습니다. 그 이유는 많은 소비자가 기술적 인증 마크를 이해하지 못하기 때문입니다. 일부 ISP 게이트웨이가 광고 타겟팅을 위해 브라우징 메타데이터를 수집하고 있다는 사실이 밝혀지면서, 개인정보 보호 운동이 활발해지고 있으며, 사업자들에게 옵트인 방식의 도입을 요구하는 압력이 높아지고 있습니다. 각 가정이 규제 명확화를 기다리는 가운데, 업그레이드 주기는 둔화되고 있으며, OEM 기업들은 기능 혁신에서 규정 준수 대응으로 예산을 전환하고 있습니다.
부문 분석
무선 라우터는 2025년에 가정용 라우터 시장 점유율의 78.46%를 차지하며, 연평균 성장률(CAGR) 10.17%로 성장할 전망입니다. 이는 동시 스트리밍 및 원격 근무로 인한 부하를 관리할 수 있는 능력을 반영한 것입니다. 3개 이상의 동영상 세션을 동시에 이용하는 가정에서는 고가의 구조화된 배선이 필요한 유선식 대체 제품보다 트라이밴드 기계식 제품이 선호되고 있습니다. 각 ISP 업체들은 사각지대를 해소하는 메시 지원 게이트웨이를 번들로 제공하여 무선 도입을 가속화하고, 가정용 라우터 시장을 구독 모델로 전환시키고 있습니다. 유선 부문은 고빈도 거래 등 지연에 민감한 틈새 시장에서 여전히 입지를 유지하고 있지만, Wi-Fi 7이 유선에 가까운 성능을 구현함에 따라 그 축소 추세는 지속될 전망입니다.
현재 무선 제품의 가치 제안을 정의하는 것은 메시 생태계와 AI 지원 로밍입니다. EU 무선기기 지침에 따른 USB-C 충전기의 표준화로 인해 전자 폐기물에 대한 우려가 완화되면서, 라우터 교체에 대한 고려 기간이 단축되고 있습니다. 독일이나 일본처럼 모든 방에 이더넷 잭이 완비된 시장에서도 유연성을 확보하기 위해 세션 종단은 여전히 Wi-Fi 엔드포인트에서 이루어지고 있습니다. 따라서 IoT 보급률이 높아짐에 따라 가정용 라우터 시장은 결정적으로 무선 중심의 모습을 유지할 것으로 보입니다.
2025년 출하 대수에서 Wi-Fi 6 및 6E가 차지하는 비율은 47.82%였으나, Wi-Fi 7은 연평균 성장률(CAGR) 10.88%로 가장 빠른 성장이 예상됩니다. 멀티링크 작동을 통해 2.4GHz, 5GHz, 6GHz 각 대역을 통합하여 클라우드 게임 및 증강현실(AR)을 위한 결정론적 지연을 실현합니다. ISP는 서비스 개통 시 802.11be를 지원하는 게이트웨이를 배포하고 있으며, 이를 통해 기존에 새로운 규격이 널리 보급되기까지 발생하던 도입 지연이 해소되고 있습니다. 중국에서는 6GHz 대역이 실내 사용으로 제한되어 있어 듀얼 SKU 전략을 채택할 수밖에 없지만, 2027년까지는 수량에 따른 가격 책정이 정상화될 것으로 예측됩니다.
400달러를 초과하는 가격대의 애호가용 Wi-Fi 7 라우터는 브랜드의 간판 제품으로서의 역할을 하고 있으며, 판매 대수에서 차지하는 비율은 8% 이하입니다. 클라이언트 기기의 등장으로 인해 성능 격차가 Wi-Fi 5 기기의 교체를 촉진하고, 가정용 라우터 시장 규모를 더욱 확대시킬 것으로 보입니다.
지역별 분석
북미는 2025년 가정용 라우터 매출의 41.58%를 차지했습니다. 이는 광섬유 및 케이블 회선 요금제에 Wi-Fi 7 게이트웨이를 통합한 ISP의 번들 서비스가 뒷받침한 결과입니다. Comcast의 xFi 플랫폼은 3,200만 가구에 서비스를 제공하고 있으며, AI를 활용한 최적화 기능을월14달러에 유료화하고 있습니다. AT&T와 Verizon도 유사한 전략을 채택하여 원격 진단을 통해 현장 방문 비용을 28% 절감했습니다. 메쉬 시스템의 평균 판매 가격은 140-200달러로 여전히 높은 수준을 유지하고 있습니다. FCC의 사이버 보안 라벨과 같은 규제 조치는 규정 준수 부담을 가중시키는 한편, 소비자의 선택에 뚜렷한 변화를 가져오지는 못했습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 10.62%를 기록하며, 지역별로는 가장 빠른 성장이 예상됩니다. 중국의 5억 8,000만 가구에 달하는 광섬유 연결 가구에는 멀티 기가 라우터가 필요한 반면, 인도의 ‘BharatNet’ 백본에서는 저가형 하드웨어의 보안 취약성이 부각되고 있습니다. 아세안(ASEAN)에서는 여전히 가격에 대한 민감도가 높아, 라우터의 72%가 35달러 이하로 판매되고 있습니다. 일본과 한국에서는 통신 사업자가 10Gbps 서비스를 번들로 제공하고 있어 Wi-Fi 7 도입이 앞서고 있습니다.
유럽은 2025년에 전 세계 매출의 22%를 차지할 것으로 예상되며, 확립된 인증 절차를 갖춘 브랜드를 우대하는 ‘EU 사이버 복원력 법’ 및 ‘에코디자인 지침’의 영향을 받고 있습니다. BeFibre와 EE는 AI가 탑재된 Wi-Fi 7 요금제를월15달러로 설정하여 해지율을 18% 감소시켰습니다. 독일의 구조화된 배선 기준으로 인해 메시 네트워크의 보급은 둔화되고 있지만, 2025년에는 광섬유 보급률이 48%에 달하여 멀티 기가 라우터에 대한 잠재적 수요가 발생하고 있습니다. 남미, 중동 및 아프리카의 합계 매출액은 18%를 차지했으나, 수입 관세 및 환율 변동의 영향을 받아 성장세가 주춤하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the residential routers market size was valued at USD 13.21 billion in 2025, USD 14.58 billion in 2026, and is projected to attain USD 22.62 billion by 2031, translating into a 9.18% CAGR during the 2026-2031 period.
This report is Segmented by Connectivity Type (Wired, and Wireless), Wi-Fi Standard Generation (Wi-Fi 4, Wi-Fi 5, and More), Product Form Factor (Stand-Alone Routers, Mesh Wi-Fi Systems, and More), Distribution Channel (Retail, Online/E-commerce, and More), End-User Household Type (Single-Family Homes, Multi-Dwelling Units, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Residential Routers Market Trends and Insights
Proliferation of Smart-Home and IoT Devices
Connected-device density climbed to 17 units per household in North America and 12 in Europe by 2025. This saturation forces legacy routers, originally designed for fewer than 10 concurrent links, into obsolescence. Households facing latency during simultaneous 4K streaming, smart-thermostat polling, and security-camera uploads now view tri-band or mesh systems as utilities rather than luxuries. ISPs exploit the pain point by bundling Wi-Fi 6E and Wi-Fi 7 gateways with new fiber installations, locking subscribers into managed Wi-Fi ecosystems at USD 10-15 per month. Matter interoperability has become baseline, compelling manufacturers to embed Thread border-router functionality that fragments competition between platform-centric entrants and traditional hardware brands.
Surging Global IP Traffic and High-Speed Broadband Uptake
Global IP traffic reached 4.8 zettabytes in 2024 and will exceed 7.5 zettabytes by 2028. Fiber penetration surpassed 52% in China and 48% in South Korea during 2025, creating pull for routers with 2.5 Gbps or 10 Gbps WAN ports. North American cable operators responded by integrating Wi-Fi 7 radios into DOCSIS 4.0 gateways, shifting profit pools from hardware to recurring managed-service fees. In India, BharatNet extended backbone capacity to 250,000 villages, but the absence of firmware-update infrastructure in sub-USD 25 routers leaves rural users exposed to botnets. These dynamics polarize the residential routers market between ISP-controlled gateways and premium enthusiast gear.
Escalating Cybersecurity and Privacy Risks
Routers represented 75% of successful IoT botnet compromises in 2024. The EU Cyber Resilience Act now mandates five-year security-update commitments, adding USD 3-5 to bill of materials and squeezing low-margin brands. In the United States, a voluntary FCC cybersecurity label remains underused because most consumers cannot interpret technical badges. Privacy advocacy intensified after revelations that some ISP gateways harvest browsing metadata for ad targeting, pressuring operators to adopt opt-in frameworks. As households wait for regulatory clarity, upgrade cycles slow and OEMs divert budgets from feature innovation to compliance.
Other drivers and restraints analyzed in the detailed report include:
- Migration to Wi-Fi 6/6E/7 Standards Fueling Replacement Cycles
- ISP Fiber Roll-Outs Bundling Wi-Fi 7 Gateways at Scale
- Price Sensitivity in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wireless routers held 78.46% residential routers market share in 2025 and are set to grow at a 10.17% CAGR, reflecting their ability to manage simultaneous streams and remote-work loads. Households that host three or more concurrent video sessions favor tri-band units over wired alternatives that require costly structured cabling. ISPs accelerate wireless adoption by bundling mesh-capable gateways that erase dead zones, moving the residential routers market toward subscription models. The wired segment persists in latency-sensitive niches such as high-frequency trading, yet its contraction will continue as Wi-Fi 7 delivers near-wired performance.
Mesh ecosystems and AI-assisted roaming now define the wireless value proposition. The EU Radio Equipment Directive's standardization on USB-C chargers lowers e-waste objections and shortens router replacement deliberations. Markets like Germany and Japan, which integrate Ethernet jacks in every room, still end sessions on Wi-Fi endpoints for flexibility. The residential routers market will therefore remain decisively wireless as IoT density rises.
Wi-Fi 6 and 6E accounted for 47.82% of shipments in 2025, yet Wi-Fi 7 is poised for the fastest growth at 10.88% CAGR. Multi-link operation aggregates 2.4 GHz, 5 GHz, and 6 GHz bands to deliver deterministic latency for cloud gaming and augmented reality. ISPs distribute 802.11be gateways during service activation, cutting the adoption lag that historically separates new standards from mass uptake. China's restriction of 6 GHz to indoor use forces dual-SKU strategies, but volume pricing will normalize by 2027.
Enthusiast-grade Wi-Fi 7 routers priced above USD 400 serve as brand halo products and constitute less than 8% of unit volume. As client devices arrive, the performance gulf will motivate replacements of Wi-Fi 5 units, further propelling the residential routers market size.
Complete Report Scope:
- By Connectivity Type
- Wired
- Wireless
- By WiFi Standard Generation
- Wi-Fi 4 (802.11n)
- Wi-Fi 5 (802.11ac)
- Wi-Fi 6 / 6E (802.11ax)
- Wi-Fi 7 (802.11be)
- By Product Form Factor
- Stand-alone Routers
- Mesh Wi-Fi Systems
- Modem- Router Gateways (IADs)
- 5G/ FWA Home Gateways
- By Distribution Channel
- Retail (In-store)
- Online/ E-commerce
- ISP Bundled/ Leased
- Direct-to-Consumer Brands
- By End-User Household Type
- Single- Family Homes
- Multi- Dwelling Units (MDUs)
- Small Office/ Home Office (SOHO)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America generated 41.58% of residential router revenue in 2025, propelled by ISP bundling that embeds Wi-Fi 7 gateways into fiber and cable tiers. Comcast's xFi platform serves 32 million households and monetizes AI-driven optimization at USD 14 per month. AT&T and Verizon adopted similar tactics, cutting truck-roll costs by 28% through remote diagnostics. Average selling prices remain high at USD 140-200 for mesh systems. Regulatory moves such as the FCC cybersecurity label add compliance overhead without visibly shifting consumer choices.
Asia-Pacific is forecast to deliver the fastest regional expansion at a 10.62% CAGR through 2031. China's 580 million fiber households require multi-gig routers, while India's BharatNet backbone highlights security gaps in low-cost hardware. ASEAN nations remain price sensitive, with 72% of routers priced below USD 35. Japan and South Korea lead Wi-Fi 7 adoption as operators bundle 10 Gbps services.
Europe held 22% of global revenue in 2025, shaped by the EU Cyber Resilience Act and Ecodesign mandates that favor brands with established certification pipelines. BeFibre and EE priced AI-powered Wi-Fi 7 tiers at USD 15 per month, trimming churn by 18%. Germany's structured wiring norms slow mesh proliferation, yet fiber penetration reached 48% in 2025, creating latent demand for multi-gig routers. South America, the Middle East, and Africa combined for 18% of revenue, constrained by import tariffs and currency volatility.
- NETGEAR Inc.
- TP-LINK Technologies Co., Ltd.
- D-Link Corporation
- Belkin International, Inc. (Linksys)
- ASUSTeK Computer Inc.
- Google LLC (Nest Wi-Fi, eero)
- Cisco Systems, Inc.
- Huawei Technologies Co., Ltd.
- Xiaomi Inc.
- Synology Inc.
- TRENDnet, Inc.
- Buffalo Inc.
- Ubiquiti Inc.
- CommScope Holding Company, Inc. (ARRIS)
- Zyxel Communications Corp.
- Amazon.com, Inc. (eero LLC)
- Sercomm Corporation
- Qualcomm Incorporated (Networking Pro platforms)
- Tenda Technology Co., Ltd.
- Mercusys Technologies Co., Ltd.
- Amped Wireless (Newo Corporation)
- Nokia Corporation (Fixed Networks CPE)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Smart-Home and IoT Devices
- 4.2.2 Surging Global IP Traffic and High-speed Broadband Uptake
- 4.2.3 Migration to Wi-Fi 6/6E/7 Standards Fueling Replacement Cycles
- 4.2.4 ISP Fiber Roll-outs Bundling Wi-Fi 7 Gateways at Scale
- 4.2.5 AI-driven Managed-Wi-Fi Subscriptions Boosting Premium Router Demand
- 4.2.6 Energy-efficiency Mandates Prompting Low-power Router Upgrades
- 4.3 Market Restraints
- 4.3.1 Escalating Cybersecurity and Privacy Risks
- 4.3.2 Price Sensitivity in Emerging Markets
- 4.3.3 User Skill Gaps Causing Feature Under-Utilization, Delaying Upgrades
- 4.3.4 Chipset Supply-chain Volatility Creating Product Shortages and Price Spikes
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Connectivity Type
- 5.1.1 Wired
- 5.1.2 Wireless
- 5.2 By WiFi Standard Generation
- 5.2.1 Wi-Fi 4 (802.11n)
- 5.2.2 Wi-Fi 5 (802.11ac)
- 5.2.3 Wi-Fi 6 / 6E (802.11ax)
- 5.2.4 Wi-Fi 7 (802.11be)
- 5.3 By Product Form Factor
- 5.3.1 Stand-alone Routers
- 5.3.2 Mesh Wi-Fi Systems
- 5.3.3 Modem- Router Gateways (IADs)
- 5.3.4 5G/ FWA Home Gateways
- 5.4 By Distribution Channel
- 5.4.1 Retail (In-store)
- 5.4.2 Online/ E-commerce
- 5.4.3 ISP Bundled/ Leased
- 5.4.4 Direct-to-Consumer Brands
- 5.5 By End-User Household Type
- 5.5.1 Single- Family Homes
- 5.5.2 Multi- Dwelling Units (MDUs)
- 5.5.3 Small Office/ Home Office (SOHO)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 NETGEAR Inc.
- 6.4.2 TP-LINK Technologies Co., Ltd.
- 6.4.3 D-Link Corporation
- 6.4.4 Belkin International, Inc. (Linksys)
- 6.4.5 ASUSTeK Computer Inc.
- 6.4.6 Google LLC (Nest Wi-Fi, eero)
- 6.4.7 Cisco Systems, Inc.
- 6.4.8 Huawei Technologies Co., Ltd.
- 6.4.9 Xiaomi Inc.
- 6.4.10 Synology Inc.
- 6.4.11 TRENDnet, Inc.
- 6.4.12 Buffalo Inc.
- 6.4.13 Ubiquiti Inc.
- 6.4.14 CommScope Holding Company, Inc. (ARRIS)
- 6.4.15 Zyxel Communications Corp.
- 6.4.16 Amazon.com, Inc. (eero LLC)
- 6.4.17 Sercomm Corporation
- 6.4.18 Qualcomm Incorporated (Networking Pro platforms)
- 6.4.19 Tenda Technology Co., Ltd.
- 6.4.20 Mercusys Technologies Co., Ltd.
- 6.4.21 Amped Wireless (Newo Corporation)
- 6.4.22 Nokia Corporation (Fixed Networks CPE)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment