|
시장보고서
상품코드
2122315
열가소성 가황 고무(TPV) : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Thermoplastic Vulcanizate (TPV) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 열가소성 가황 고무(TPV) 시장 규모는 2025년 478.22 킬로톤, 2026년 503.66 킬로톤에서 2031년까지 652.67 킬로톤으로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 5.32%를 기록할 전망입니다.
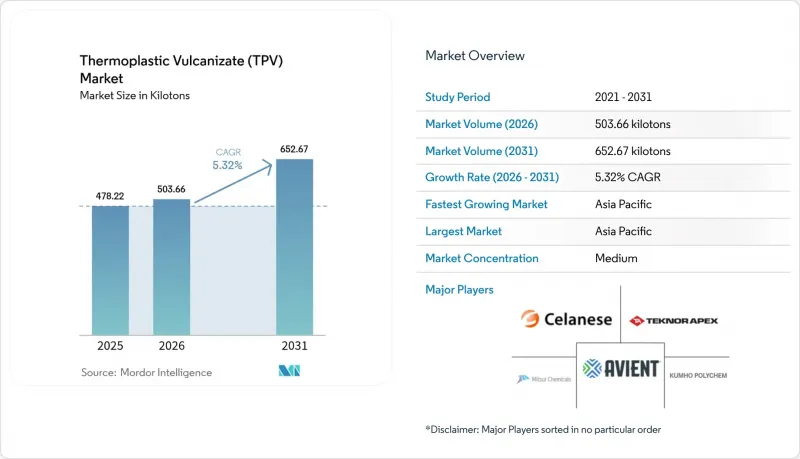
본 보고서는 제품 유형별(표준 EPDM/PP TPV, 고성능·내열성 TPV, 기타), 용도별(씰링 시스템·웨더스트립, 내장·외장 트림, 엔진룸 내 부품, 기타), 최종 사용자 산업별(자동차, 건축 및 건설, 기타),지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시되어 있습니다.
전 세계 열가소성 가황 고무(TPV) 시장 동향 및 인사이트
전 세계 자동차 제조업체의 경량화 수요 증가
자동차 경량화 목표는 주요 금속 구조에서 엘라스토머 부품으로 확대되고 있으며, 이에 따라 TPV는 부품 재설계가 필요 없이 도어 씰 및 유리 런 채널에서 열경화성 고무에 비해 20%-24%의 질량 감소 효과를 가져옵니다. 차량 총중량을 10% 줄일 때마다 배터리식 전기자동차의 주행 거리는 약 6%-8% 향상됩니다. 이는 유럽연합(EU)이 2027년에 설정한 차량군의 CO₂ 배출량 상한선(93.6g/km)을 충족하기 위해 각 OEM이 활용해야 할 효율화 수단입니다. BYD나 NIO 등 중국 자동차 제조업체들은 이미 양산 중인 EV 모델에 다중 소재 TPV 씰을 채택하고 있는 반면, 1차 공급업체인 쿠퍼 스탠다드와 도요타 고세이는 15% 이상의 복합 성장 목표를 달성하기 위해 2025년에 우한과 톈진의 TPV 압출 라인을 확장했습니다. 북미에서는 도입 속도가 여전히 완만하지만, 포드는 배터리 팩의 무게 증가를 상쇄하기 위해 2025년형 F-150 라이트닝에 TPV 벨트라인 씰을 사후 장착했습니다.
가전제품용 TPV 소프트 터치 부품 수요 급증
스마트폰,태블릿, 웨어러블 기기의 OEM 업체들은 폴리카보네이트나 ABS 재질의 케이스에 대해 쇼어 A 60-80의 TPV 오버몰드를 지정하고 있으며, 이를 통해 2차 도장 공정을 생략할 수 있을 뿐만 아니라 실리콘 엘라스토머에 비해 12%-15%의 불량률 감소 효과를 얻고 있습니다. 삼성이나 샤오미에 제품을 공급하는 베트남과 한국의 성형 제조업체들은 높은 굴곡 피로 내성이 요구되는 폴더블 스마트폰의 힌지 커버나 스마트 워치 밴드 수요에 힘입어, 2025년 TPV 출하량이 전년 대비 18% 증가했습니다. 고급 전자기기 제품 라인에서는 재생 가능한 원료를 포함한 TPV로의 전환이 진행되고 있지만, 비용을 중시하는 계약에서는 여전히 화석 유래 등급이 선호되어 25% 이상의 가격 차이가 발생하고 있습니다. 규제에 따른 압박은 미미하지만, 공급망 전반에 걸친 ISO 14001의 자발적 도입으로 인해 재활용 가능한 열가소성 플라스틱에 대한 선호도가 높아지고 있습니다.
프로파일렌 및 EPDM 원료 가격 변동
예기치 못한 크래커 가동 중단과 나프타 가격 변동으로 인해 2025년 4월 프로파일렌 현물 가격이 톤당 1,120달러까지 상승했으나, 하반기에는 안정화되었습니다. 한편, 유럽의 EPDM 계약 가격은 주요 제조업체들의 생산 능력 감축에 따라 전 분기 대비 12% 급등했습니다. TPV 컴파운더는 일반적으로 하류 가격을 12-24개월 동안 고정하고 있기 때문에 원료 가격의 급등으로 인해 매출 총이익률이 최대 300베이시스포인트까지 축소되었습니다. 이러한 압박은 아시아태평양에서 가장 심각했으며, 이 지역에서는 프로파일렌 유도체가 TPV 제조 원가의 60% 가까이 차지하고 있습니다.
부문별 분석
바이오 등급은 2031년까지 연평균 성장률(CAGR) 6.82%라는 가장 높은 성장률을 나타낼 것으로 예측됩니다. 쿠라레는 2024년에 재생 가능 원료 함유율 80%인 ‘SEPTON BIO’를 상용화했으며, 2026년형 토요타 차량용 내장 트림 계약을 수주했습니다. 표준 EPDM/PP 컴파운드는 2025년 생산량의 45.15%를 차지하며 여전히 주류를 이루고 있습니다. 이는 단위 비용이 kg당 2.80-3.20달러로, 재생 가능 원료를 사용한 대체품보다 최대 30%나 저렴하기 때문입니다. 고성능 내열 TPV는 엔진룸 내 호스나 터보차저 덕트와 같은 중요한 용도로 채택되고 있으며, 과산화물 가교 공정이 더 복잡함에도 불구하고 프리미엄 가격을 유지하고 있습니다. 재활용 원료 함유 등급은 원료 확보 상황에 따라 달라지는데, 북미에서는 사용 후 엘라스토머의 5% 이하만이 기계적 재활용 과정으로 되돌아가기 때문에 컴파운더는 더 비싼 산업 폐기물에 의존할 수밖에 없습니다.
표준 EPDM/PP 등급은 1kg당 약 3kg의 CO2 환산에 해당하는 화석 유래 탄소 발자국을 가지고 있어, 유럽의 기업 지속가능성 보고 지침(CSRD)에 따라 엄격해지고 있는 스코프 3 배출량 감사 위험에 OEM 각사를 노출시키고 있습니다. 바이오 대체재는 20%-35%의 비용 프리미엄이 있음에도 불구하고, 눈에 띄는 실내 트림 분야에서 점유율을 확대되고 있습니다. 이는 재생 가능 탄소 공개가 높은 재료비를 상쇄하는 브랜딩 가치를 가져다주기 때문입니다. 고성능 과산화물 가황 등급은 배터리 팩이나 터보차저가 장착된 엔진에 적용할 수 있게 해 주지만, 재가공성이 저하되어 재활용성이 제한되며, 이는 순환 경제의 주장을 훼손하게 됩니다. 재생 원료를 포함한 TPV의 경우, 슈레더 잔여물의 선별이 개선될 때까지 생산 능력 제약이 지속될 전망입니다.
지역별 분석
아시아태평양은 2025년 TPV 생산량의 45.78%를 차지하며, 2031년까지 연평균 6.18%의 성장이 예상됩니다. 중국은 2024년에 550만 대의 자동차를 해외로 수출했으며, 이 30% 증가에 힘입어 절강 시안통 고무(Zhejiang Xiantong Rubber) 등 국내 컴파운더들은 TPV의 공칭 생산 능력을 매년 약 20%씩 확대되고 있습니다. 현재 세계 3위의 자동차 생산국인 인도에서는 높아지는 연비 목표를 달성하기 위해 이륜차와 소형차에 TPV를 채택하고 있습니다. 한편, 일본과 한국공급업체인 미쓰이 화학(Mitsui Chemicals)과 금호폴리켐(Kumho Polychem)은 토요타, 현대, 기아의 전기차 플랫폼용 내열 등급 제품을 지속적으로 공급하고 있습니다.
2025년에는 북미가 시장 수요의 대부분을 차지했습니다. 미국의 픽업 트럭 플랫폼은 여전히 내구성을 중시하고 있지만, 포드와 제너럴 모터스가 배터리 무게를 상쇄하기 위해 전기 트럭에 씰을 탑재함에 따라 TPV의 채택은 점차 증가하고 있습니다. 멕시코의 410만 대 규모의 조립 기지는 테크놀 아펙스의 마타모로스 공장에서 현지 TPV를 조달하고 있으며, 이를 통해 지역 컨버터는 공급망의 회복력을 확보하고 있습니다. 유럽 시장의 성장은 EU의 지속가능성 지침에 따라 바이오 및 재생 소재의 채택이 주도하고 있습니다. 독일, 프랑스, 이탈리아가 해당 지역의 TPV 수요의 60%를 차지하고 있으며, 폭스바겐, 스텔란티스, BMW가 스코프 3 배출량 감사를 강화하고 있습니다.
남미 시장은 브라질을 핵심으로 하고 있으며, 피아트와 폭스바겐은 소형 모델에 TPV製の 웨더스트립을 채택하고 있습니다. 중동 및 아프리카에서는 사우디아라비아와 아랍에미리트의 조립 공장이 수입 키트와 함께 TPV 부품을 수입하고 있어 전반적으로 성장의 조짐이 보입니다. 이러한 지역에서는 재생 재료 함유율 의무화나 EPR(생산자 책임 확대) 제도가 마련되어 있지 않아, 재생 가능 재료나 재생 재료를 사용한 등급의 도입이 지연되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the thermoplastic vulcanizate market size is projected to expand from 478.22 kilotons in 2025 and 503.66 kilotons in 2026 to 652.67 kilotons by 2031, registering a CAGR of 5.32% between 2026 to 2031.
This report is Segmented by Product Type (Standard EPDM/PP, High-Performance/Heat-Resistant, and More), Application (Sealing Systems, Interior/Exterior Trim, Under-The-Hood, and More), End-User (Automotive, Building and Construction, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). Market Forecasts are Provided in Terms of Volume (Tons).
Global Thermoplastic Vulcanizate (TPV) Market Trends and Insights
Rising Lightweighting Demand From Global Automotive OEMs
Automotive light-weighting goals have cascaded from primary metal structures to elastomeric parts, giving TPV a 20%-24% mass-saving edge over thermoset rubber in door seals and glass-run channels without part redesign. Every 10% curb-weight reduction improves battery-electric range by roughly 6%-8%, an efficiency lever OEMs need to satisfy the European Union's 2027 fleet CO2 cap of 93.6 g/km. Chinese automakers such as BYD and NIO already integrate multi-material TPV seals on high-volume EV models, while tier-one suppliers Cooper Standard and Toyoda Gosei expanded Wuhan and Tianjin TPV extrusion lines in 2025 to chase 15%-plus compound growth targets. Adoption remains slower in North America, yet Ford retrofitted TPV belt-line seals on the 2025 F-150 Lightning to offset battery-pack mass penalties.
Surge in TPV-Based Soft-Touch Parts for Consumer Electronics
Smartphone, tablet, and wearable OEMs specify Shore A 60-80 TPV overmolds on polycarbonate and ABS housings to eliminate secondary painting and capture a 12%-15% scrap-reduction benefit relative to silicone elastomers. Vietnam and Korea molders that serve Samsung and Xiaomi posted 18% year-on-year TPV volume gains in 2025, buoyed by foldable-phone hinge covers and smartwatch bands requiring high flex fatigue resistance. Premium electronics lines are migrating to renewable-content TPV, whereas cost-sensitive contracts still prefer fossil-derived grades, leaving a 25%-plus price delta. Regulatory pressure is minimal, but voluntary ISO 14001 adoption across the supply chain reinforces a recyclable-thermoplastic preference.
Volatility in Propylene and EPDM Feedstock Prices
Unplanned cracker outages and fluctuating naphtha costs lifted spot propylene to USD 1,120 per ton in April 2025 before easing later in the year, while European EPDM contracts jumped 12% quarter-over-quarter after capacity curtailments at major producers. TPV compounders normally lock downstream prices for 12-24 months, so rapid feedstock inflation compressed gross margins by up to 300 basis points. The pressure is heaviest in Asia-Pacific, where propylene derivatives account for almost 60% of TPV manufacturing cost.
Other drivers and restraints analyzed in the detailed report include:
- OEM Shift Toward Recyclable Elastomeric Materials
- Expansion of EV Battery-Pack Sealing Applications
- Inferior Long-Term Chemical/Wear Resistance vs. Thermoset Rubber
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bio-based grades are projected to grow with the highest CAGR of 6.82% CAGR through 2031. Kuraray commercialized SEPTON BIO in 2024 with 80% renewable content and secured Toyota interior-trim contracts for the 2026 model year. Standard EPDM/PP compounds still dominate with 45.15% of 2025 volume because their unit costs of USD 2.80-3.20 per kg undercut renewable alternatives by as much as 30%. High-performance heat-resistant TPV wins critical under-hood hose and turbocharger duct slots, sustaining premium pricing despite more complex peroxide cross-linking. Recycled-content grades depend on feedstock access; fewer than 5% of post-consumer elastomers in North America reenter mechanical recycling streams, forcing compounders to rely on pricier post-industrial scrap.
Standard EPDM/PP grades carry a fossil-derived carbon footprint near 3 kg CO2-equivalent per kg, exposing OEMs to tightening scope-3 emission audits under the European Corporate Sustainability Reporting Directive. Bio-based alternatives gain share in visible interior trim despite 20%-35% cost premiums because renewable-carbon disclosure provides branding value that offsets higher material expenses. High-performance peroxide-cured grades open battery-pack and turbocharged-engine doors, but reduced re-processability limits recyclability and truncates circular-economy claims. Recycled-content TPV remains capacity-constrained until shredder-residue sorting improves.
Complete Report Scope:
- By Product Type
- Standard EPDM/PP TPV
- High-Performance / Heat-Resistant TPV
- Bio-based TPV
- Recycled-content TPV
- By Application
- Sealing Systems and Weather-strips
- Interior and Exterior Trim
- Under-the-Hood Components
- Hose and Tubing
- Wire and Cable
- Medical Devices
- Consumer and Sporting Goods Parts
- By End-User Industry
- Automotive
- Building and Construction
- Consumer Goods
- Healthcare
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Malaysia
- Thailand
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- Qatar
- United Arab Emirates
- Nigeria
- Egypt
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific anchored 45.78% of 2025 TPV volume and is projected to grow at 6.18% through 2031. China shipped 5.5 million vehicles abroad in 2024, a 30% rise that has spurred domestic compounders such as Zhejiang Xiantong Rubber to boost TPV nameplate capacity by roughly 20% per year. India, now the world's third-largest vehicle producer, is adopting TPV on two-wheelers and compact cars to meet rising fuel-economy targets, while Japanese and Korean suppliers Mitsui Chemicals and Kumho Polychem continue to push heat-resistant grades for Toyota, Hyundai, and Kia EV platforms.
North America accounted for significant market demand in 2025. U.S. pickup platforms remain durability-oriented, yet TPV adoption is creeping upward as Ford and General Motors integrate seals on electrified trucks to offset battery weight. Mexico's 4.1-million-unit assembly base sources local TPV from Teknor Apex's Matamoros site, giving regional converters supply-chain resilience. Europe's market growth is driven by bio-based and recycled-content adoption due to EU sustainability directives. Germany, France, and Italy represent 60% of regional TPV needs as Volkswagen, Stellantis, and BMW intensify scope-3 emission audits.
South America market is centered on Brazil, where Fiat and Volkswagen apply TPV weatherstrips on compact models. The Middle East and Africa collectively register nascent growth as Saudi and UAE assembly plants import TPV parts alongside imported kits. Lack of mandatory recycled-content or EPR schemes slows the adoption of renewable or recycled grades in these regions.
- Avient Corporation
- Celanese Corporation
- DuPont
- Elastron TPE
- FM Plastics
- HEXPOL AB
- Kumho Polychem
- LCY
- LOTTE Chemical CORPORATION
- Mitsubishi Chemical Group Corporation
- Mitsui Chemicals Inc.
- Orbia (Alphagary)
- Ravago
- RTP Company
- Shandong Dawn Polymer Materials Co. Ltd
- Teknor Apex
- Trinseo
- Zylog ElastoComp LLP
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Lightweighting Demand from Global Automotive OEMs
- 4.2.2 Surge in TPV-Based Soft-Touch Parts for Consumer Electronics
- 4.2.3 OEM Shift Toward Recyclable Elastomeric Materials
- 4.2.4 Expansion of EV Battery-Pack Sealing Applications
- 4.2.5 Emergence of Bio-Based TPV Grades
- 4.3 Market Restraints
- 4.3.1 Volatility in Propylene and EPDM Feedstock Prices
- 4.3.2 Inferior Long-Term Chemical/Wear Resistance Vs. Thermoset Rubber
- 4.3.3 Lack of Closed-Loop Recycling Infrastructure for TPV Scrap
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Standard EPDM/PP TPV
- 5.1.2 High-Performance / Heat-Resistant TPV
- 5.1.3 Bio-based TPV
- 5.1.4 Recycled-content TPV
- 5.2 By Application
- 5.2.1 Sealing Systems and Weather-strips
- 5.2.2 Interior and Exterior Trim
- 5.2.3 Under-the-Hood Components
- 5.2.4 Hose and Tubing
- 5.2.5 Wire and Cable
- 5.2.6 Medical Devices
- 5.2.7 Consumer and Sporting Goods Parts
- 5.3 By End-User Industry
- 5.3.1 Automotive
- 5.3.2 Building and Construction
- 5.3.3 Consumer Goods
- 5.3.4 Healthcare
- 5.3.5 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Indonesia
- 5.4.1.6 Malaysia
- 5.4.1.7 Thailand
- 5.4.1.8 Vietnam
- 5.4.1.9 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Nordic Countries
- 5.4.3.7 Russia
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 Qatar
- 5.4.5.3 United Arab Emirates
- 5.4.5.4 Nigeria
- 5.4.5.5 Egypt
- 5.4.5.6 South Africa
- 5.4.5.7 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Avient Corporation
- 6.4.2 Celanese Corporation
- 6.4.3 DuPont
- 6.4.4 Elastron TPE
- 6.4.5 FM Plastics
- 6.4.6 HEXPOL AB
- 6.4.7 Kumho Polychem
- 6.4.8 LCY
- 6.4.9 LOTTE Chemical CORPORATION
- 6.4.10 Mitsubishi Chemical Group Corporation
- 6.4.11 Mitsui Chemicals Inc.
- 6.4.12 Orbia (Alphagary)
- 6.4.13 Ravago
- 6.4.14 RTP Company
- 6.4.15 Shandong Dawn Polymer Materials Co. Ltd
- 6.4.16 Teknor Apex
- 6.4.17 Trinseo
- 6.4.18 Zylog ElastoComp LLP
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment