|
시장보고서
상품코드
2122342
인플루엔자 진단 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Influenza Diagnostics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
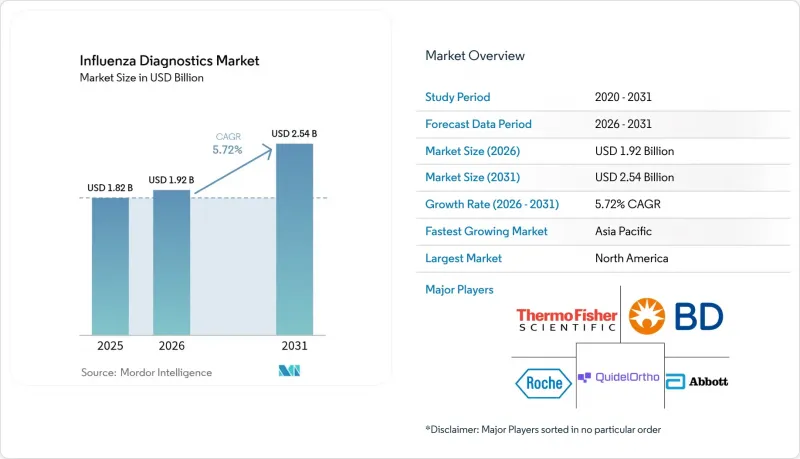
에 의하면, 인플루엔자 진단 시장 규모는 2025년에 18억 2,000만 달러로 평가되었고, 2026년 19억 2,000만 달러로 추정되고, 2031년까지 25억 4,000만 달러에 이를 것으로 예측됩니다. 예측 기간(2026-2031년) CAGR은 5.72%를 나타낼 전망입니다.
본 보고서는 검사 유형별(기존 진단 검사(신속 인플루엔자 진단 검사, 바이러스 배양 등) 및 분자진단 검사(RT-PCR, LAMP 등)), 최종 사용자별(병원 및 임상 실험실, 독립 진단 검사 기관 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 인플루엔자 진단 시장 동향 및 인사이트
계절성 독감 및 인수공통감염병으로서의 독감 유행 빈도와 중증도 증가
계절성 인플루엔자의 활동이 다시 활발해짐에 따라 전 세계 진단 수요가 증가하고 있습니다. 미국 질병통제예방센터(CDC)의 기록에 따르면, 2024-2025년 시즌에는 검사를 통해 확인된 입원 환자 수가 3만 9,053명에 달했으며, 이는 2010-2011년 시즌 이후 가장 높은 수치입니다. 동시에, 고병원성 H5N1의 발생으로 캘리포니아주의 낙농 종사자들 사이에서 38명의 인간 감염 사례가 확인되어 가축 모니터링 체계의 확대가 촉발되었습니다. 싱가포르의 ‘Steadfast’ 분석법 등 새로운 검사 키트는 3시간 이내에 고병원성 균주와 저병원성 균주를 구별할 수 있어 유행에 대한 대응 능력을 높이고 있습니다. 이러한 상황으로 인해 의료 시스템은 연중 내내 비상 수준의 검사 능력을 유지해야 할 필요에 직면해 있으며, 고정밀 분자진단 플랫폼의 조달이 계속되고 있습니다.
외래 진료 현장에서의 신속한 현장 진단(Point-of-Care) 검사 보급 확대
사우샘프턴 대학의 병원 연구에 따르면, POC(진료 현장)에서의 인플루엔자 검사를 통해 결과가 나오는 데 걸리는 시간이 1시간 미만으로 단축되어, 항바이러스제 투여 시작이 빨라지고 환자의 입원 기간도 단축되는 것으로 나타났습니다. 현재 검사 플랫폼에는 애보트(Abbott)사의 ‘ID NOW’와 같은 분자진단 옵션이 포함되어 있으며, A형 및 B형 독감 검사 결과를 13분 만에 제공하며, 민감도는 96.3%입니다. AI를 활용한 판독 장치를 통해 판정 시간은 최대 2분까지 단축됩니다. 운송 비용 절감과 진료 당일 치료 시작이 가능해짐에 따라, 진료소 및 소매 의료시설에서의 POC 검사 광범위한 도입은 경제적 이점을 제공합니다.
RIDT의 민감도와 위음성률의 편차
많은 RIDT는 바이러스 양이 적은 초기 감염을 놓치고 맙니다. 연구에 따르면 특정 시판 키트의 위음성률은 30% 이상의 것으로 나타났습니다. Panbio사의 COVID-19/인플루엔자 A·B 패널은 인플루엔자에 대한 민감도가 불과 80.8%에 그쳤습니다. WHO의 2024년판 지침에서는 중증 환자나 고위험군 환자에 대해서는 핵산 검사를 권장하고 있습니다. 진료소에서는 RIDT의 속도라는 장점을 상쇄하는 확인용 PCR 검사 워크플로가 도입되어 있어, 시장 점유율 확대가 억제되고 있습니다.
부문 분석
신속 검사 형식은 매출 점유율 41.10%를 차지하며 여전히 주류를 이루고 있지만, 임상의들이 민감도와 다중 검사를 우선시함에 따라 인플루엔자 진단 시장은 재편되고 있습니다. CRISPR 분석법은 2031년까지 연평균 성장률(CAGR) 9.28%를 나타낼 것으로 예상되며, 그 선두에는 15분 만에 아형을 식별할 수 있는 브로드 연구소의 SHINE 검사가 있습니다. A형·B형 인플루엔자, RSV, SARS-CoV-2를 한 세트로 묶은 분자 패널은 응급실의 업무 효율을 높이고 있습니다. CRISPR 플랫폼 내 인플루엔자 진단 시장 규모는 워크플로우 간소화와 장비 설치 공간 축소에 힘입어 모든 방식 중에서 가장 빠르게 확대될 것으로 예측됩니다. 직접 형광 항체법이나 바이러스 배양 검사는 균주 동정이나 항바이러스제 감수성 평가가 필요한 조사 분야에서는 계속해서 이용되고 있지만, 주류 구매 결정에는 더 이상 영향을 미치지 않습니다.
RT-PCR 및 등온법을 포함한 분자진단은 AI 도구를 통해 결과 해석이 효율화됨에 따라 도입이 가속화되고 있습니다. 멀티플렉스 CRISPR-Cas13a 스트립은 증폭 과정을 생략하면서도 RT-qPCR과 100% 일치율을 달성했습니다. 병원에서는 단일 검체 내에서 중복되는 호흡기 증상을 구별할 수 있는 증후군별 패널이 선호되는 반면, 소매 클리닉에서는 예약 없이 신속한 진료를 제공하기 위해 CLIA 면제 분자진단 카트리지가 채택되고 있습니다. 이러한 정확성과 속도의 융합으로 인해 자본적 장벽이 완화됨에 따라, 분자진단 솔루션은 RIDT의 주도적 지위를 잠식할 수 있는 위치에 서 있습니다.
지역별 분석
북미가 주도적인 위치를 차지하고 있는 것은 종합적인 감시 시스템과 성숙한 보상 모델 덕분입니다. CDC(미국 질병통제예방센터)는 125개국에 걸친 8개의 지역 감시 허브를 총괄하고 있지만, 검사 체계의 규모 면에서는 여전히 국내가 가장 큽니다. 북미의 인플루엔자 진단 시장 규모는 공급망 안정화를 목표로 서모피셔 사이언티픽이 국내 생산 확대를 위해 20억 달러를 투자한 덕을 보고 있습니다. 소매 약국에서는 CLIA 면제 분자진단 카트리지를 도입하여 내원 당일 진료를 실현하고 있는 한편, 건강보험사의 재택 검체 채취 키트에 대한 보험 적용이 확대되면서 소비자의 접근성이 높아지고 있습니다.
아시아태평양은 검사 시설의 급속한 확충과 정부의 자금 지원에 힘입어 7.78%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 동남아시아 전역에서 11곳의 국가 인플루엔자 센터가 완전히 가동되고 있다는 WHO의 성과는 이러한 진전을 뒷받침하고 있습니다. 일본은 ISO 13485:2016을 준수하도록 품질 관리 규정을 개정하여, 해외 검사법 개발자들의 승인 절차를 원활하게 했습니다. 중국과 인도는 백신 관련 mRNA 투자를 진단 분야로 전환하고, 지역 내 유통을 위한 국산 CRISPR 카트리지 개발을 촉진하고 있습니다.
유럽은 체외진단용 의료기기 규정(IVDR)을 통해 여전히 큰 영향력을 유지하고 있으며, 이로 인해 적합성 평가 대상이 되는 검사가 15%에서 90% 가까이 확대되었습니다. 2024년에 승인된 이행 기간 연장으로 당장공급 부족은 피할 수 있게 되었지만, 규정 준수 비용 증가로 인해 연구 개발이 더 적은 수의 고부가가치 검사로 전환될 가능성이 있습니다. 중동 및 아프리카 및 남미에서는 다자간 원조와 민관 파트너십을 통해 생산 능력 확대를 도모하고 있으며, OECD는 팬데믹 기간 동안 겪었던 물류 혼란을 완화하기 위해 조달처의 다각화를 강력히 요구하고 있습니다. 이러한 준비 상황의 편차로 인해 도입 진척도에는 차이가 나타나고 있지만, 호흡기 질환 감시에 대한 공통된 중시 태도가 검사 키트에 대한 전 세계적인 수요를 견고하게 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the influenza diagnostics market size was valued at USD 1.82 billion in 2025 and estimated to grow from USD 1.92 billion in 2026 to reach USD 2.54 billion by 2031, at a CAGR of 5.72% during the forecast period (2026-2031).
This report is Segmented by Test Type (Traditional Diagnostic Tests {Rapid Influenza Diagnostic Tests, Viral Culture, and More} and Molecular Diagnostic Tests {RT-PCR, LAMP, and More}), End User (Hospitals and Clinical Laboratories, Independent Diagnostic Laboratories, and More), and Geography (North America, Europe, Asia Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Influenza Diagnostics Market Trends and Insights
Rising Prevalence & Severity of Seasonal and Zoonotic Influenza Outbreaks
A resurgence in seasonal influenza activity has intensified global diagnostic demand, with the CDC logging 39,053 laboratory-confirmed hospitalizations during the 2024-2025 season, the highest rate since 2010-2011.Concurrently, highly pathogenic H5N1 outbreaks generated 38 human cases in California among dairy workers, prompting expanded livestock surveillance. New kits, such as Singapore's Steadfast assay, differentiate highly and low pathogenic strains within three hours, enhancing outbreak response. These events push health systems to retain emergency-level testing capacity year-round, sustaining procurement of high-accuracy molecular platforms.
Growing Adoption of Rapid Point-of-Care Tests in Outpatient Settings
Hospital studies from the University of Southampton showed that POC influenza testing cuts result time to under one hour, enabling faster antiviral initiation and shorter patient stays. Platforms now include molecular options like Abbott's ID NOW, which returns influenza A/B results in 13 minutes with 96.3% sensitivity. AI-enhanced readers further reduce interpretation time to two minutes. Lower transport costs and same-visit treatment support economic arguments for widespread POC deployment in clinics and retail health sites.
Variable Sensitivity & False-Negative Rate of RIDTs
Many RIDTs miss early infections when viral load is low; studies place false-negative rates above 30% for certain commercial kits. The Panbio COVID-19/Flu A&B panel delivered only 80.8% sensitivity for influenza. WHO's 2024 guidance now recommends nucleic-acid tests for severe or high-risk cases. Clinics have introduced confirmatory PCR workflows that erase the speed advantage of RIDTs, curbing segment expansion.
Other drivers and restraints analyzed in the detailed report include:
- Government-Funded Surveillance Programs & Pandemic-Preparedness Budgets
- AI-Powered Result-Interpretation Software Boosting Molecular Workflow Throughput
- High Capital & Running Cost of Molecular Diagnostic Platforms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rapid formats remained dominant with a 41.10% revenue share, yet the influenza diagnostics market is repositioning as clinicians prioritize sensitivity and multiplexing. CRISPR assays show 9.28% CAGR by 2031, led by the Broad Institute's SHINE test that discriminates subtypes in 15 minutes. Molecular panels that bundle influenza A/B, RSV, and SARS-CoV-2 deliver operational efficiency for emergency departments. The influenza diagnostics market size for CRISPR platforms is forecast to expand fastest among all modalities, driven by simplified workflows and shrinking instrument footprints. Direct fluorescent antibody and viral culture testing continue to serve research niches where strain typing or antiviral susceptibility is required, but they no longer influence mainstream purchasing decisions.
Molecular diagnostics, including RT-PCR and isothermal formats, see accelerated uptake as AI tools streamline result interpretation. Multiplex CRISPR-Cas13a strips achieved 100% concordance with RT-qPCR while removing amplification steps. Hospitals prefer syndromic panels that differentiate overlapping respiratory symptoms within a single sample, whereas retail clinics adopt CLIA-waived molecular cartridges for rapid walk-in encounters. This convergence of accuracy and speed positions molecular solutions to erode RIDT leadership as capital barriers abate.
Complete Report Scope:
- By Test Type
- Traditional Diagnostic Tests
- Rapid Influenza Diagnostic Tests (RIDTs)
- Direct Fluorescent Antibody (DFA) Tests
- Viral Culture
- Rapid Cell Culture
- Molecular Diagnostic Tests
- Reverse-Transcriptase PCR (RT-PCR)
- Loop-Mediated Isothermal Amplification (LAMP)
- Nicking-Enzyme Amplification Reaction (NEAR)
- CRISPR-based Assays
- Syndromic Multiplex PCR Panels
- Traditional Diagnostic Tests
- By End User
- Hospitals & Clinical Laboratories
- Independent Diagnostic Laboratories
- Point-of-Care Settings
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America's leadership stems from comprehensive surveillance systems and mature reimbursement models. The CDC coordinates eight regional surveillance hubs spanning 125 countries, yet maintains its largest testing footprint domestically. The influenza diagnostics market size in North America benefits from Thermo Fisher Scientific's USD 2 billion investment to expand domestic manufacturing, aimed at insulating supply chains. Retail pharmacies integrate CLIA-waived molecular cartridges for same-visit care, while health insurers increasingly reimburse home-collection kits, broadening consumer access.
Asia Pacific posts the fastest 7.78% CAGR owing to rapid laboratory build-outs and government funding. WHO's milestone of 11 fully operational national influenza centers across South-East Asia evidences this progress. Japan updated quality-management regulations to align with ISO 13485:2016, smoothing approval pathways for foreign assay developers. China and India funnel vaccine-related mRNA investments into diagnostics, fostering locally made CRISPR cartridges for regional distribution.
Europe remains influential through the In Vitro Diagnostic Regulation (IVDR), which raises conformity-assessment requirements from 15% to nearly 90% of assays. Transition extensions granted in 2024 prevent immediate supply shortages but raise compliance costs that could shift R&D to fewer, higher-value tests. Middle East & Africa and South America pursue capacity growth via multilateral aid and public-private partnerships; the OECD urges diversified sourcing to mitigate logistic shocks experienced during the pandemic. This uneven readiness shapes divergent adoption curves, yet shared emphasis on respiratory surveillance sustains global demand for robust assays.
- Roche
- Abbott Laboratories (incl. ID NOW)
- QuidelOrtho
- Thermo Fisher Scientific (Cepheid, Mesa Bio)
- Beckton Dickinson
- bioMerieux
- Hologic
- Siemens Healthineers
- Danaher Corp. (Cepheid)
- Sekisui Diagnostics
- GenMark Diagnostics (Roche)
- Meridian Bioscience
- Luminex Corp. (DiaSorin)
- QIAGEN
- Bio-Rad Laboratories
- Fujirebio
- Cue Health
- Ellume
- Genetic Signatures
- Lucira Health
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence & Severity Of Seasonal And Zoonotic Influenza Outbreaks
- 4.2.2 Growing Adoption Of Rapid Point-Of-Care (POC) Tests In Outpatient Settings
- 4.2.3 Government-Funded Surveillance Programs & Pandemic Preparedness Budgets
- 4.2.4 AI-Powered Result-Interpretation Software Boosting Molecular Workflow Throughput
- 4.2.5 Commercialization Of Combo SARS-CoV-2/Flu Multiplex Panels Expanding Installed Base
- 4.2.6 Increasing Integration Of Telehealth With Home-Based Flu Testing Kits
- 4.3 Market Restraints
- 4.3.1 Variable Sensitivity & False-Negative Rate Of RIDTs
- 4.3.2 High Capital & Running Cost Of Molecular Diagnostic Platforms
- 4.3.3 Regulatory Uncertainty For CRISPR-Based Influenza Assays
- 4.3.4 Supply Chain Disruptions Affecting Critical Reagents For PCR Assays
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Test Type
- 5.1.1 Traditional Diagnostic Tests
- 5.1.1.1 Rapid Influenza Diagnostic Tests (RIDTs)
- 5.1.1.2 Direct Fluorescent Antibody (DFA) Tests
- 5.1.1.3 Viral Culture
- 5.1.1.4 Rapid Cell Culture
- 5.1.2 Molecular Diagnostic Tests
- 5.1.2.1 Reverse-Transcriptase PCR (RT-PCR)
- 5.1.2.2 Loop-Mediated Isothermal Amplification (LAMP)
- 5.1.2.3 Nicking-Enzyme Amplification Reaction (NEAR)
- 5.1.2.4 CRISPR-based Assays
- 5.1.2.5 Syndromic Multiplex PCR Panels
- 5.1.1 Traditional Diagnostic Tests
- 5.2 By End User
- 5.2.1 Hospitals & Clinical Laboratories
- 5.2.2 Independent Diagnostic Laboratories
- 5.2.3 Point-of-Care Settings
- 5.2.4 Others
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Italy
- 5.3.2.5 Spain
- 5.3.2.6 Rest of Europe
- 5.3.3 Asia Pacific
- 5.3.3.1 China
- 5.3.3.2 Japan
- 5.3.3.3 India
- 5.3.3.4 South Korea
- 5.3.3.5 Australia
- 5.3.3.6 Rest of Asia Pacific
- 5.3.4 Middle East & Africa
- 5.3.4.1 GCC
- 5.3.4.2 South Africa
- 5.3.4.3 Rest of Middle East & Africa
- 5.3.5 South America
- 5.3.5.1 Brazil
- 5.3.5.2 Argentina
- 5.3.5.3 Rest of South America
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 F. Hoffmann-La Roche AG
- 6.3.2 Abbott Laboratories (incl. ID NOW)
- 6.3.3 QuidelOrtho Corporation
- 6.3.4 Thermo Fisher Scientific (Cepheid, Mesa Bio)
- 6.3.5 Becton, Dickinson & Co.
- 6.3.6 bioMerieux SA
- 6.3.7 Hologic Inc.
- 6.3.8 Siemens Healthineers
- 6.3.9 Danaher Corp. (Cepheid)
- 6.3.10 Sekisui Diagnostics
- 6.3.11 GenMark Diagnostics (Roche)
- 6.3.12 Meridian Bioscience
- 6.3.13 Luminex Corp. (DiaSorin)
- 6.3.14 QIAGEN NV
- 6.3.15 Bio-Rad Laboratories
- 6.3.16 Fujirebio
- 6.3.17 Cue Health
- 6.3.18 Ellume
- 6.3.19 Genetic Signatures
- 6.3.20 Lucira Health