

|
시장보고서
상품코드
2122344
마이크로 가이드 카테터 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Micro Guide Catheter - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
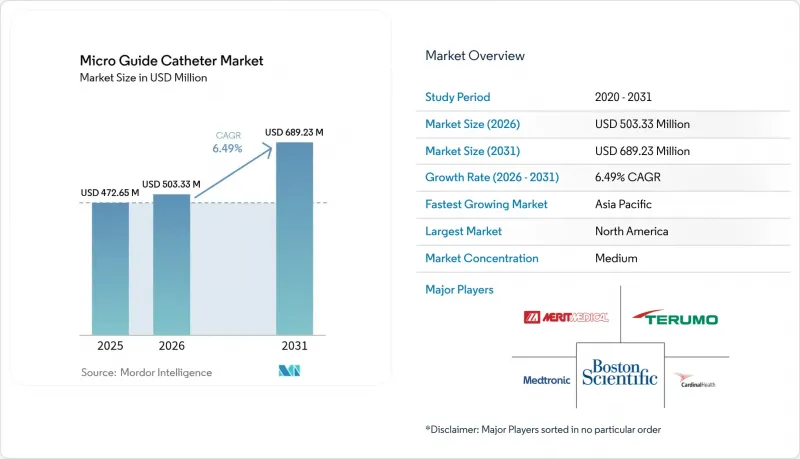
에 의하면, 마이크로 가이드 카테터 시장 규모는 2025년 4억 7,265만 달러로 평가되었고, 2026년에는 5억 333만 달러로 추정되고, 2026-2031년 CAGR 6.49%로 성장을 지속할 전망이며, 2031년에는 6억 8,923만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형별(오버-더-와이어형 마이크로 가이드 카테터, 플로우 디렉티드형 마이크로 가이드 카테터), 용도별(심혈관, 신경혈관, 기타), 최종 사용자별(병원 및 진료소, 외래수술센터(ASC)), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 마이크로 가이드 카테터 시장 동향 및 인사이트
심장 및 신경혈관 질환의 부담 증가
심혈관 질환은 미국에서 연간 4,223억 달러의 직접 비용을 발생시키고 있으며, 생활습관과 관련된 위험 요인과 고령화가 맞물려 그 금액은 계속 증가하고 있습니다. 이와 유사한 경향은 아시아태평양 전체에서도 나타나고 있으며, 홍콩에서는 치료비로 46억 달러, 싱가포르에서는 81억 달러가 지출되고 있어 각국 정부는 중재 치료 프로그램에 대한 지원을 할 수밖에 없는 상황입니다. 뇌졸중 발생률 증가에 따라 카테터 시술 기술을 습득하는 신경과 전문의가 늘어나고 있으며, 현재 다직종으로 구성된 뇌졸중 팀이 마이크로 가이드 카테터의 토크 반응성과 선단의 유연성에 의존하는 혈전 제거술을 사상 최대 건수로 시행하고 있습니다. 이러한 요인들이 복합적으로 작용하여 마이크로 가이드 카테터 시장의 장기적인 수요를 뒷받침하고 있습니다.
저침습적 중재 치료의 보급 확대
의료계에서는 고위험 고령 환자를 대상으로 한 TAVR(경카테터 대동맥판막 교체술) 등 침습성이 낮은 치료법이 선호되고 있습니다. 소구경 대동맥 고리에서 자가 팽창형 판막의 복합 평가 지표는 9.4%였던 반면, 풍선 팽창형 플랫폼에서는 10.6%였습니다. 구조적 심장 질환의 사례 수가 증가함에 따라, 폐쇄 장치의 위치를 최적화하기 위해 정확한 압력 피드백 기능을 갖춘 마이크로 카테터에 대한 수요가 높아지고 있습니다. 컴퓨터 유도형 성형 소프트웨어를 통해 첫 시술 성공률이 34%에서 4%로 낮아졌으며, 이는 투시 시간 단축과 시술자의 피로 경감으로 이어지고 있습니다. 유사한 디지털 도구는 뇌졸중 치료 시스템에도 활용되고 있는데, 이 분야에서는 접근 속도가 신경 기능 회복을 좌우하기 때문에 마이크로 가이드 카테터 시장의 성장에 큰 호재가 되고 있습니다.
고도의 기술을 갖춘 중재 시술 전문의 부족
은퇴하는 심장 전문의 2명당 새로 진입하는 의사는 단 1명에 불과하여, 많은 병원에서 카테터실의 처리 능력이 제한되고 있습니다. 증례의 복잡성은 증가하는 반면 진료 보수는 정체되어 있어, 번아웃 비율이 급증하고 있습니다. 경력 초반의 의사들은 예후가 불량한 사례를 처리할 수밖에 없기 때문에 학습 곡선을 단축하고 자신감을 높일 수 있는 직관적인 카테터의 필요성이 더욱 커지고 있습니다. 지방에서는 이러한 부족 현상이 가장 심각하여, 병원들은 환자를 수백 마일이나 떨어진 곳으로 이송할 수밖에 없으며, 이로 인해 치료가 지연될 뿐만 아니라 의료 서비스가 부족한 지역의 마이크로 가이드 카테터 시장 수요에 부담을 주고 있습니다.
부문 분석
2025년에는 오버 더 와이어(OTW) 구성이 매출의 64.78%를 차지했습니다. 이는 풍선의 장기 팽창이나 스텐트 삽입 시, 그 단계적인 지지 기능이 시술자들에게 계속해서 선호되고 있기 때문입니다. 이 카테고리는 임상 현장에서 확고하게 자리 잡은 친숙함 덕분에 CTO 프로토콜의 중심적인 위치를 계속 차지하고 있지만, 특히 비외상성 원위부 접근을 중시하는 신경혈관 분야에서 플로우 디렉티드 시스템이 연평균 성장률(CAGR) 7.43%로 성장세를 보이고 있습니다. 보스턴 사이언티픽(Boston Scientific)의 ‘Renegade HI-FLO’는 설계상의 진보를 구현한 제품으로, 경쟁 제품에 비해 필요한 힘을 36.8% 줄이고 혈류를 7% 향상시켰습니다. 조향 가능한 샤프트 덕분에 와이어 교체 횟수가 줄어들어, 검사실에서의 형광 투시 및 조영제 사용량을 줄이는 데 도움이 되고 있습니다.
혁신은 와이어와 마이크로 코일의 동시 전달을 가능하게 하는 듀얼 루멘 및 트리플 루멘 구조에 집약되어 있습니다. 고어(Gore)사의 트리플 루멘 설계는 최대 4개의 와이어를 지원하여 페네스트레이션 그래프트 삽입을 간소화합니다. 압력 감지 루멘은 통합적인 생리학적 평가를 약속하지만, 분획 혈류 예비량(FFR)의 정확도 측면에서 전용 와이어보다 0.03 단위 낮은 교정상의 한계가 있어 여전히 틈새 시장 제품에 머물러 있습니다. 수지 공급업체의 생산 능력이 안정화됨에 따라, 각 제조업체는 조작성, 모듈성 및 저프로파일 원위 샤프트를 차세대 제품 라인에 통합하는 것을 목표로 하고 있으며, 이를 통해 마이크로 가이드 카테터 시장은 다목적 하이브리드 제품으로의 전환을 확실히 추진하고 있습니다.
지역별 분석
북미는 종합적인 보험 적용 범위, 높은 검사실 밀도, 정밀 내비게이션 기능의 급속한 보급을 배경으로 2025년 매출의 42.30%를 차지했습니다. 미국의 의료진은 연간 50만 건 이상의 PCI(경피적 관상동맥 성형술)를 시행하고 있으며, 그중 29%는 CTO(완전 폐색) 치료 기술을 활용한 사례로, 이로 인해 마이크로카테터의 삽입 성공률이 향상되고 있습니다. 캐나다에서는 지역 병원이 복잡한 사례를 대학 병원으로 의뢰하는 ‘허브 앤 스포크(hub-and-spoke)’ 방식이 채택되어, 이에 따라 국내 의료기기 사용량이 증가하고 있습니다. 압력 감지 카테터의 보험 환급 조건은 여전히 유리하며, CMS(미국 의료보험센터)는 외래 진료 청구서에 기록된 경우 1회 사용당 989달러의 추가 지급을 인정하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.33%를 나타낼 것으로 예측되며, 마이크로 가이드 카테터 시장의 추가 성장을 견인할 중요한 지역이 될 것입니다. 중국에서는 매년 250개 이상의 카테터실이 개설되고 있으며, 수량 기준의 조달 입찰로 인해 국내 기업들은 상품 가격의 상한선을 피하기 위해 조종 가능한 원위부 끝부분과 같은 차별화된 틈새 시장으로 진출하고 있습니다. 다음으로, 국민건강보험 제도를 갖춘 고령화 사회인 일본이 부상하고 있습니다. 일본에서는 새로운 신경 혈전 제거 도구에 대한 중립적인 보험 급여 제도가 조기 도입을 가속화하고 있습니다. 베트남 등 동남아시아 국가들은 첨단 마이크로 가이드 카테텔의 경우 수입에 의존하고 있지만, 의료기기 성장률은 두 자릿수를 기록하고 있습니다. 2021-2024년 현지 임상시험 참여가 65% 증가했으며, 국내 승인 획득이 가속화되고 있습니다.
유럽에서는 독일, 프랑스, 영국이 주도하여 안정적인 10%대 중반의 성장이 예상됩니다. EU 의료기기 규정(MDR)은 승인 주기를 장기화시키지만, 안전성에 대한 평가를 높여 임상의들의 신뢰를 뒷받침하고 있습니다. 라틴아메리카에서는 지불 주체의 구성이 분산되어 있어 판매량은 제한적이지만, 브라질의 5,900만 달러 규모의 혈관용 의료기기 시장은 사립 병원을 타겟으로 한 고급 카테터에 대한 발판이 되고 있습니다. 사우디아라비아 등 중동의 주요 국가들은 ‘비전 2030’의 일환으로 심장 질환 치료 전문센터에 투자하고 있으며, 영상 진단 장비와 일회용 제품을 세트로 묶은 조달 계약이 체결되는 경우가 늘고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the micro guide catheters market size is expected to grow from USD 472.65 million in 2025 to USD 503.33 million in 2026 and is forecast to reach USD 689.23 million by 2031 at 6.49% CAGR over 2026-2031.
This report is Segmented by Product Type (Over-The-Wire Micro Guide Catheters, Flow-Directed Micro Guide Catheters), Application (Cardiovascular, Neurovascular, Others), End User (Hospitals & Clinics, Ambulatory Surgical Centers), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Micro Guide Catheter Market Trends and Insights
Growing Burden Of Cardiac & Neurovascular Disorders
Cardiovascular disease imposes USD 422.3 billion in direct costs annually on the United States and continues to rise as lifestyle risk factors intersect with aging demographics. The same pattern is unfolding across Asia-Pacific, where Hong Kong spends USD 4.6 billion and Singapore USD 8.1 billion on treatment, prompting governments to subsidize interventional programs. Increasing stroke incidence means more neurologists are training in catheter skills, and multi-disciplinary stroke teams now perform a record number of thrombectomies that depend on micro guide catheter torque response and tip flexibility. Together, these factors sustain long-run demand in the micro guide catheters market.
Rising Adoption Of Minimally-Invasive Interventions
The clinical community favors less invasive solutions such as TAVR for high-risk elderly patients; self-expanding valves posted a 9.4% combined endpoint versus 10.6% for balloon-expandable platforms in small annuli. Higher volumes of structural heart cases require microcatheters with precise pressure feedback to optimize closure device positioning. Computer-guided shaping software lowers first-pass failure from 34% to 4%, trimming fluoroscopy seconds and operator fatigue. The same digital tools inform stroke systems, where speed of access dictates neurological function, thus creating a meaningful tail-wind for micro guide catheters market growth.
Shortage Of Highly-Skilled Interventional Specialists
Only one new cardiologist enters the workforce for every two that retire, limiting lab throughput in many hospitals . Burnout rates have escalated because reimbursement stagnates while case complexity rises. Early-career physicians contend with higher predicted mortality caseloads, reinforcing the need for intuitive catheters that shorten learning curves and improve confidence. Rural regions feel the shortfall most; hospitals ship patients hundreds of miles, delaying treatment and compressing demand for micro guide catheters market devices in underserved areas.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Geriatric Patient Pool Worldwide
- Surge In CTO-PCI Driving Demand For Dual-/Locking Microcatheters
- Supply-Chain Volatility For High-Performance Polymers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Over-the-wire configurations held 64.78% of revenue in 2025 as operators continue to favor their incremental support during prolonged balloon inflations and stent delivery. This category's entrenched clinical familiarity keeps it at the center of CTO protocols, yet flow-directed systems are picking up pace at a 7.43% CAGR, particularly in neurovascular circles that value atraumatic distal access. Boston Scientific's Renegade HI-FLO exemplifies design gains, posting 36.8% lower force and 7% higher flow than peers . Steerable shafts reduce wire exchanges, helping labs trim fluoroscopy and contrast.
Innovation converges on dual-lumen and tri-lumen form factors that facilitate simultaneous wire or microcoil delivery. Gore's tri-lumen design handles up to four wires, simplifying fenestrated graft placement. Pressure-sensing lumens promise integrated physiological assessment but remain niche due to calibration limits that trail dedicated wires by 0.03 units in fractional-flow reserve accuracy. As resin suppliers stabilize capacity, manufacturers aim to merge steerability, modularity, and low-profile distal shafts into next-gen lines, ensuring the micro guide catheters market continues its shift toward versatile hybrids.
Complete Report Scope:
- By Product Type
- Over-the-wire Micro Guide Catheters
- Flow-directed Micro Guide Catheters
- By Application
- Cardiovascular
- Neurovascular
- Others
- By End User
- Hospitals & Clinics
- Ambulatory Surgical Centers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America anchors 42.30% of 2025 revenue on the strength of comprehensive insurance coverage, high lab density, and rapid adoption of precision navigation features. U.S. operators perform more than 500,000 PCI cases annually, with 29% involving CTO techniques that elevate microcatheter pull-through rates. Canada adopts a hub-and-spoke approach where community hospitals send complex patients to academic centers, increasing national device turnover. Reimbursement for pressure-sensing catheters remains favorable, with CMS paying an extra USD 989 per use when documented in outpatient claims.
Asia-Pacific, projected at an 8.33% CAGR through 2031, will be the swing territory for incremental gains in the micro guide catheters market. China opens more than 250 cath labs each year, and its volume-based-procurement tenders push domestic firms toward differentiated niches like steerable distal tips to escape commodity price ceilings. Japan advances next as an aging society with universal coverage; its neutral reimbursement for novel neuro thrombectomy tools accelerates early adoption. Southeast Asian economies such as Vietnam log double-digit medical device growth rates, though they rely on imports for sophisticated micro guide catheters. Local clinical trial participation increased 65% between 2021 and 2024, enabling faster in-country registrations.
Europe presents stable mid-single-digit expansion fueled by Germany, France, and the UK. The EU Medical Device Regulation (MDR) lengthens approval cycles but raises perceived safety, supporting clinician confidence. Latin America's fragmented payer mix tempers volume, yet Brazil's USD 59 million vascular device market sets a foothold for premium catheters targeting private hospitals. Middle East hubs like Saudi Arabia invest in cardiac centers of excellence within Vision 2030, creating procurement contracts that often bundle imaging hardware with disposables.
- Boston Scientific
- Terumo
- Medtronic
- Asahi Intecc
- Merit Medical Systems
- Cook Group
- Cardinal Health
- Teleflex
- Integer Holdings
- Stryker
- Abbott Laboratories
- Johnson & Johnson (Cordis)
- Penumbra
- AngioDynamics
- MicroPort Scientific Corp.
- Becton Dickinson & Co.
- Lepu Medical
- Acandis
- Oscor
- iVascular S.L.U.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Burden Of Cardiac & Neurovascular Disorders
- 4.2.2 Rising Adoption Of Minimally-Invasive Interventions
- 4.2.3 Expanding Geriatric Patient Pool Worldwide
- 4.2.4 Surge In CTO-PCI Driving Demand For Dual-/Locking Microcatheters
- 4.2.5 Rapid Innovation In Steerable & Pressure-Sensing Microcatheters
- 4.2.6 Expansion Of High-Volume Ambulatory Cath Labs In Ems
- 4.3 Market Restraints
- 4.3.1 Shortage Of Highly-Skilled Interventional Specialists
- 4.3.2 Product Recalls & Stringent Post-Market Surveillance
- 4.3.3 Accuracy Concerns In FFR When Using Microcatheters
- 4.3.4 Supply-Chain Volatility For High-Performance Polymers
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Over-the-wire Micro Guide Catheters
- 5.1.2 Flow-directed Micro Guide Catheters
- 5.2 By Application
- 5.2.1 Cardiovascular
- 5.2.2 Neurovascular
- 5.2.3 Others
- 5.3 By End User
- 5.3.1 Hospitals & Clinics
- 5.3.2 Ambulatory Surgical Centers
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Boston Scientific Corporation
- 6.3.2 Terumo Corporation
- 6.3.3 Medtronic plc
- 6.3.4 Asahi Intecc Co. Ltd
- 6.3.5 Merit Medical Systems Inc.
- 6.3.6 Cook Group Incorporated
- 6.3.7 Cardinal Health Inc.
- 6.3.8 Teleflex Incorporated
- 6.3.9 Integer Holdings Corporation
- 6.3.10 Stryker Corporation
- 6.3.11 Abbott Laboratories
- 6.3.12 Johnson & Johnson (Cordis)
- 6.3.13 Penumbra Inc.
- 6.3.14 AngioDynamics Inc.
- 6.3.15 MicroPort Scientific Corp.
- 6.3.16 Becton Dickinson & Co.
- 6.3.17 Lepu Medical Technology
- 6.3.18 Acandis GmbH
- 6.3.19 Oscor Inc.
- 6.3.20 iVascular S.L.U.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


