

|
시장보고서
상품코드
2123379
혈관 가이드와이어 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Vascular Guidewires - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 혈관 가이드와이어 시장 규모는 2025년 16억 1,000만 달러에서 2026년에는 17억 2,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 6.66%로 성장을 지속하여, 2031년에는 23억 7,000만 달러에 이를 것으로 예측됩니다.
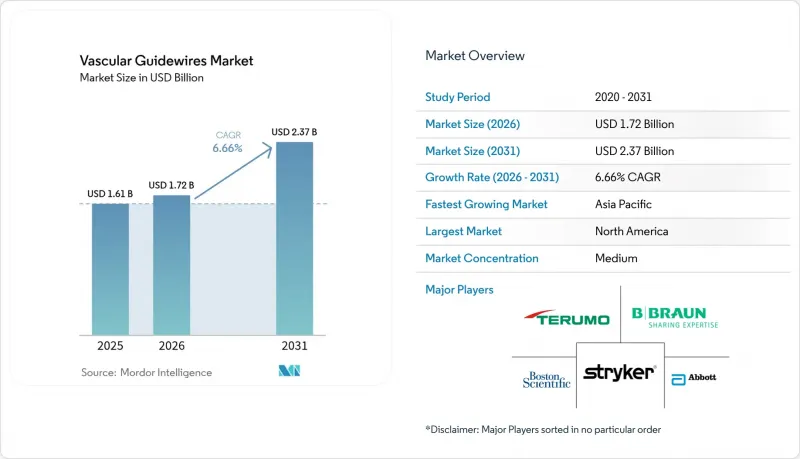
본 보고서는 제품(말초혈관 가이드와이어, 관상동맥용 가이드와이어 등), 코팅(코팅 처리된 제품, 코팅되지 않은 제품), 원재료(니티놀, 스테인리스 스틸, 기타), 최종 사용자(병원, 외래수술센터(ASC) 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 혈관 가이드와이어 시장 동향 및 인사이트
심혈관 질환 부담 증가
세계 고혈압 유병률은 2020년 51.2%에서 2050년까지 61.0%로 상승할 것으로 예측되며, 당뇨병 유병률도 16.3%에서 26.8%로 상승할 것으로 전망됩니다. 이러한 역학적 변화로 인해 관상동맥, 말초혈관 및 신경혈관 중재 시술 건수가 증가함에 따라, 가이드와이어는 필수적인 접근 도구로서의 입지를 확고히 하고 있습니다. 뇌졸중 관련 비용만 해도 2050년까지 535% 증가하여 4,230억 달러에 달할 것으로 예측되며, 이는 신경혈관 기기에 대한 장기적인 수요를 뒷받침하고 있습니다. 병원 시스템에서는 카테터실의 수용 능력을 확대하는 동시에, 고령 환자의 복잡한 해부학적 구조에 대응할 수 있는 토크 반응형 가이드와이어의 도입이 진행되고 있습니다. 또한, 예방적 중재도 확산되고 있어 혈관 가이드와이어의 전체 시장 규모가 확대되고 있습니다.
저침습 수술에 대한 선호도 증가
2028년까지 외래수술센터(ASC)가 미국 외래 수술의 절반 이상을 담당할 것으로 예상되며, 이는 연평균 성장률(CAGR) 6.9%로 330억 달러 규모 시장 기회를 의미합니다. 현재 경피적 관상동맥 중재술(PCI) 중 ASC에서 시행되는 비율은 1.8%에 불과하여 성장 여지가 남아 있습니다. 비용 절감, 빠른 회복, 그리고 동등한 안전성 실적을 바탕으로 보험사 및 의료 제공업체들은 외래 혈관 내 시술을 선호하게 되었으며, 그 결과 모든 시술 환경에서 확실하게 작동하는 범용성 높은 가이드와이어에 대한 수요가 증가하고 있습니다.
제품 리콜 및 FDA 경고장 발부 건수 증가
2024년부터 2025년까지 코팅 박리 등의 사건을 포함한 클래스 I 리콜이 주요 제조업체와 수십만 대의 의료기기에 영향을 미쳤습니다. 규제 환경이 엄격해짐에 따라 의료 기관은 공급업체 다각화를 추진하는 한편, 제조업체는 시장의 신뢰를 유지하기 위해 품질 관리를 강화하고 있습니다.
부문 분석
2025년, 관상동맥용 가이드와이어는 전 세계 PCI 시술 건수가 많음에 따라 혈관 가이드와이어 시장에서 46.02%의 점유율을 차지했습니다. 신경혈관 가이드와이어는 매출 규모는 작지만, 뇌졸중에 대한 인식 제고와 원위부 접근 장치의 개선을 반영하여 연평균 성장률(CAGR) 8.14%를 나타낼 것으로 예측됩니다. 첨단 하이브리드 와이어는 부드러운 선단부와 근위부의 강성을 결합하여 여러 번의 와이어 교체에 대한 의존도를 낮추고, 임상의의 선호도에 영향을 미치고 있습니다. 인공지능(AI) 통합도 검토되고 있으며, 향후 실시간 혈관 매핑이 가능한 스마트 가이드와이어가 등장할 것으로 예측됩니다.
말초 혈관 부문은 말초 동맥 질환의 발생률 증가에 힘입어 안정적인 성장을 이어가고 있습니다. 비뇨기과용 가이드와이어는 저침습적 결석 치료로의 광범위한 전환의 혜택을 받고 있지만, 심혈관 용도와 비교하면 여전히 틈새 시장에 머물러 있습니다.
2025년에는 코팅된 가이드와이어가 혈관 가이드와이어 시장 규모의 62.48%를 차지했습니다. 이는 친수성 층이 굴곡진 해부학적 구조에서 미끄러짐을 개선하기 때문입니다. PFAS(퍼플루오로알킬 물질)에 대한 규제 당국의 감시가 강화됨에 따라 대체 화학 물질에 대한 연구 개발이 가속화되고 있으며, 각 제조업체는 불소를 포함하지 않는 코팅 및 생분해성 코팅에 관한 새로운 특허를 출원하고 있습니다. 비코팅 가이드와이어는 연평균 성장률(CAGR) 7.69%로 성장하고 있습니다. 이는 특정 관상동맥 및 말초혈관 사례에서 시술자가 직접적인 촉각 피드백을 중요시하고 있으며, 가격에 민감한 시장이 프리미엄 코팅의 이점을 재평가하고 있기 때문입니다.
지역별 분석
북미는 2025년에도 매출 점유율 44.88%를 유지했습니다. 탄탄한 보험 환급 제도, 로봇 플랫폼의 조기 도입, 그리고 광범위한 임상 교육 네트워크가 수요를 뒷받침하고 있습니다. 그러나 FDA의 시판 후 감시가 강화됨에 따라 승인 주기가 길어지고, 규정 준수 비용이 증가하고 있습니다. 가치 기반 의료 계약에서는 치료 성과에 대한 증거가 점점 더 요구되고 있어, 공급업체들은 의료기기의 성능과 총 의료비를 연계해야 한다는 압력을 받고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.47%를 나타낼 것으로 예측됩니다. 2029년까지 556억 7,000만 달러에 달할 것으로 예상되는 중국의 의료기기 시장은 ‘중국 제조 2025’ 등 국내 생산을 촉진하는 정책의 혜택을 받고 있습니다. 인도네시아는 2024년에 23억 달러에 도달할 전망이며, 현지 조달률(TKDN)을 의무화하는 규정을 계속해서 활용하고 있습니다. 인도의 새로운 판매 행동 강령은 투명성을 높이고 있지만, 다국적 공급업체에게는 단기적인 조정이 필요하게 되었습니다. 수술 건수 증가, 보험 적용 범위 확대, 그리고 심혈관 의료에 대한 정부 투자로 인해 이 지역은 혈관 가이드와이어 시장 매출 증가의 주요 원동력으로서의 입지를 확고히 하고 있습니다.
유럽에서는 엄격한 규제 체계 속에서도 안정적인 수요가 나타나고 있습니다. 2024년에 개정된 조화 표준에 따라 CE 마크 획득 절차는 더욱 명확해졌으나, 반면 서류 제출 요건은 더욱 엄격해졌습니다. 유럽 대륙의 고령화로 인해 시술 건수는 높은 수준을 유지하고 있으며, 비용 대비 효과 평가에 따라 성능과 경제적 가치의 균형을 갖춘 가이드와이어의 채택이 촉진되고 있습니다. 브렉시트로 인한 규제 차이는 여전히 영국과 EU 간공급 물류를 복잡하게 만들고 있지만, 상호 인정 협정을 통해 점차 완화되고 있습니다.
중동 및 아프리카 및 남미에서는 새로운 가능성이 나타나고 있습니다. 걸프협력회의(GCC) 회원국들은 심혈관 질환 전문 의료 센터에 대한 투자를 추진하고 있는 반면, 브라질과 아르헨티나에서는 보험 환급의 장벽이 있음에도 불구하고 카테터실 네트워크 확장이 진행되고 있습니다. 시장 진입은 유통업체와의 제휴 및 끊임없이 변화하는 현지 규정의 준수에 크게 좌우됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the vascular guidewires market size is expected to grow from USD 1.61 billion in 2025 to USD 1.72 billion in 2026 and is forecast to reach USD 2.37 billion by 2031 at 6.66% CAGR over 2026-2031.
This report is Segmented by Product (Peripheral Guidewires, Coronary Guidewires, and More), Coating (Coated, Non-Coated), Raw Material (Nitinol, Stainless Steel, Other Materials), End User (Hospitals, Ambulatory Surgical Centres, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Vascular Guidewires Market Trends and Insights
Rising Cardiovascular Disease Burden
Global hypertension prevalence is forecast to climb from 51.2% in 2020 to 61.0% by 2050, while diabetes rises from 16.3% to 26.8%. These epidemiological shifts elevate procedure volumes for coronary, peripheral, and neurovascular interventions, positioning guidewires as essential access tools. Stroke-related costs alone are anticipated to increase 535% to USD 423 billion by 2050, underscoring long-term demand for neurovascular devices. Hospital systems are expanding cath-lab capacity and procuring torque-responsive wires that address complex anatomy in older patients. Preventive interventions are also gaining traction, enlarging the overall addressable vascular guidewires market .
Growing Preference for Minimally Invasive Surgeries
Ambulatory surgical centers (ASCs) are expected to handle more than half of US outpatient surgeries by 2028, representing a USD 33 billion opportunity at a 6.9% CAGR. Only 1.8% of percutaneous coronary interventions currently occur in ASCs, leaving headroom for growth. Cost savings, faster recovery, and comparable safety records are compelling payers and providers to favor outpatient endovascular care, thereby increasing demand for versatile guidewires that perform reliably across procedural settings.
Rising Incidence of Product Recalls & FDA Warning Letters
Class I recalls in 2024-2025, including coating separation events, have affected leading manufacturers and hundreds of thousands of devices. The heightened regulatory environment is prompting providers to diversify suppliers, while manufacturers strengthen quality controls to preserve market confidence.
Other drivers and restraints analyzed in the detailed report include:
- Technological Breakthroughs in Steerable & Torque-Enhanced Wires
- Ageing Population Expanding Interventional Case-Load
- Hospital Adoption of Robotic-Assisted Endovascular Suites
- Price Erosion Amid Commoditization in Mature Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Coronary guidewires held a 46.02% share of the vascular guidewires market in 2025 owing to high global PCI volumes. Neurovascular guidewires, though smaller in revenue, are forecast for an 8.14% CAGR, reflecting rising stroke awareness and improvements in distal access devices. Advanced hybrid wires are influencing clinician preferences by combining soft tips with proximal stiffness, reducing reliance on multiple wire exchanges. Artificial intelligence integration is under exploration, pointing to future smart guidewires capable of real-time vessel mapping.
The peripheral segment continues stable growth fuelled by increasing peripheral artery disease incidence. Urology guidewires benefit from the broader shift toward minimally invasive stone management, although they remain niche compared with cardiovascular applications.
Coated guidewires represented 62.48% of vascular guidewires market size in 2025 as hydrophilic layers improve lubricity in tortuous anatomy. PFAS-related regulatory scrutiny is accelerating R&D into alternative chemistries, prompting manufacturers to file new patents for fluorine-free or biodegradable coatings. Non-coated guidewires are expanding at a 7.69% CAGR as operators value direct tactile feedback in certain coronary and peripheral cases, and as price-sensitive markets re-evaluate premium coating benefits.
Complete Report Scope:
- By Product
- Peripheral Guidewires
- Coronary Guidewires
- Urology Guidewires
- Neurovascular Guidewires
- By Coating
- Coated
- Non-Coated
- By Raw Material
- Nitinol
- Stainless Steel
- Other Materials (PEEK, Polymer Hybrids)
- By End User
- Hospitals
- Ambulatory Surgical Centres
- Specialty Clinics & Cath Labs
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained a 44.88% revenue share in 2025. Robust reimbursement, early adoption of robotic platforms, and broad clinical training networks sustain demand. However, stricter FDA post-market surveillance is lengthening approval cycles and raising compliance costs. Value-based care contracts increasingly require outcome evidence, pressuring suppliers to link device performance with total cost of care.
Asia-Pacific is projected for an 8.47% CAGR through 2031. China's device market, targeted to reach USD 55.67 billion by 2029, benefits from policies such as Made in China 2025 that foster domestic production. Indonesia reached USD 2.3 billion in 2024 and continues to leverage TKDN rules that mandate local content. India's new marketing conduct codes are improving transparency, though they require short-term adjustments for multinational suppliers. Rising procedure volumes, expanding insurance coverage, and government investments in cardiovascular care position the region as the key driver for incremental vascular guidewires market revenue.
Europe exhibits steady demand amid rigorous regulatory frameworks. Harmonized standards updated in 2024 introduce clearer pathways for CE marking, albeit with higher documentation requirements . The continent's aging demographic keeps procedure numbers high, while cost-effectiveness evaluations encourage adoption of guidewires that balance performance with economic value. Brexit-induced divergence still complicates UK-EU supply logistics but is gradually being mitigated through mutual recognition agreements.
Middle East & Africa and South America show emerging potential. Gulf Cooperation Council countries invest in cardiovascular centers of excellence, whereas Brazil and Argentina expand cath-lab networks despite reimbursement hurdles. Market access relies heavily on distributor partnerships and compliance with evolving local regulations.
- Boston Scientific
- Abbott Laboratories
- Terumo
- Asahi Intecc
- Medtronic
- Cardinal Health
- B. Braun
- AngioDynamics
- Stryker
- Cook Group
- Integer Holdings
- Lepu Medical
- FMD Co. Ltd
- Teleflex
- Merit Medical Systems
- Cordis (Hellman & Friedman)
- Penumbra
- MicroPort
- Nipro
- Bentley InnoMed GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Cardiovascular Disease Burden
- 4.2.2 Growing Preference For Minimally-Invasive Surgeries
- 4.2.3 Technological Breakthroughs In Steerable & Torque-Enhanced Wires
- 4.2.4 Ageing Population Expanding Interventional Case-Load
- 4.2.5 Hospital Adoption Of Robotic-Assisted Endovascular Suites
- 4.2.6 Supply-Chain Localisation Of Medical-Grade Nitinol
- 4.3 Market Restraints
- 4.3.1 Rising Incidence Of Product Recalls & Fda Warning Letters
- 4.3.2 Price Erosion Amid Commoditisation In Mature Markets
- 4.3.3 Global Nitinol Feedstock Shortages
- 4.3.4 PFAS-Linked Regulation Of Hydrophilic Coatings
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Peripheral Guidewires
- 5.1.2 Coronary Guidewires
- 5.1.3 Urology Guidewires
- 5.1.4 Neurovascular Guidewires
- 5.2 By Coating
- 5.2.1 Coated
- 5.2.2 Non-Coated
- 5.3 By Raw Material
- 5.3.1 Nitinol
- 5.3.2 Stainless Steel
- 5.3.3 Other Materials (PEEK, Polymer Hybrids)
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centres
- 5.4.3 Specialty Clinics & Cath Labs
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Boston Scientific Corporation
- 6.3.2 Abbott Laboratories
- 6.3.3 Terumo Corporation
- 6.3.4 Asahi Intecc Co. Ltd
- 6.3.5 Medtronic plc
- 6.3.6 Cardinal Health
- 6.3.7 B. Braun Melsungen AG
- 6.3.8 AngioDynamics
- 6.3.9 Stryker Corporation
- 6.3.10 Cook Medical
- 6.3.11 Integer Holdings Corporation
- 6.3.12 Lepu Medical Technology
- 6.3.13 FMD Co. Ltd
- 6.3.14 Teleflex Incorporated
- 6.3.15 Merit Medical Systems
- 6.3.16 Cordis (Hellman & Friedman)
- 6.3.17 Penumbra Inc.
- 6.3.18 MicroPort Scientific
- 6.3.19 Nipro Corporation
- 6.3.20 Bentley InnoMed GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


