|
시장보고서
상품코드
2122389
공기청정기 : 시장 점유율 분석, 산업 동향·통계 데이터, 성장 예측(2026-2031년)Air Purifier - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
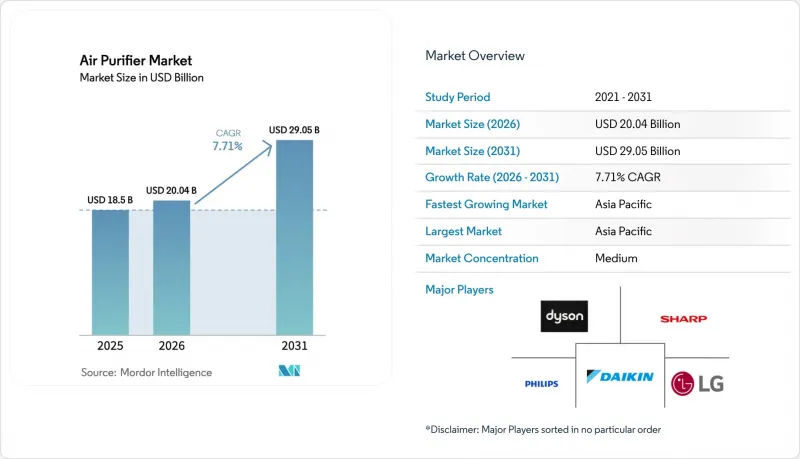
에 따르면 공기청정기 시장은 2025년 185억 달러에서 2026년에는 200억 4,000만 달러로 확대하며, 2026-2031년에 CAGR 7.71%로 추이하며, 2031년에는 290억 5,000만 달러에 달할 것으로 예측됩니다.
이 보고서는 여과 기술(HEPA, 활성탄, 이온/정전기 집진 장치, UV-C·광촉매 산화, 하이브리드·다단식 시스템), 유형(독립형, 덕트 내장형), 연결 기능(비스마트형, 스마트/IoT 대응형), 최종사용자(가정용, 상업용, 산업용) 및 지역(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)별로 분류되어 있습니다.
전 세계 공기청정기 시장 동향 및 인사이트
동아시아 대도시에서 COVID-19 팬데믹 이후 건강 지향적 기기의 보급
베이징, 서울, 도쿄에서는 PM2.5 측정치가 국가 목표치를 초과하는 상태가 지속되고 있으며, 이로 인해 연중 내내 공기청정기 소유가 정착되면서 공기청정기 시장은 팬데믹 당시의 급증기를 넘어 계속 확대되고 있습니다. 중국 생태환경부는 2024년에 모니터링 대상이었던 168개 도시 중 38개 도시가 PM2.5 목표를 달성하지 못했음을 확인했습니다. 일본 후생노동성은 2024년에 실내 공기질 가이드라인을 개정하여, 보육 시설 및 노인 요양 시설에서의 HEPA 필터 사용을 권장함으로써 필터 교체 주기를 제도화했습니다. 한국에서는 초청정 팹에서 근무하는 반도체 엔지니어들이 직장 기준을 자택에도 반영하려는 경향이 강해지면서, 고급 주택을 찾는 계층이 형성되고 있습니다. 샤오미는 2025년에 우한에 25억 위안 규모의 스마트 가전 공장을 개설하여, 내수 및 수출 주문에 따라 유연하게 조정 가능한 연간 700만 대의 생산 능력을 추가했습니다. 이러한 규제에 따른 지원과 소비자의 수요가 맞물려, 동아시아의 안정적인 수요 기반이 확고해지고 있습니다.
북미 지역의 PM2.5 관련 상업용 부동산 기준 강화(LEED v4.1)
LEED v4.1의 ‘실내 환경 품질’ 크레딧에서는 MERV 13 이상의 필터와 PM2.5의 지속적인 모니터링이 의무화되어 있으며, 미국 및 캐나다의 건물 소유주는 개보수를 실시하거나 설계 단계부터 첨단 정화 시스템을 사양서에 반영해야만 합니다. 10만 제곱피트 규모의 사무실에서 규정 준수 예산은 5만 달러에서 15만 달러에 달하지만, 임차인들이 인재 확보 및 ESG 보고를 위해 건강한 건물 인증을 요구함에 따라 이러한 투자의 정당성은 점점 더 높아지고 있습니다. ASHRAE 62.1-2022에서는 외기 환기율이 더욱 엄격해졌으며, 덕트내 HEPA 모듈과 회의 공간용 휴대용 장치를 결합한 하이브리드 솔루션이 권장되고 있습니다. 캐나다 그린 빌딩 협의회에 따르면 2025년에는 신규 상업 프로젝트의 68%가 LEED 인증을 획득할 것으로 예상되며, 이는 이 기준이 주류로 자리 잡을 조짐을 보여줍니다. 2027년까지 ‘건물의 에너지 성능에 관한 지침’ 개정을 통해 실내 공기질 지표가 포함됨에 따라 이러한 기준은 유럽으로도 확산될 전망입니다.
캘리포니아주 및 일본의 이온화기 오존 배출 규제
캘리포니아주 대기자원국은 2024년, 실내용 공기청정기에서 배출되는 오존량을 0.050 ppm으로 제한함으로써 사실상 이온화 기술을 핵심으로 하는 설계를 배제했습니다. 일본 후생노동성도 2025년에 유사한 표시 규정을 시행하여, 보육 시설내 이온 발생 장치의 판매를 제한했습니다. 샤프나 파나소닉 등 이온화 기술에 의존하는 브랜드들은 기준을 충족하기 위해 대당 15-25달러의 재설계 비용을 부담하게 되어, 엔트리 부문에서의 이익률이 압박받고 있습니다. 이러한 규제 변경으로 인해 수요는 HEPA 필터만 탑재한 제품이나 하이브리드형 제품으로 이동하고 있으며, 이는 이온 발생 장치를 탑재하지 않은 경쟁사들에게 혜택을 주고 있습니다.
부문 분석
HEPA 필터는 2025년 공기청정기 시장 점유율의 68.1%를 차지했으며, 0.3µm에서 99.97%의 포집 효율과 미국 환경보호청(EPA) 및 세계보건기구(WHO)의 권장 사항이 높이 평가받았습니다. HEPA에 활성탄, UV-C 또는 광촉매 산화를 결합한 하이브리드 구성은 가정과 기업이 단일 기기로 VOC, 병원체, 악취 제거를 목표로 하게 됨에 따라 연평균 성장률(CAGR) 9.3%를 기록할 것으로 전망됩니다. 다이킨의 ‘스트리머’ 플라즈마 모듈은 2024년 실험실 테스트에서 SARS-CoV-2를 99.9% 불활성화시키는 것으로 나타났습니다. 파나소닉의 ‘nanoe X’ 하이드록실 라디칼 발생 장치는 입자 포집과 마찬가지로 병원체 제어가 중시되는 일본의 노인 돌봄 시장에서 인기를 끌고 있습니다. 한편, 캘리포니아주와 일본에서 오존 배출 규제가 강화됨에 따라 이온 집진기는 틈새 산업 용도로 전환되고 있습니다. 그러나 하이브리드 유닛에 대한 통일된 성능 기준이 부족하여, 위험 회피 성향이 강한 병원이나 제약 공장에서의 도입은 주춤하고 있습니다.
하이브리드 시스템은 스마트 센서 어레이와 연동하여 단계에 따라 여과 방식을 자동으로 전환함으로써 에너지 소비를 억제하고 필터의 수명을 연장합니다. LG의 ‘클린 부스터’ 와류 기류는 기존 원심 팬에 비해 CADR을 47% 향상시켰으며, 더 컴팩트한 본체로 동등한 실내 커버 범위를 실현하고 있습니다. UV-C 및 광촉매 모듈은 대당 80-120달러에 달하는 고가의 옵션 기능으로 남아 있으므로 500달러 이하 가격대의 제품으로의 보급은 제한적입니다. UV-C 노출에 관한 향후 규제가 경쟁 환경을 더욱 형성할 가능성이 있지만, 현재로서는 전 세계적인 합의가 존재하지 않습니다.
2025년 공기청정기 시장에서 독립형 기기가 시장 규모의 79.5%를 차지했습니다. 이는 임차인이나 주택 소유자들이 150-800달러 가격대의 ‘플러그 앤 플레이’형 솔루션을 선호했기 때문입니다. 그럼에도 불구하고 덕트내 설치형은 2031년까지 연평균 성장률(CAGR) 8.8%로 확대되고 있으며, 특히 중앙 집중식 유지 관리를 선호하는 상업 시설에서 이러한 경향이 두드러집니다. 2만-4만 달러의 비용이 드는 덕트내 HEPA 필터 개조 1건만으로도 5만 제곱피트 규모의 사무실에서 LEED 환기 횟수 요건을 충족할 수 있습니다. 반면, 휴대용 기기로 동등한 커버리지를 확보하려면 50대가 필요하며, 필터 교체를 위한 지속적인 인건비도 발생합니다. 삼성은 2025년에 FlaktGroup을 인수하여 병원 및 공항을 대상으로 하는 정화 모듈 분야로 HVAC 사업의 범위를 확대했습니다. 데이터센터 운영사는 부유 입자 농도를 10µg/m³ 미만으로 유지하기 위해 덕트내 시스템을 채택하고 있으며, 이를 통해 고밀도 서버의 과열 및 단락을 방지하고 있습니다. 반면, 숙박 시설이나 공동 주택에서는 개별 방별 제어와 외관의 미관이 운영상의 통합보다 더 중요시되므로 휴대용 유닛이 여전히 주류를 이루고 있습니다.
지역별 HVAC 보급 현황이 이러한 동향을 형성하고 있습니다. 북미와 유럽에서는 상업용 빌딩의 중앙 공조 도입률이 약 85%에 달하여, 당연히 덕트내 솔루션으로의 전환이 진행되고 있습니다. 대조적으로 아시아태평양에서는 건축물의 구성이 다양하므로 휴대용에 대한 수요가 유지되고 있습니다. 다만, 베이징, 서울, 싱가포르에서는 신축 A급 오피스에서 필터용 플레넘 공간을 내장한 설계가 점점 늘어나고 있습니다. 휴대용과 덕트내 설치형 모두를 제공할 수 있는 공급업체는 고장시 교체부터 신축 건물의 설계 사양에 이르기까지 프로젝트의 전체 수명 주기에 대응할 수 있는 입장에 있습니다.
지역별 분석
아시아태평양은 2025년 공기청정기 시장 매출의 42.9%를 차지하며, 도시 지역의 PM2.5 농도가 지속적으로 높은 수준을 유지하고 있는 점,반도체 분야에 대한 적극적인 투자, 그리고 정부의 대기 정화 프로그램을 배경으로 2031년까지 연평균 성장률(CAGR) 8.5%로 성장할 것으로 전망됩니다. 중국 환경보호부는 2024년, 대기질 기준을 달성하지 못한 도시가 38곳에 달한다고 보고했으며, 이는 안정적인 가정용 수요의 기반이 되고 있습니다. 샤오미의 우한 공장은 연간 생산 능력을 700만 대 늘려 현지 비용 면에서의 우위를 강화하고 있습니다. 일본의 보육 시설용 실내 공기질(IAQ) 지침 개정에 따라 HEPA 필터 설치가 촉진되어 안정적인 교체 주기가 형성되고 있습니다.
북미는 판매 대수는 적지만, LEED v4.1, ASHRAE 62.1 및 CHIPS법에 따른 자금이 결합되어 정책 주도형으로 가장 빠른 성장을 보이고 있습니다. 애리조나주, 텍사스주, 오하이오주에서 건설 중인 반도체 팹에서는 HEPA/ULPA 인프라가 필수로 요구되고 있으며, 이는 B2B 분야의 대규모 수주로 이어지고 있습니다. 캐나다의 신축 건물에서 LEED 채택률이 68%에 달한다는 사실은 북미 대륙 전체에서 실내 공기질(IAQ) 기준에 대한 부합이 진행되고 있음을 지원합니다.
유럽에서는 조만간 시행될 ‘건축물 에너지 성능 지침(EPBD)’ 개정에 따라 2027년까지 실내 공기질 측정 기준이 공식적으로 정해지며, 독일, 프랑스, 북유럽 국가들에서 도입이 촉진될 전망입니다. 중동에서는 사우디아라비아와 아랍에미리트(UAE)의 기후변화 대책 공약에 따라 호텔·리조트 업계의 개보수 공사가 추진되고 있으며, 규모는 작지만 두 자릿수 성장을 기록하고 있습니다. 남미는 경제 변동과 규제 체계의 미비로 인해 광범위한 도입이 저해되고 있으며, 다른 지역에 비해 뒤처지고 있지만, 상파울루와 부에노스아이레스의 대기 오염 문제가 주거용 판매의 점진적인 증가를 지원하고 있습니다.
기타 혜택:
- Excel 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모·성장률 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.07According to Mordor Intelligence, the air purifier market is expected to grow from USD 18.5 billion in 2025 to USD 20.04 billion in 2026 and is forecasted to reach USD 29.05 billion by 2031 at 7.71% CAGR over 2026-2031.
This report is Segmented by Filtration Technology (HEPA, Activated Carbon, Ionic/Electrostatic Precipitators, UV-C and Photocatalytic Oxidation, and Hybrid and Multi-Stage Systems), Type (Stand-Alone and In-Duct), Connectivity (Non-Smart and Smart/IoT-Enabled ), End User (Residential, Commercial, and Industrial), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Air Purifier Market Trends and Insights
Post-COVID Health-Centric Device Adoption in East Asian Metros
Persistent PM2.5 readings above national targets in Beijing, Seoul, and Tokyo have normalized year-round purifier ownership, extending the air purifier market beyond the pandemic spike. China's Ministry of Ecology and Environment confirmed that 38 of 168 monitored cities missed PM2.5 goals in 2024. Japan's health ministry updated indoor-air guidelines in 2024 to recommend HEPA filtration in childcare and eldercare facilities, institutionalizing a replacement cycle. Semiconductor engineers in South Korea, exposed to ultra-clean fabs, increasingly mirror workplace standards at home, creating a premium residential cohort. Xiaomi's RMB 2.5 billion smart-appliance factory opened in Wuhan in 2025, adding 7 million units of annual capacity that can flex between domestic and export orders. This combination of regulatory push and consumer pull solidifies a stable East-Asian demand base.
Stricter PM2.5 Commercial Real-Estate Standards in North America (LEED v4.1)
LEED v4.1's Indoor Environmental Quality credit mandates MERV 13 or higher filtration and continuous PM2.5 monitoring, compelling U.S. and Canadian building owners to retrofit or specify advanced purification from the design stage. Compliance budgets ranging from USD 50,000 to USD 150,000 for a 100,000-square-foot office are increasingly justified as tenants demand healthy-building certification for talent attraction and ESG reporting. ASHRAE 62.1-2022 further tightens outdoor-air ventilation rates, encouraging hybrid solutions that pair in-duct HEPA modules with portable units in meeting spaces. The Canada Green Building Council noted that 68% of new commercial projects sought LEED certification in 2025, signaling mainstream adoption. These standards are likely to cascade into Europe as revisions to the Energy Performance of Buildings Directive embed indoor-air metrics by 2027.
Ozone-Emission Restrictions on Ionizers in California & Japan
California's Air Resources Board capped ozone output from indoor cleaners at 0.050 ppm in 2024, effectively sidelining ionizer-centric designs. Japan's health ministry imposed parallel labeling rules in 2025 that limit ionizer sales in childcare facilities. Brands dependent on ionization, including Sharp and Panasonic, face USD 15-USD 25 per-unit redesign costs to meet thresholds, crimping margins in entry segments. The rule change funnels demand toward HEPA-pure or hybrid devices, benefiting competitors without ion emitters.
Other drivers and restraints analyzed in the detailed report include:
- Semiconductor Cleanroom Capacity Build-out in the US & South Korea
- Smart-Home Integration Pull for Connected Purifiers in EU & US
- High Filter Replacement Cost Sensitivity in ASEAN Mass Market
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
HEPA media captured 68.1% of the air purifier market share in 2025, favored for its 99.97% efficiency at 0.3 µm and endorsements from the U.S. EPA and WHO. Hybrid configurations that pair HEPA with activated carbon, UV-C, or photocatalytic oxidation are slated for a 9.3% CAGR because households and businesses now target VOCs, pathogens, and odors in a single chassis. Daikin's Streamer plasma module showed 99.9% SARS-CoV-2 inactivation in 2024 lab tests. Panasonic's nanoe X hydroxyl-radical generator is popular in Japan's eldercare market, where pathogen control ranks with particulate capture. Ionic precipitators retreat to niche industrial uses as ozone-cap rules in California and Japan tighten. Lack of harmonized efficacy standards for hybrid units, however, tempers adoption in risk-averse hospitals and pharmaceutical plants.
Hybrid systems also dovetail with smart-sensor arrays that trigger stage-specific filtration to curb energy draw and extend filter life. LG's Clean Booster vortex airflow increases CADR 47% over conventional centrifugal fans, enabling similar room coverage with smaller form factors. UV-C and photocatalytic modules remain premium add-ons costing USD 80-USD 120 per unit, limiting penetration below the USD 500 price tier. Prospective regulation around UV-C exposure could further shape the competitive field, but no global consensus exists yet.
Stand-alone devices accounted for 79.5% of the air purifier market volume in 2025 as renters and homeowners favored plug-and-play solutions priced between USD 150 and USD 800. Nevertheless, in-duct installations are scaling at an 8.8% CAGR through 2031, especially within commercial campuses that prefer centralized maintenance. A single in-duct HEPA retrofit costing USD 20,000-USD 40,000 can meet LEED air-change requirements for a 50,000-square-foot office, whereas equivalent coverage with portables would need 50 units and recurring labor for filter swaps. Samsung's 2025 acquisition of FlaktGroup extends its HVAC reach into purification modules that target hospitals and airports. Data-center operators adopt in-duct systems to keep airborne particulates below 10 µg/m3, protecting high-density servers from overheating or shorts. Portable units remain dominant in hospitality and multifamily housing, where room-specific control and aesthetics outweigh operational consolidations.
Regional HVAC penetration shapes these trends: North America and Europe, with about 85% central-HVAC adoption in commercial buildings, naturally migrate to in-duct solutions. By contrast, Asia-Pacific's heterogeneous building stock sustains portable demand, although new Grade-A offices in Beijing, Seoul, and Singapore are increasingly designed with built-in filtration plenum space. Suppliers that can package both portable and in-duct offerings stand to address the full project life cycle, from break-fix replacements to green-field architectural specs.
Complete Report Scope:
- By Filtration Technology
- HEPA
- Activated Carbon
- Ionic/Electrostatic Precipitators
- UV-Cand Photocatalytic Oxidation
- Hybrid and Multi-stage Systems
- By Type
- Stand-alone/Portable
- In-duct/Central HVAC
- By Connectivity
- Non-Smart (Manual/Analog)
- Smart/IoT-Enabled (App and Voice Controlled)
- By End User
- Residential
- Commercial (Hospitality and Leisure, Healthcare Facilities and Clinics, Educational Institutions and Corporate Offices and Retail)
- Industrial (Manufacturing and Warehousing, Food and Beverage Processing, Pharmaceuticals and Clean-rooms and Data Centers and Server Rooms)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 42.9% of 2025 revenue for the air purifier market and will climb at an 8.5% CAGR through 2031 on sustained urban PM2.5 levels, aggressive semiconductor investments, and government clean-air programs. China's environment ministry reported 38 non-attainment cities in 2024, underpinning stable household demand. Xiaomi's Wuhan factory adds 7 million units of annual output, reinforcing local cost advantages. Japan's updated childcare IAQ guidelines promote HEPA installations, creating steady replacement cycles.
North America, though smaller in unit volume, exhibits the fastest policy-driven acceleration as LEED v4.1, ASHRAE 62.1, and CHIPS Act funds converge. Semiconductor fabs under construction across Arizona, Texas, and Ohio mandate HEPA/ULPA infrastructure, pulling through significant B2B orders. Canada's 68% LEED adoption rate for new builds underscores continental alignment with IAQ standards.
Europe's forthcoming Energy Performance of Buildings Directive revision will formalize indoor-air metrics by 2027, driving uptake in Germany, France, and the Nordics. The Middle East leverages hospitality retrofits under Saudi and Emirati climate pledges, producing double-digit growth, albeit from a small base. South America trails as economic volatility and limited regulatory frameworks hamper widespread adoption, although pollution in Sao Paulo and Buenos Aires nudges incremental residential sales.
- Daikin Industries Ltd
- Sharp Corporation
- Dyson Ltd
- Koninklijke Philips N.V.
- LG Electronics Inc.
- Panasonic Corporation
- Whirlpool Corporation
- Resideo Technologies Inc.
- Samsung Electronics Co. Ltd
- Xiaomi Corp.
- Honeywell International Inc.
- IQAir AG
- Coway Co. Ltd
- Winix Inc.
- Blueair AB
- AllerAir Industries Inc.
- Airdog (IAQ Tech)
- Austin Air Systems Ltd
- Kent RO Systems Ltd
- TruSens (ACCO Brands)
- Medify Air LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-COVID Health-Centric Device Adoption in East Asian Metros
- 4.2.2 Stricter PM2.5 Commercial Real-Estate Standards in North America (LEED v4.1)
- 4.2.3 Semiconductor Clean-room Capacity Build-out in the US & South Korea
- 4.2.4 Smart-Home Integration Pull for Connected Purifiers in EU & US
- 4.2.5 ESG-Driven Hospitality Upgrades across GCC Countries
- 4.2.6 Indian NCAP Subsidies for HEPA Purifiers in Public Schools
- 4.3 Market Restraints
- 4.3.1 Ozone-Emission Restrictions on Ionizers in California & Japan
- 4.3.2 High Filter Replacement Cost Sensitivity in ASEAN Mass Market
- 4.3.3 Consumer Skepticism on CADR Claims-Lack of Unified Test Protocol
- 4.3.4 HVAC In-duct Filtration Diluting Stand-alone Unit Demand in Large Offices
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Filtration Technology
- 5.1.1 HEPA
- 5.1.2 Activated Carbon
- 5.1.3 Ionic/Electrostatic Precipitators
- 5.1.4 UV-Cand Photocatalytic Oxidation
- 5.1.5 Hybrid and Multi-stage Systems
- 5.2 By Type
- 5.2.1 Stand-alone/Portable
- 5.2.2 In-duct/Central HVAC
- 5.3 By Connectivity
- 5.3.1 Non-Smart (Manual/Analog)
- 5.3.2 Smart/IoT-Enabled (App and Voice Controlled)
- 5.4 By End User
- 5.4.1 Residential
- 5.4.2 Commercial (Hospitality and Leisure, Healthcare Facilities and Clinics, Educational Institutions and Corporate Offices and Retail)
- 5.4.3 Industrial (Manufacturing and Warehousing, Food and Beverage Processing, Pharmaceuticals and Clean-rooms and Data Centers and Server Rooms)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Spain
- 5.5.2.5 Nordic Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Australia
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Colombia
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Daikin Industries Ltd
- 6.4.2 Sharp Corporation
- 6.4.3 Dyson Ltd
- 6.4.4 Koninklijke Philips N.V.
- 6.4.5 LG Electronics Inc.
- 6.4.6 Panasonic Corporation
- 6.4.7 Whirlpool Corporation
- 6.4.8 Resideo Technologies Inc.
- 6.4.9 Samsung Electronics Co. Ltd
- 6.4.10 Xiaomi Corp.
- 6.4.11 Honeywell International Inc.
- 6.4.12 IQAir AG
- 6.4.13 Coway Co. Ltd
- 6.4.14 Winix Inc.
- 6.4.15 Blueair AB
- 6.4.16 AllerAir Industries Inc.
- 6.4.17 Airdog (IAQ Tech)
- 6.4.18 Austin Air Systems Ltd
- 6.4.19 Kent RO Systems Ltd
- 6.4.20 TruSens (ACCO Brands)
- 6.4.21 Medify Air LLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment