

|
시장보고서
상품코드
2122463
불소수지 코팅 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Fluoropolymer Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
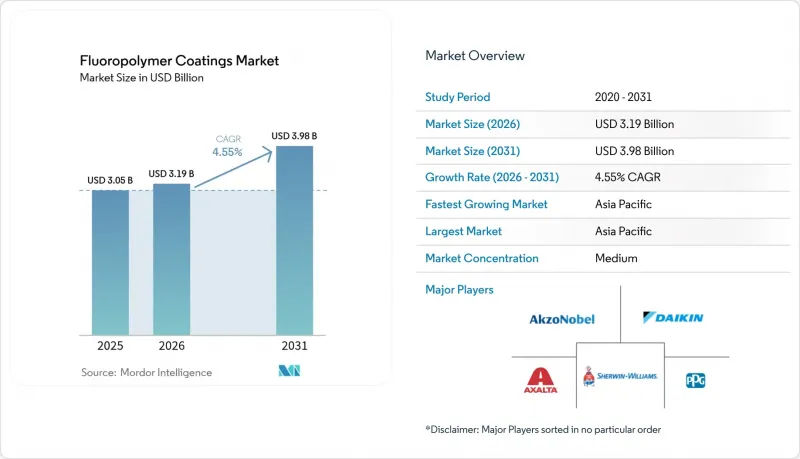
에 의하면, 불소수지 코팅 시장 규모는 2025년에 30억 5,000만 달러로 평가되었습니다. 2026년 31억 9,000만 달러에서 2031년까지 39억 8,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 4.55%를 나타낼 전망입니다.

본 보고서에서는 산업을 수지 유형별(폴리테트라플루오로에틸렌(PTFE), 폴리비닐리덴플루오라이드(PVDF), 기타), 코팅 기술별(액체, 분말),기재별(금속, 플라스틱, 복합재료·기타), 용도별(산업, 건축 및 건설, 자동차, 식품 가공, 조리 기구, 기타), 지역별(아시아태평양, 북미, 유럽, 기타)로 분류하고 있습니다.
세계의 불소수지 코팅 시장 동향 및 인사이트
해상 풍력 발전 타워용 부식 방지 코팅 수요 증가
해상 풍력 발전 설비의 급증에 따라, 기존 에폭시계 시스템을 능가하는 성능 요건이 요구되고 있습니다. 현재, 불소수지 배합에는 해수, 염수 분무, 터빈 출력을 30%나 저하시킬 가능성이 있는 얼음 축적에 내성을 가진 유기·무기 하이브리드 소재가 포함되어 있습니다. 코팅의 수명은 10-12년에 달하는 것으로 예상되며, 심해 지역에 배치되는 차세대 부유식 플랫폼에서는 유지보수 주기가 2배로 연장됩니다. 프로토타입 졸-겔 계열 시스템은 금속에 대한 강력한 접착력을 발휘하고 피막 하부 부식을 저감함으로써, 25년의 수명을 목표로 하는 사업자에게 다운타임으로 인한 비용을 절감해 줍니다.
전기자동차 파워트레인 부품에 저마찰 코팅의 급속한 보급
전기 구동계는 내연기관보다 높은 회전수, 온도, 전압에서 작동하기 때문에 마찰학적 스트레스가 증가합니다. 불소수지층은 표면 에너지를 감소시키고, 아크 방전을 최소화하며, 800V e-액슬 내의 구리 도체를 보호함으로써 드라이브트레인 전체의 효율을 3-5% 향상시킵니다. 주요 OEM 업체들은 윤활 시스템의 소형화를 실현하고, 부품 수명을 연장하며, 주행 거리를 향상시키기 위해 베어링과 스플라인 기어에 PTFE 개질 코팅의 사용을 지정하고 있습니다. 중급 부문의 EV 모델에서 이러한 솔루션이 표준화됨에 따라, 향후 10년 후반에는 코팅 수요가 가속화될 전망입니다.
중국의 수출 할당제에 따른 형석 유래 HF산공급 및 가격 변동
중국은 채굴되는 형석의 절반 이상을 장악하고 있으며, 고부가가치 생산을 유지하기 위해 수출 할당량을 엄격히 제한하고 있어 해외 HF산 생산 업체들은 어려운 상황에 처해 있습니다. 2024년에는 현물 가격이 다시 급등하면서, 대형 불소수지 제조업체들은 다년 계약을 체결하고 재고를 늘리는 움직임을 보였습니다. 중소 코팅 제조업체들은 이익률 하락, 수주 잔고 감소, 납기 지연에 대한 취약성 증가에 직면해 있으며, 협상력과 공급망 회복력을 높이기 위한 합병이 진행되고 있습니다.
부문별 분석
PTFE는 260°C의 사용 온도와 화학적 비활성이라는 특성으로 인해 반도체 에칭 장비, 식품용 컨베이어, 화학 반응기 등 가혹한 환경에서의 용도에 적합하기 때문에 2025년에도 불소수지 코팅 시장에서 43.35%의 점유율을 유지했습니다.
가장 높은 연평균 성장률(CAGR) 5.12%를 기록한 PVDF는 리튬 이온 배터리의 양극 바인더, 분리막, 절연 내력과 용제 적합성이 극히 중요한 반도체 클린룸용 장비에 활용되고 있습니다. 북미와 유럽에서의 생산 능력 확대는 지역적 공급 안정성을 확보하는 동시에, 현지 생산을 통해 탄소 발자국과 관세를 최소화함으로써 PVDF의 성장 궤도를 더욱 공고히 하고 있습니다.
불소수지 코팅 시장 규모 중 액상 제제가 62.10%를 차지하고 있습니다. 막의 품질을 저하시키지 않으면서 VOC를 대폭 줄이는 수성 제품은 제조업체가 캘리포니아주와 EU의 엄격한 배출 규제를 준수하는 데 도움이 되고 있습니다.
분체 도료는 VOC를 거의 제로 수준으로 억제하고, 오버스프레이를 재활용할 수 있기 때문에 2031년까지 연평균 성장률(CAGR) 5.28%로 성장할 것으로 전망됩니다. CARC 인증 분체 탑코트 등의 개발을 통해 군사 자산에 대한 내화학성이 확보되는 동시에 시공 시간이 단축됨에 따라, 기존에는 액체 시스템이 주류를 이루던 항공우주, 해양, 중장비 부문으로 분체 도료의 용도가 확대되고 있습니다.
지역별 분석
2025년, 아시아태평양은 불소수지 코팅 시장 점유율의 43.40%를 차지했습니다. 이는 중국의 광범위한 불소화학물제품 기반과 대규모 재생에너지 확장에 힘입은 결과입니다. 인도는 전자제품 및 태양광(PV) 제조를 촉진하는 인센티브 조치에 힘입어 그 뒤를 이으며, 플랜트 설비의 부식 방지 코팅에 대한 지속적인 수요를 창출하고 있습니다. 일본과 한국은 반도체 부문에서 주도적인 위치를 유지하고 있으며, 해당 지역의 최첨단 기술을 주도함으로써 고급 코팅의 소비를 안정적으로 유지하고 있습니다.
북미는 국내 PVDF 및 PTFE 생산을 촉진하는 리쇼어링의 혜택을 받고 있으며, 이를 통해 배터리 및 항공우주 부문의 주요 기업들은 공급 충격으로부터 보호받고 있습니다. 연방 정부의 인센티브는 ETFE 라이닝이 적용된 플랜트 주변 설비가 필요한 수소 프로젝트를 뒷받침하여 수요를 더욱 끌어올리고 있습니다.
유럽에서는 높은 환경 기준과 산업적 필요성 간의 균형이 이루어지고 있습니다. 독일과 영국의 해상 풍력 발전 타워 건설업체들은 비용이 많이 드는 북해에서의 유지보수 작업을 최소화하기 위해 수명이 긴 불소수지 코팅을 지정하고 있습니다. 임박한 PFAS 규제로 인해 배합 제조업체들은 장기적인 사업 지속을 보장하기 위해 폐쇄형 순환 재활용 및 저배출 제조 방식을 검토해야 하는 상황에 직면해 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the fluoropolymer coatings market size was valued at USD 3.05 billion in 2025 and estimated to grow from USD 3.19 billion in 2026 to reach USD 3.98 billion by 2031, at a CAGR of 4.55% during the forecast period (2026-2031).
This report Segments the Industry by Resin Type (Polytetrafluoroethylene (PTFE), Polyvinylidene Fluoride (PVDF), and More), Coating Technology (Liquid and Powder), Substrate (Metal, Plastic, and Composite and Others), Application (Industrial, Building and Construction, Automotive, Food Processing, Cookware, and More), and Geography (Asia-Pacific, North America, Europe, and More).
Global Fluoropolymer Coatings Market Trends and Insights
Increased Demand for Anti-corrosive Coatings in Offshore Wind Turbine Towers
Surging offshore wind installations are elevating performance requirements beyond conventional epoxy systems. Fluoropolymer formulations now integrate organic-inorganic hybrids that resist seawater, salt spray, and ice accumulation that can cut turbine output by 30%. Coating lifetimes are projected to stretch to 10 - 12 years, doubling the maintenance window for next-generation floating platforms deployed in deeper waters. Prototype sol-gel systems deliver strong metal adhesion, reducing under-film corrosion and cutting downtime expenses for operators who target 25-year service lives.
Fast-growing Adoption of Low-Friction Coatings in Electric-Vehicle Powertrains
Electrified drivetrains operate at higher rpm, temperature, and voltage than internal-combustion engines, amplifying tribological stress. Fluoropolymer layers reduce surface energy, minimize arcing, and protect copper conductors in 800 V e-axles, raising overall drivetrain efficiency by 3-5%. Leading OEMs specify PTFE-modified coatings on bearings and spline gears to enable downsized lubrication systems, extending part life and boosting range. Standardization of these solutions across mid-segment EV models will accelerate coating volumes by the latter half of the decade.
Volatile Supply and Pricing of Fluorspar-derived HF Acid
China controls well over half of mined fluorspar and tightens export quotas to retain value-added production, squeezing external producers of HF acid. Spot prices rose sharply again in 2024, prompting larger fluoropolymer makers to lock multi-year contracts and build stockpiles. Smaller coaters face margin erosion, shortened order books, and greater exposure to delivery disruptions, encouraging mergers aimed at negotiating power and supply-chain resilience.
Other drivers and restraints analyzed in the detailed report include:
- Growth of High-temperature Non-stick Coatings in Smart Cookware
- Expansion of PVDF-lined Lithium-ion Battery Gigafactories
- Strict Environmental Policies and Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PTFE maintained 43.35% of fluoropolymer coatings market share in 2025 because its 260 °C service temperature and chemical inertness serve harsh duties in semiconductor etching tools, food-grade conveyors, and chemical reactors.
PVDF, posting the fastest 5.12% CAGR, is leveraged in lithium-ion cathode binders, separator films, and semiconductor clean-room hardware where its dielectric strength and solvent compatibility are critical. Capacity expansions in North America and Europe lock in regional security of supply, while localized production minimizes carbon footprints and tariffs, further entrenching PVDF's trajectory.
Liquid formulations held 62.10% of fluoropolymer coatings market size. Waterborne variants that slash VOCs without compromising film integrity are helping manufacturers comply with stringent emission rules in California and the EU.
Powder coatings deliver near-zero VOCs and over-spray recyclability, propelling a 5.28% CAGR through 2031. Developments such as CARC-qualified powder topcoats offer chemical-agent resistance for military assets while cutting application time, broadening powder use into aerospace, maritime, and heavy equipment segments formerly dominated by liquid systems.
Complete Report Scope:
- By Resin Type
- Polytetrafluoroethylene (PTFE)
- Polyvinylidene Fluoride (PVDF)
- Fluorinated Ethylene Propylene (FEP)
- Ethylene Tetrafluoroethylene (ETFE)
- Perfluoroalkoxy Alkanes (PFA)
- Polyvinyl Fluoride (PVF)
- Other Resin Types
- By Coating Technology
- Liquid
- Powder
- By Substrate
- Metal
- Plastic
- Composite and Others
- By Application
- Industrial
- Building and Construction
- Automotive
- Food Processing
- Aviation and Aerospace
- Electrical
- Cookware
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia Pacific accounted for 43.40% of fluoropolymer coatings market share in 2025, driven by China's extensive fluorochemicals base and massive renewable-energy build-out. India follows with incentives that stimulate electronics and PV manufacturing, creating sustained coating demand for anti-corrosive plant equipment. Japan and South Korea maintain leadership in semiconductors, pushing the region's technology frontier and thereby steadying premium coating consumption.
North America benefits from reshoring that promotes domestic PVDF and PTFE production, insulating battery and aerospace primes from supply shocks. Federal incentives catalyze hydrogen projects that call for ETFE-lined balance-of-plant hardware, further bolstering demand.
Europe balances high environmental standards with industrial necessity. Offshore-wind tower builders in Germany and the United Kingdom specify long-life fluoropolymer layers to minimize expensive North Sea maintenance campaigns. Nevertheless, the looming PFAS restriction forces formulators to examine closed-loop recycling and lower-emission manufacturing to secure long-term viability.
- AkzoNobel N.V.
- Arkema SA
- Axalta Coating Systems LLC
- Beckers Group
- Berger Paints India Ltd.
- Daikin Industries, Ltd.
- Dongyue Group Co., Ltd.
- Endura Coatings
- Hempel A/S
- Jiangsu Chenguang Fluoropolymer Co., Ltd.
- Jotun
- NIC Industries Inc.
- PPG Industries, Inc.
- Praxair Surface Technologies, Inc.
- Precision Coating Company, LLC (Integer Holdings Corporation)
- Solvay SA
- The Chemours Company
- The Sherwin-Williams Company
- Tnemec Company Inc.
- Walter Wurdack Inc.
- Whitford Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increased Demand for Anti-corrosive Coatings in Offshore Wind Turbine Towers
- 4.2.2 Fast-growing Adoption of Low-Friction Coatings in Electric Vehicle Powertrain Components
- 4.2.3 Growth of High-temperature Non-stick Coatings in Smart Cookware
- 4.2.4 Expansion of PVDF-lined Lithium-ion Battery Gigafactories in the North America and Europe
- 4.2.5 Surge in Hydrogen Pipeline Projects Driving ETFE and FEP Coatings
- 4.3 Market Restraints
- 4.3.1 Volatile Supply and Pricing of Fluorspar-derived HF Acid Due to Chinese Export Quotas
- 4.3.2 Competition from Low-priced Protective Coatings Available in the Industry
- 4.3.3 Strict Environmental Policies and Regulations
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Polytetrafluoroethylene (PTFE)
- 5.1.2 Polyvinylidene Fluoride (PVDF)
- 5.1.3 Fluorinated Ethylene Propylene (FEP)
- 5.1.4 Ethylene Tetrafluoroethylene (ETFE)
- 5.1.5 Perfluoroalkoxy Alkanes (PFA)
- 5.1.6 Polyvinyl Fluoride (PVF)
- 5.1.7 Other Resin Types
- 5.2 By Coating Technology
- 5.2.1 Liquid
- 5.2.2 Powder
- 5.3 By Substrate
- 5.3.1 Metal
- 5.3.2 Plastic
- 5.3.3 Composite and Others
- 5.4 By Application
- 5.4.1 Industrial
- 5.4.2 Building and Construction
- 5.4.3 Automotive
- 5.4.4 Food Processing
- 5.4.5 Aviation and Aerospace
- 5.4.6 Electrical
- 5.4.7 Cookware
- 5.4.8 Other Applications
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 Italy
- 5.5.3.4 France
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (Merger and Acquisition, JV, Capacity Expansions)
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 AkzoNobel N.V.
- 6.4.2 Arkema SA
- 6.4.3 Axalta Coating Systems LLC
- 6.4.4 Beckers Group
- 6.4.5 Berger Paints India Ltd.
- 6.4.6 Daikin Industries, Ltd.
- 6.4.7 Dongyue Group Co., Ltd.
- 6.4.8 Endura Coatings
- 6.4.9 Hempel A/S
- 6.4.10 Jiangsu Chenguang Fluoropolymer Co., Ltd.
- 6.4.11 Jotun
- 6.4.12 NIC Industries Inc.
- 6.4.13 PPG Industries, Inc.
- 6.4.14 Praxair Surface Technologies, Inc.
- 6.4.15 Precision Coating Company, LLC (Integer Holdings Corporation)
- 6.4.16 Solvay SA
- 6.4.17 The Chemours Company
- 6.4.18 The Sherwin-Williams Company
- 6.4.19 Tnemec Company Inc.
- 6.4.20 Walter Wurdack Inc.
- 6.4.21 Whitford Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Sustainable and Eco-Friendly Coatings


