

|
시장보고서
상품코드
2122475
열가소성 복합재료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Thermoplastic Composites - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 열가소성 복합재료 시장 규모는 2025년 492만 톤으로 평가되었습니다. 2026년에는 517만 톤으로 확대되어 2031년까지 664만 톤에 이를 것으로 예상되고 2026-2031년에 걸쳐 CAGR 5.14%로 성장할 전망입니다.

본 보고서는 수지 유형별(폴리프로필렌, 폴리아미드, 기타), 섬유 유형별(유리섬유, 탄소섬유, 기타 섬유 유형), 제품 유형별(단섬유, 장섬유, 기타), 최종 사용자 산업별(자동차, 항공우주 및 방위, 기타),지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시되어 있습니다.
세계의 열가소성 복합재료 시장 동향 및 인사이트
유럽과 미국에서 자동차 경량화를 위한 규제 도입 가속화
2025년 중반에 시행된 유로 7 규제와 미국 환경보호청(EPA)의 2027-2032년 온실가스 기준에 따라, 자동차 제조업체는 차량군의 평균 배출량 제한 범위 내에 맞추기 위해 차량 공차 중량을 8%-12% 감축해야 할 의무가 있습니다. 열가소성 복합재료는 강재에 비해 30%-40%의 경량화를 실현할 뿐만 아니라, 성형 사이클이 60초 이하이므로 생산 라인에 통합이 가능합니다. BMW iX의 루프 패널은 차량당 15kg의 경량화를 실현하면서 구조적 실현 가능성을 보여주고 있습니다. CO₂ 배출량이 기준치를 초과할 경우, 1그램당 95유로 이상의 벌금이 부과되므로 경제적 관점에서도 복합재의 채택은 피할 수 없습니다.
e-모빌리티 부문에서 재활용 가능한 복합재료 솔루션에 대한 OEM 각사의 노력
EU 배터리 규정의 재활용 함량 및 디지털 여권 기준은 재용해 가능한 매트릭스를 사용하여 제조된 폐쇄형 루프 구조의 하우징을 장려하고 있습니다. 메르세데스-벤츠는 단섬유 폴리아미드 하우징을 회수하여 재사용하고 있으며, 충격 강도의 저하 없이 22%의 재활용 함량 비율을 달성하고 있습니다. 중국의 ‘분해 설계’에 관한 규정안이 이러한 전환을 뒷받침하고 있으며, 미국 화학 산업 협회(ACC)는 2030년까지 복합재 스크랩의 재활용률을 30%로 높이는 것을 목표로 하고 있습니다.
원료 및 성형 공정의 높은 비용
2024년부터 2025년에 걸쳐 카프로락탐 공급이 부족해지면서 폴리아미드 수지 가격은 톤당 2,800-3,400달러 사이에서 변동했습니다. 또한 PEEK는 여전히 1kg당 60-80달러의 높은 가격을 유지하고 있어, 항공기 및 임플란트 분야 이외로의 보급을 저해하고 있습니다. 탄소섬유는 1kg당 15-25달러로, 유리섬유에 비해 여전히 비싼 가격대를 보이고 있습니다. 자동 테이프 적층 셀의 도입 비용이 500만 달러를 초과하여 중소기업의 진입이 제한되고 있는 반면, 에폭시계 소재는 1kg당 4-6달러로 소량 생산이 이루어지는 항공우주 부문에서 시장 점유율을 유지하고 있습니다.
부문별 분석
폴리아미드 열가소성 복합재료 시장 규모는 자동차 산업의 사이클 타임 목표를 충족하는 고속 사출 성형 라인의 보급에 힘입어 2025년에는 총 생산량의 38.89%에 달했습니다. 흡습으로 인해 강성은 15%-20% 저하되지만, 충격 인성이 향상되기 때문에 범퍼 빔 용도로 수요는 유지되고 있습니다. PEEK는 총 생산량에서 차지하는 비중은 극히 미미하지만, 항공기 브래킷에는 180°C에서의 사용이 요구되고, 척추 케이지에는 방사선 투과성이 요구되기 때문에 연평균 성장률(CAGR) 6.08%로 성장하고 있습니다. 폴리프로필렌은 비용 및 재생재 함유율 요건이 부합하는 비구조용 커버 용도로 계속해서 채택되고 있는 반면, PPS와 PEI는 엔진룸 내의 난연성 틈새 시장을 충족시키고 있습니다.
전동화의 진전에 따라 내화학성 매트릭스에 대한 수요가 증가하고 있습니다. 배터리 트레이 공급업체들은 ELV(폐차)의 25% 재활용률 기준을 충족하기 위해 재활용 소재를 배합한 폴리아미드를 검사하고 있습니다. 한편, 미국 FDA의 PEEK 재질 척추 케이지에 대한 510(k) 승인은 외과의사들이 티타늄의 익숙한 촉감을 중요시하는 상황에서도 병원 측 수요를 뒷받침하고 있습니다. 예측 기간 동안, 폴리이미드 혼합물 및 저발연·무할로겐 PAEK 등급은 화재·연기·독성 검사가 성숙해지면 차량 내장재 부문에서 점유율을 확대할 가능성이 있습니다.
2025년 공급량의 87.27%를 차지한 유리 섬유는 72GPa의 탄성 계수를 갖추고 있으며, 가격은 1.50-2달러/kg으로 배터리 트레이나 시트백에 충분한 성능을 발휘합니다. 탄소섬유의 연평균 성장률(CAGR) 5.81%라는 전망은 메르세데스-벤츠 EQS의 루프 보우와 같은 프로그램에 힘입은 것으로, 이를 통해 8kg의 경량화와 12mm의 무게 중심 저하가 실현되었습니다. 바사ルト와 아라미드는 공급망 규모가 부족하여 합계 3% 이하에 그치고 있습니다.
충돌 안전 기준이 엄격해짐에 따라, 비용이 12달러/kg 미만으로 떨어지면 탄소섬유의 B-필러 보강재로의 채택이 점차 확대될 전망입니다. 이는 2027년에 중국에서 2개의 신규 25kt 생산 라인이 가동을 시작함으로써 실현될 것으로 예측됩니다. 천연섬유 하이브리드 소재는 EU의 승용차 도어 트림 방음 성능 검사에서 양호한 결과를 보였으나, 흡습성 문제는 여전히 남아 있습니다.
지역별 분석
아시아태평양은 2025년에 48.76%의 점유율을 차지했으며, 중국의 2,610만 대 자동차 생산과 주강 삼각주 일대의 전자 산업 클러스터가 주요 견인 역할을 했습니다. 2030년까지 연장된 베이징시의 신에너지차(NEV) 계획에서는 재활용 가능한 경량 부품의 사용이 의무화되어 있으며, 이는 단섬유 및 장섬유 원료 수입을 촉진하고 있습니다. 일본에서는 3,000억 엔의 보조금을 통해 2030년까지 1,000곳의 수소 충전소가 구축될 예정이며, 이로 인해 유형 IV 실린더 수요가 견인되고 있습니다. 한국에서는 멀티머티리얼 미드프레임의 도입으로 스마트폰 조립 공정이 40% 단축되었습니다. 인도에서는 생산 연계형 인센티브로 인해 복합재 셀의 자본 비용이 절감되고 있는 반면, 베트남과 태국에서는 공급망의 다각화에 따라 오버몰드 생산 능력이 확대되고 있습니다.
북미와 유럽이 소비량의 대부분을 차지하고 있습니다. 미국의 CAFE 규제로 인해 디트로이트의 자동차 제조업체들은 복합재 차체 패널과 시트를 채택함으로써 모델당 100-150kg의 경량화를 달성해야 하는 상황에 놓여 있습니다. 보잉(Boeing)사의 777X 플로어 빔은 비용 절감과 제조 주기 단축을 실현하고 있으며, 유럽의 ELV 규제에서는 2030년까지 재활용 플라스틱 사용률을 25% 이상으로 하도록 하는 기준이 마련되어 있습니다. 영국의 1,800만 파운드 규모의 주익 외판 프로젝트는 ATI 시설의 인건비를 50% 절감하는 것을 목표로 하고 있습니다.
중동 및 아프리카는 2031년까지의 성장률이 5.72%로 가장 높은 수준을 보이고 있습니다. NEOM에 건설되는 사우디 아람코의 200km에 달하는 수소 파이프라인은 60%의 경량화와 취성 저항성을 특징으로 합니다. 마스다르 시티에서는 50°C의 온도 변동을 견딜 수 있는 열가소성 플라스틱 파사드가 사양으로 채택되었습니다. 남아프리카의 남팍(Nampak)사의 컴파운딩 라인은 유럽 수출용 차량 생산을 준비하고 있는 반면, 나이지리아에서는 현지 조달 규정을 충족하기 위해 사워 가스용 복합 파이프의 평가가 진행되고 있습니다. 남미는 다소 뒤처져 있지만, 브라질의 농업 기계 부문에서는 디젤 소비량이 적은 경량 수확기가 시장에서 호응을 얻고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the thermoplastic composites market size is expected to increase from 4.92 Million tons in 2025 to 5.17 Million tons in 2026 and reach 6.64 Million tons by 2031, growing at a CAGR of 5.14% over 2026-2031.
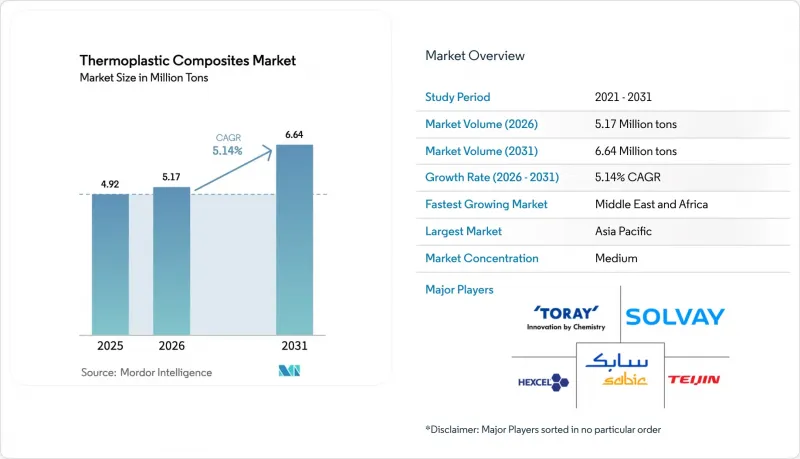
This report is Segmented by Resin Type (Polypropylene, Polyamide, and More), Fiber Type (Glass Fiber, Carbon Fiber, Other Fiber Types), Product Type (Short-Fiber, Long-Fiber, and More), End-User Industry (Automotive, Aerospace and Defense, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). Market Forecasts are Provided in Terms of Volume (Tons).
Global Thermoplastic Composites Market Trends and Insights
Rapid Vehicle Lightweighting Mandates in Europe and the United States
Euro 7 rules effective mid-2025 and the U.S. EPA's 2027-2032 greenhouse-gas standards oblige automakers to remove 8%-12% of curb weight to stay inside fleet-average limits. Thermoplastic composites deliver 30%-40% savings versus steel yet cycle in under 60 seconds, enabling line-side integration. BMW's iX roof panel shows structural feasibility while trimming 15 kg per vehicle. Penalties above EUR 95 per excess gram of CO2 make adoption financially unavoidable.
OEM Push for Recyclable Composite Solutions in E-Mobility
EU Battery Regulation thresholds on recycled content and digital passports promote closed-loop enclosures built from remeltable matrices. Mercedes-Benz recovers short-fiber polyamide housings for reuse, achieving 22% recycled content with no impact-strength loss. China's draft design-for-disassembly rules amplify the shift, and the American Chemistry Council targets 30% composite scrap circularity by 2030.
High Cost of Raw Materials and Forming Processes
Polyamide resins fluctuated between USD 2,800 and USD 3,400/ton in 2024-2025 as caprolactam supply tightened, and PEEK still commands USD 60-80/kg, curbing penetration outside aviation and implants. Carbon fiber at USD 15-25/kg remains a premium over glass. Automated tape-laying cells exceed USD 5 million, limiting SME entry, whereas epoxy systems price in at USD 4-6/kg and keep share in low-volume aerospace runs.
Other drivers and restraints analyzed in the detailed report include:
- Asia-Pacific LNG and Hydrogen Storage Megaproject Pipeline
- Thermoplastic Over-Molding Adoption in Smart-Electronics Housings
- Limited Awareness and Standardization
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The thermoplastic composites market size for polyamide reached 38.89% of total volume in 2025, owing to high-speed injection lines that meet automotive cycle-time targets. Moisture absorption cuts stiffness 15%-20% but boosts impact toughness, sustaining bumper-beam appeal. PEEK, although just a fraction of tonnage, is on a 6.08% CAGR path as aircraft brackets need 180 °C service and spine cages demand radiolucency. Polypropylene retains non-structural covers where cost and recycled-content mandates align, while PPS and PEI satisfy under-hood flame-retardant niches.
Heightened electrification keeps demand for chemical-resistant matrices; battery-tray suppliers are trialing recycled-content polyamide to meet 25% ELV thresholds. Meanwhile, the U.S. FDA's 510(k) clearance of PEEK spinal cages spurs hospital demand even as surgeons weigh titanium familiarity. Over the forecast horizon, polyimide blends and low-smoke zero-halogen PAEK grades could carve out cabin-interior volume once fire-smoke-toxicity testing matures.
Glass fiber supplied 87.27% of 2025 volume, offering 72 GPa modulus for USD 1.50-2.00/kg - adequate for battery trays and seat backs. Carbon fiber's 5.81% CAGR outlook is underpinned by programs like Mercedes-Benz EQS roof bows that trim 8 kg and lower center of gravity 12 mm. Basalt and aramid remain below 3% combined because supply chains lack scale.
Crash-standards tightening will gradually expand carbon into B-pillar reinforcements once cost drops below USD 12/kg, expected as two new 25 kt lines in China come online in 2027. Natural-fiber hybrids are testing well for door-trim acoustics in EU vans, though moisture uptake challenges persist.
Complete Report Scope:
- By Resin Type
- Polypropylene (PP)
- Polyamide (PA)
- Polyether-ether-ketone (PEEK)
- Other Resin Types
- By Fiber Type
- Glass Fiber
- Carbon Fiber
- Other Fiber Types
- By Product Type
- Short-Fiber Thermoplastic (SFT)
- Long-Fiber Thermoplastic (LFT)
- Continuous-Fiber Thermoplastic (CFT)
- Glass-Mat Thermoplastic (GMT)
- By End-User Industry
- Automotive
- Aerospace and Defense
- Electrical and Electronics
- Construction
- Medical
- Other End-Users
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 48.76% share in 2025, powered by China's 26.1 million vehicle output and electronics clusters along the Pearl River Delta. Beijing's NEV plan, extended to 2030, requires recyclable lightweight components, fueling short- and long-fiber feedstock imports. Japan's JPY 300 billion subsidy backs 1,000 hydrogen stations by 2030, pulling Type IV cylinder demand. South Korea's multi-material mid-frame adoption reduced smartphone assembly steps 40%. India's production-linked incentive cuts capital costs for composite cells, while Vietnam and Thailand expand over-molding capacity as supply chains diversify.
North America and Europe account for significant consumption volume. U.S. CAFE rules force Detroit to drop 100-150 kg per model using composite closures and seating. Boeing's 777X floor beams showcase cost and cycle reductions, and Euro ELV mandates place 25% recycled-plastic thresholds by 2030. The U.K.'s GBP 18 million wing-skin project targets 50% labor cuts at ATI facilities.
The Middle East and Africa lead by growth rate at 5.72% through 2031. Saudi Aramco's 200-km hydrogen pipeline at NEOM highlights 60% weight savings and embrittlement resistance. Masdar City specs thermoplastic facades that survive 50 °C swings. South Africa's Nampak compounding line readies for export vehicles bound for Europe, while Nigeria assesses sour-gas composite pipe to meet local content rules. South America trails, though Brazilian agri-equipment gains from lightweight harvesters that consume less diesel.
- Arkema
- Avient Corporation
- Alsiano A/S
- BASF
- Celanese Corporation
- Daicel Corporation
- dsm-firmenich
- DuPont
- Hexcel Corporation
- LANXESS
- LyondellBasell Industries Holdings B.V.
- Mitsubishi Chemical Group Corporation
- Owens Corning
- RTP Company
- SABIC
- SGL Carbon
- Solvay
- TechnoCompound GmbH
- TEIJIN LIMITED
- TORAY INDUSTRIES, INC.
- Victrex plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Vehicle-Light-Weighting Mandates in Europe and the United States
- 4.2.2 OEM Push for Recyclable Composite Solutions in E-Mobility
- 4.2.3 Asia-Pacific LNG and Hydrogen-Storage Megaproject Pipeline
- 4.2.4 Thermoplastic Over-Moulding Adoption in Smart-Electronics Housings
- 4.2.5 Military Demand for Damage-Tolerant, Radar-Transparent Structures
- 4.3 Market Restraints
- 4.3.1 High Cost of Raw Materials and Forming Processes
- 4.3.2 Limited Awareness and Standardization
- 4.3.3 Competitive Pressure from Thermoset Composites
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Resin Type
- 5.1.1 Polypropylene (PP)
- 5.1.2 Polyamide (PA)
- 5.1.3 Polyether-ether-ketone (PEEK)
- 5.1.4 Other Resin Types
- 5.2 By Fiber Type
- 5.2.1 Glass Fiber
- 5.2.2 Carbon Fiber
- 5.2.3 Other Fiber Types
- 5.3 By Product Type
- 5.3.1 Short-Fiber Thermoplastic (SFT)
- 5.3.2 Long-Fiber Thermoplastic (LFT)
- 5.3.3 Continuous-Fiber Thermoplastic (CFT)
- 5.3.4 Glass-Mat Thermoplastic (GMT)
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Aerospace and Defense
- 5.4.3 Electrical and Electronics
- 5.4.4 Construction
- 5.4.5 Medical
- 5.4.6 Other End-Users
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Arkema
- 6.4.2 Avient Corporation
- 6.4.3 Alsiano A/S
- 6.4.4 BASF
- 6.4.5 Celanese Corporation
- 6.4.6 Daicel Corporation
- 6.4.7 dsm-firmenich
- 6.4.8 DuPont
- 6.4.9 Hexcel Corporation
- 6.4.10 LANXESS
- 6.4.11 LyondellBasell Industries Holdings B.V.
- 6.4.12 Mitsubishi Chemical Group Corporation
- 6.4.13 Owens Corning
- 6.4.14 RTP Company
- 6.4.15 SABIC
- 6.4.16 SGL Carbon
- 6.4.17 Solvay
- 6.4.18 TechnoCompound GmbH
- 6.4.19 TEIJIN LIMITED
- 6.4.20 TORAY INDUSTRIES, INC.
- 6.4.21 Victrex plc
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Wide Application Scope in the Healthcare Sector


