

|
시장보고서
상품코드
2122510
클라우드 모니터링 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Cloud Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 클라우드 모니터링 시장 규모는 2025년 37억 5,000만 달러에서 2026년에는 44억 8,000만 달러로 성장하고, 2026-2031년 CAGR 19.56%로 성장을 지속하여 2031년에는 109억 5,000만 달러에 달할 것으로 예측됩니다.
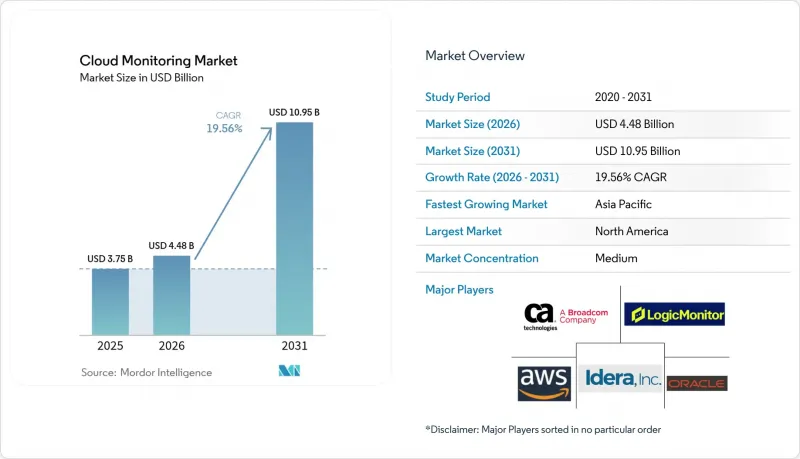
본 보고서는 클라우드 서비스 모델(IaaS, SaaS, PaaS), 구성 요소(솔루션 및 서비스), 도입 형태(퍼블릭 클라우드, 프라이빗 클라우드, 하이브리드/멀티 클라우드), 조직 규모(중소기업 및 대기업), 최종 사용자 산업(은행, 금융서비스 및 보험(BFSI), 소매 및 전자상거래,IT 및 통신, 헬스케어 및 생명과학, 정부·공공 부문, 제조업, 기타) 및 지역별로 분류되어 있습니다.
세계 클라우드 모니터링 시장 동향 및 인사이트
멀티클라우드 및 하이브리드 클라우드 도입 가속화
멀티클라우드 활용은 전환점을 넘어, 2024년에는 금융 서비스 기업의 43%가 이미 2개 이상의 하이퍼스케일러에 워크로드를 분산시키고 있습니다. 각 제공업체가 고유한 메트릭을 내보내기 때문에 운영 팀은 텔레메트리 분산 및 사각지대에 직면하고 있습니다. 이에 따라 AWS, Azure, Google Cloud의 데이터를 표준화하는 통합 플랫폼이 단일 클라우드 모니터링 도구를 대체하고 있습니다. 벤더 중립적인 측정 기능을 통해 전체 환경을 쉽게 포괄할 수 있게 되면서 OpenTelemetry 에이전트의 채택이 급증했습니다. 또한, 동일한 트랜잭션이 On-Premise와 클라우드 노드에 걸쳐 있는 경우, 조직은 비용, 성능, 규정 준수의 상관관계를 보여주는 뷰가 필요합니다. 이러한 압박으로 인해 하이브리드 클라우드 관측 가능성은 ‘선택 사항’에서 ‘필수 기능’으로 격상되었으며, 클라우드 관측 가능성 시장은 더욱 심층적인 엔드투엔드 맥락으로 나아가고 있습니다.
DevOps/SRE 문화와 실시간 가시성
사이트 신뢰성 엔지니어링(SRE)은 대기업에서 주류로 자리 잡았으며, 시간당 100만 달러가 넘는 평균 다운타임 비용을 절감하고 있습니다. 현재 팀들은 CI/CD 파이프라인에 ‘골든 시그널’과 서비스 수준 목표를 통합하여, 프로덕션 환경으로 배포하기 전에 문제를 파악하고 있습니다. 풀스택 가시화를 통해 사일로화된 툴체인에 비해 다운타임을 79% 줄일 수 있습니다. AI를 활용한 이상 감지는 로그와 트레이스 전체에서 인시던트의 전조를 찾아냄으로써 사람의 작업을 보완합니다. 피드백 루프의 가속화 또한 개발자의 생산성을 향상시켜, 관측 가능성을 직접적인 비즈니스 촉진요인으로 전환하고 있습니다. 따라서 클라우드 관측 가능성 시장은 기존 IT 운영 부서가 아닌 엔지니어링 팀으로 예산이 이동하는 혜택을 누리고 있습니다.
컨테이너화·서버리스·스택에서의 가시성 한계
컨테이너의 수명은 불과 몇 초에 불과하고, 서버리스 함수는 에이전트 없이 실행되기 때문에 기존 모니터링 도구로는 메울 수 없는 모니터링 사각지대가 발생하고 있습니다. Kubernetes는 방대한 양의 메타데이터를 생성하기 때문에 무작정 수집하는 방식은 스토리지 비용을 증가시킵니다. 마이크로서비스 간을 가로지르며 요청 경로를 추적하는 분산 트레이스와 eBPF 기반의 낮은 오버헤드를 가진 측정 기능을 결합한 방식이 해결책으로 부상하고 있습니다. OpenTelemetry는 매우 중요하지만, 도입이 여전히 복잡하기 때문에 자원이 제한된 중소기업에서의 채택이 지연되고 있습니다. 턴키 방식의 측정 기능이 성숙해지기 전까지는 수명이 짧은 환경에서의 가시성 격차가 클라우드 가시성 시장의 연평균 성장률(CAGR)을 끌어내리는 요인이 될 것입니다.
부문 분석
SaaS 플랫폼은 2025년 매출의 47.80%를 차지하며, 인프라 오버헤드를 제거하는 턴키 도입에 대한 높은 수요를 뒷받침하고 있습니다. PaaS 솔루션은 가장 빠르게 성장하는 분야로, 사용자가 수집기를 관리할 필요 없이 코드 수준의 심층적인 인사이트를 추구함에 따라 연평균 성장률(CAGR) 28.45%로 성장하고 있습니다. IaaS 도구는 규제 대상 데이터 근처에 On-Premise 수집기가 필요한 하이브리드 환경에서 여전히 중요한 역할을 수행하고 있습니다. SaaS 분야의 클라우드 가시성 시장 규모는 뒤처져 있던 업계가 관리형 서비스로 전환함에 따라 2026년부터 2031년 사이에 29억 2,000만 달러로 확대될 것으로 예측됩니다.
PaaS의 성장세는 플랫폼 엔지니어링 팀이 내부 개발자 포털에 관측 가능성을 통합하고 있음을 반영합니다. 주요 기술 벤더들은 트레이싱, 카오스 테스트, KPI 대시보드를 빌드 파이프라인에 직접 통합하여 인지적 부하를 줄이고 있습니다. OpenTelemetry의 자동 계측 기능과 결합함으로써, 이러한 시너지 효과로 인해 가치 실현까지 걸리는 시간이 단축됩니다. 그 결과, 클라우드 가시성 시장의 신규 수주액의 약 3분의 1은 AI 모델의 가시성 및 비용 분석을 대상으로 하는 PaaS 프로젝트에서 비롯됩니다.
2025년에는 데이터 레이크, 상관 관계 엔진, UX 분석을 아우르는 솔루션 제품군이 매출의 61.30%를 차지했습니다. 기업들이 관측성 엔지니어 채용에 어려움을 겪는 가운데, 서비스 컨설팅, 온보딩, 매니지드 관측성은 연평균 성장률(CAGR) 18.85%로 성장하고 있습니다. 통합 업체에 대한 수요가 가장 높은 분야는 측정이 규제 프레임워크를 준수해야 하는 규제 대상 업종입니다.
벤더의 로드맵에는 현재 자문 서비스, 인증 교육, 그리고 가치 입증(PoV) 주기를 단축하는 퀵스타트 팩이 포함되어 있습니다. LogicMonitor가 서비스 확장을 위해 확보한 8억 달러 규모의 자금 조달은 전문적인 노하우가 얼마나 중요한 경쟁 우위가 되고 있는지를 보여줍니다. 프레임워크가 발전함에 따라, 정기 서비스 계약이 클라우드 관측 가능성 시장 전체 매출에서 차지하는 비중이 확대되고, 파트너 생태계가 더욱 공고해질 것입니다.
지역별 분석
북미는 2025년 매출의 40.60%를 차지하고 있으며, 이는 수십 년에 걸친 DevOps의 성숙도와 막대한 AI 투자를 반영합니다. 금융 기관들은 연간 1,044만 달러의 다운타임으로 인한 손실 중앙값을 제시하고 있으며, 이는 프리미엄 도구 도입을 정당화하는 근거가 되고 있습니다. ‘소버린 클라우드’에 대한 논의는 소극적이지만, 개인정보 보호 관련 법규로 인해 데이터 레지던시 기능에 대한 수요는 여전히 증가하고 있습니다. 2027년 이후에는 교체 주기가 포화 상태에 도달함에 따라 성장률이 10%대 초반으로 둔화되겠지만, AI 가시성 업그레이드로 인해 라이선스 확대는 지속될 전망입니다.
아시아태평양은 연평균 성장률(CAGR) 20.85%로 가장 빠르게 성장하고 있으며, 클라우드 우선(Cloud First)을 추구하는 스타트업과 정부 주도의 디지털화 추진이 원동력이 되고 있습니다. 인도의 퍼블릭 클라우드 지출은 2028년까지 255억 달러에 달할 전망입니다. 싱가포르와 인도네시아에서는 가시성의 ROI가 114%를 넘어, 다운타임 감소를 통한 높은 투자 대비 효과를 보이고 있습니다. 알리바바 클라우드가 43%의 점유율을 차지하는 중국(클라우드 시장 규모 6조 1,920억 위안)에서는 현지 언어 지원 대시보드와 국내 데이터 레이크가 추진되고 있습니다.
유럽에서는 GDPR(EU 개인정보보호규정) 및 향후 시행될 AI 법에 따라 데이터 보호 요건이 확고해지면서 연평균 성장률(CAGR)이 15%대 중반을 기록하고 있습니다. 액센츄어의 조사에 따르면, 기업의 37%가 소버린 클라우드에 투자하고 있으며, 44%는 2년 이내에 추가 투자를 계획하고 있습니다. 각 벤더사는 EU 역내에 로깅 파이프라인을 확보하기 위해 지역 호스팅 사업자와의 제휴를 추진하고 있습니다. 기후 변화 보고와 성과 지표가 융합됨에 따라 에너지 대시보드 도입이 확대되고 있습니다. 이러한 지역별 특징들이 결합되어 클라우드 관측 가능성 시장을 규정 준수를 중시하는 다양한 도입 형태로 이끌고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.03According to Mordor Intelligence, the cloud monitoring market size is expected to grow from USD 3.75 billion in 2025 to USD 4.48 billion in 2026 and is forecast to reach USD 10.95 billion by 2031 at 19.56% CAGR over 2026-2031.
This report is Segmented by Cloud Service Model (IaaS, Saas, Paas), Component (Solution and Services), Deployment Mode (Public Cloud, Private Cloud, and Hybrid/Multi-Cloud), Organization Size (SMEs and Large Enterprises), End-User Industry (BFSI, Retail and E-Commerce, IT and Telecommunications, Healthcare and Life Sciences, Government and Public Sector, Manufacturing, and Others), and Geography.
Global Cloud Monitoring Market Trends and Insights
Accelerated Multi-Cloud and Hybrid-Cloud Adoption
Multi-cloud usage crossed a tipping point, with 43% of financial-services firms already distributing workloads across two or more hyperscalers in 2024. Each provider exports unique metrics, so operations teams face telemetry sprawl and blind spots. Unified platforms that normalise data across AWS, Azure, and Google Cloud are therefore replacing single-cloud monitors. Adoption of OpenTelemetry agents rose sharply because vendor-neutral instrumentation eases estate-wide coverage. Organisations also need correlated cost, performance, and compliance views when the same transaction spans on-premises and cloud nodes. These pressures elevate hybrid-cloud observability from optional to indispensable capability, pushing the cloud observability market toward deeper end-to-end context.
DevOps/SRE Culture and Real-Time Observability
Site Reliability Engineering is mainstreamed in large enterprises, cutting mean outage costs that exceed USD 1 million per hour. Teams now embed golden signals and service-level objectives into CI/CD pipelines so that defects surface before production rollouts. Full-stack insight lowers downtime by 79% versus siloed toolchains. AI-driven anomaly detection augments humans by surfacing precursors to incidents across logs and traces. Faster feedback loops also boost developer productivity, turning observability into a direct business enabler. The cloud observability market, therefore, benefits from budgets shifting left toward engineering teams rather than traditional IT operations.
Limited Visibility in Containerised, Serverless Stacks
Containers may live for seconds, while serverless functions spin up without agents, leaving gaps that legacy monitors cannot fill. Kubernetes adds torrent-level metadata, so brute-force collection inflates storage bills. Distributed tracing that stitches request paths across microservices, combined with eBPF-based low-overhead instrumentation, is emerging as the remedy. OpenTelemetry is pivotal yet still complex to deploy, explaining slower adoption among resource-constrained SMEs. Until turnkey instrumentation matures, observability gaps in ephemeral environments will drag on the cloud observability market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- AI/ML Workload Explosion Requiring GPU-Level Monitoring
- FinOps Accountability and Cost-to-Value Optimisation Pressure
- Rising TCO of Full-Stack Observability Platforms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SaaS platforms anchored 47.80% of 2025 revenue, underscoring demand for turnkey deployments that remove infrastructure overhead. PaaS solutions shape the fastest lane, growing 28.45% CAGR as users crave deeper code-level insight without managing collectors. IaaS tools retain relevance for hybrid estates that need on-premises collectors close to regulated data. The cloud observability market size for SaaS is forecast to widen by USD 2.92 billion between 2026 and 2031 as lagging industries migrate to managed services.
PaaS momentum reflects platform-engineering teams embedding observability into internal developer portals. Big-tech vendors integrate tracing, chaos testing, and KPI dashboards directly into build pipelines, reducing cognitive load. Combined with OpenTelemetry auto-instrumentation, this synergy accelerates time to value. Consequently, the cloud observability market records almost one-third of net-new bookings from PaaS deals targeting AI model observability and cost analytics.
Solution suites captured 61.30% revenue in 2025, covering data lakes, correlation engines, and UX analytics. Services consulting, onboarding, and managed observability grow 18.85% CAGR as enterprises struggle to hire observability engineers. Integrator demand is highest in regulated verticals where instrumentation must map to control frameworks.
Vendor roadmaps now bundle advisory hours, certified training, and quick-start packs that shorten proof-of-value cycles. LogicMonitor's USD 800 million funding earmarked for services expansion signals how professional expertise becomes a key moat. As frameworks evolve, recurring service contracts will comprise a larger slice of the overall cloud observability market revenue, deepening partner ecosystems.
Complete Report Scope:
- By Cloud Service Model
- IaaS
- PaaS
- SaaS
- By Component
- Solution
- Services
- By Deployment Mode
- Public Cloud
- Private Cloud
- Hybrid/Multi-Cloud
- By Organisation Size
- SMEs
- Large Enterprises
- By End-User Industry
- BFSI
- Retail and e-Commerce
- IT and Telecommunications
- Healthcare and Life Sciences
- Government and Public Sector
- Manufacturing
- Others (Media, Energy, Education)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America commanded 40.60% of 2025 revenue, reflecting decades-long DevOps maturity and heavy AI investment. Financial institutions cite median outage losses of USD 10.44 million per year, justifying premium tooling. Sovereign-cloud talk is muted, yet privacy laws still nudge data residency features. Growth moderates to low teens after 2027 as replacement cycles saturate, but AI observability upgrades sustain license expansion.
Asia Pacific is the fastest mover at 20.85% CAGR, propelled by cloud-first start-ups and government digital drives. India's public cloud outlay could reach USD 25.5 billion by 2028. Observability ROI tops 114% in Singapore and Indonesia, showcasing high payoff for downtime reduction. China's 6.192 trillion-yuan cloud sector, led by Alibaba Cloud's 43% hold, fuels local-language dashboards and in-country data lakes.
Europe records mid-teens CAGR as GDPR and upcoming AI Act cement data-protection demands. Accenture notes 37% of enterprises investing in sovereign cloud, with 44% planning more within two years. Vendors partner with regional hosts to ensure EU-located logging pipelines. Energy dashboards gain traction as climate reporting merges with performance metrics. These regional nuances collectively propel the cloud observability market toward diverse compliance-aware deployments.
- AWS
- Microsoft
- Google Cloud
- IBM
- Oracle
- Datadog
- Dynatrace
- New Relic
- Broadcom (CA Tech/AppDynamics)
- LogicMonitor
- Splunk
- SolarWinds
- PagerDuty
- Cisco ThousandEyes
- Grafana Labs
- Elastic
- Zenoss
- ScienceLogic
- Idera
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated multi-cloud and hybrid-cloud adoption
- 4.2.2 DevOps/SRE culture and need for real-time observability
- 4.2.3 AI/ML workload explosion requiring GPU-level monitoring
- 4.2.4 FinOps accountability and cost-to-value optimisation pressure
- 4.2.5 Sustainability dashboards for cloud-carbon reporting
- 4.2.6 Sovereign-cloud and data-localisation mandates
- 4.3 Market Restraints
- 4.3.1 Limited visibility in containerised, serverless stacks
- 4.3.2 Rising TCO of full-stack observability platforms
- 4.3.3 Skills gap for observability engineering
- 4.3.4 Hyperscaler API-rate limits throttling deep telemetry
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry Intensity
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cloud Service Model
- 5.1.1 IaaS
- 5.1.2 PaaS
- 5.1.3 SaaS
- 5.2 By Component
- 5.2.1 Solution
- 5.2.2 Services
- 5.3 By Deployment Mode
- 5.3.1 Public Cloud
- 5.3.2 Private Cloud
- 5.3.3 Hybrid/Multi-Cloud
- 5.4 By Organisation Size
- 5.4.1 SMEs
- 5.4.2 Large Enterprises
- 5.5 By End-User Industry
- 5.5.1 BFSI
- 5.5.2 Retail and e-Commerce
- 5.5.3 IT and Telecommunications
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Government and Public Sector
- 5.5.6 Manufacturing
- 5.5.7 Others (Media, Energy, Education)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Spain
- 5.6.3.5 Russia
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Rest Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AWS
- 6.4.2 Microsoft
- 6.4.3 Google Cloud
- 6.4.4 IBM
- 6.4.5 Oracle
- 6.4.6 Datadog
- 6.4.7 Dynatrace
- 6.4.8 New Relic
- 6.4.9 Broadcom (CA Tech/AppDynamics)
- 6.4.10 LogicMonitor
- 6.4.11 Splunk
- 6.4.12 SolarWinds
- 6.4.13 PagerDuty
- 6.4.14 Cisco ThousandEyes
- 6.4.15 Grafana Labs
- 6.4.16 Elastic
- 6.4.17 Zenoss
- 6.4.18 ScienceLogic
- 6.4.19 Idera
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


