

|
시장보고서
상품코드
2122522
기업용 비디오 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Enterprise Video - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
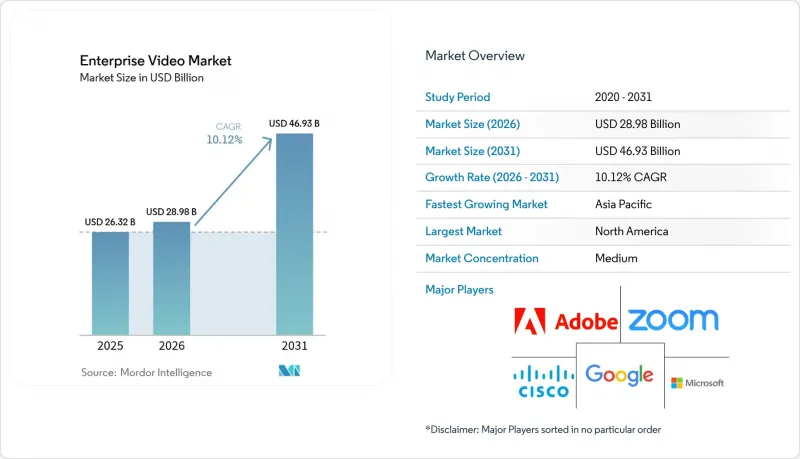
에 의하면, 기업용 비디오 시장 규모는 2025년 263억 2,000만 달러로 평가되었습니다. 2026년에는 289억 8,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 10.12%로 성장을 지속하여, 2031년에는 469억 3,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 유형별(화상 회의, 비디오 콘텐츠 관리, 웹캐스트 및 라이브 스트리밍, 비디오 분석, 기타), 구성 요소별(하드웨어, 소프트웨어, 서비스), 배포 모드별(On-Premise, 클라우드), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 의료, IT 및 통신, 기타),조직 규모별(중소기업, 대기업), 지역별로 분류되어 있습니다.
세계의 기업용 비디오 시장 동향 및 인사이트
클라우드 우선 비디오 아키텍처의 도입
클라우드 네이티브 스택으로의 전환을 통해 초기 비용을 절감하면서도 탄력적인 확장, API 주도형 통합 및 전 세계적인 콘텐츠 배포가 가능해집니다. 기업들은 기밀성이 높은 아카이브를 On-Premise에 보관하면서, 계산 부하가 높은 분석 처리는 퍼블릭 클라우드에 맡김으로써 로컬 하드웨어의 업데이트 주기를 단축하고 있습니다. 멀티 클라우드 라우팅은 벤더 종속성이나 지연 시간 변동으로부터 보호할 뿐만 아니라, IT 팀이 다양한 워크로드를 최적의 비용 대비 성능을 제공하는 리전에 할당할 수 있게 해줍니다. 하지만 월간 데이터 출력 요금이 탄력성의 이점을 상회하는 경우, 일부 기업이 프라이빗 인프라에 대한 지출을 재분배하는 ‘클라우드 엑시트’ 전략도 대두되고 있습니다.
AI를 활용한 라이브 캡션 정확도의 비약적 발전
자동 음성 인식 모델은 음향 조건이 양호한 환경에서 최대 98%의 정확도를 달성하게 되어, 동영상 접근성을 단순한 규정 준수의 범위를 넘어 생산성 향상으로 이끌고 있습니다. 140개 언어에 이르는 풍부한 언어 지원은 국경을 초월한 협업을 촉진하며, 검색 가능한 트랜스크립션 데이터는 언제든지 활용할 수 있는 지식 저장소를 가능하게 합니다. 기업들은 이러한 AI 자막을 콘텐츠 관리 시스템에 직접 통합함으로써 참여 지표를 향상시키고 콘텐츠 현지화를 가속화하고 있습니다. 또한, 이러한 발전은 청각 장애가 있거나 난청을 가진 직원이 제3자의 자막 제작자 없이도 실시간으로 회의에 참여할 수 있게 함으로써, 포용적인 채용 관행을 촉진하는 데에도 기여하고 있습니다.
초저지연 인프라의 높은 총비용
왕복 25밀리초 미만의 성능을 요구하는 기업은 프라이빗 5G, 엣지 CDN 노드 및 GPU 가속 인코더에 대한 투자가 필요합니다. 각 하이퍼스케일러 기업들이 2025년 AI 및 네트워크 백본을 위한 설비 투자로 750억 달러를 계상했으며, 그 일부를 다운스트림 고객이 부담해야 하기 때문에 자본 계획은 종종 예산 배분을 초과합니다. LED 비디오월만 해도 1제곱피트당 380-1,200달러에 달하므로, 대형 디스플레이는 자금력이 풍부한 조직만이 도입하기 어렵습니다. 당직 엔지니어부터 이중화 회선에 이르기까지 지속적인 운영 비용으로 인해 총 소유 비용은 더욱 부풀어 오릅니다.
부문별 분석
화상 회의 부문은 2025년에 109억 1,000만 달러의 매출을 기록하며, 기업용 비디오 시장 점유율의 41.45%를 차지했습니다. 이는 화상 회의가 표준적인 협업 수단으로 자리 잡았음을 반영합니다. 비디오 분석은 절대값으로는 작지만, 연평균 성장률(CAGR) 18.2%로 다른 모든 카테고리를 능가하는 성장이 예상되며, 2031년까지 기업용 비디오 시장 규모를 40억 달러 이상 끌어올릴 것으로 예측됩니다. 이러한 성장세는 보안, 제조, 소매 각 분야에서 이상 징후를 감지하고, 메타데이터를 추출하며, 워크플로우 자동화를 촉발하는 AI 엔진에 기인합니다.
도입 동향을 살펴보면, 과거에는 명확하게 구분되던 카테고리 간의 융합이 진행되고 있습니다. 회의 시스템 벤더는 발언자의 감정 분석 기능을 번들로 제공하고, 콘텐츠 관리 플랫폼은 하이브리드 이벤트를 지원하기 위해 라이브 스트리밍 모듈을 통합하고 있습니다. 구글의 ‘Veo 3’와 같은 AI 동영상 생성 도구는 전문 지식이 없는 사용자도 몇 초 만에 브랜드 자산을 제작할 수 있게 함으로써, 제작과 배포의 경계를 모호하게 만들고 있습니다. 그 결과, 기업들은 모놀리식 제품군 대신 오픈 API를 통해 통합되는 유연한 모듈을 선택하는 모자이크형 생태계가 형성되고 있으며, 이러한 동향이 기업용 비디오 시장의 혁신 주기를 더욱 가속화하고 있습니다.
2025년, 소프트웨어 제품은 기업용 비디오 시장 규모에서 50.92%의 점유율을 유지하며 회의, 스트리밍, 아카이빙 기능을 뒷받침했습니다. 그러나 ‘서비스’ 부문은 연평균 성장률(CAGR) 14.05%로 가장 빠르게 성장할 전망입니다. 외부 위탁을 통한 오케스트레이션, 연중무휴 24시간 모니터링 SLA, AI 튜닝 서비스는 사내에 전문 지식이 없는 조직에게 매력적입니다. 하드웨어는 인코딩, 회의실용 엔드포인트, 엣지 캐싱 분야에서 여전히 필수적이지만, 그 가치는 범용 기기에 사전 설치된 소프트웨어 정의 구성 요소로 이동하고 있습니다.
번들로 제공되는 ‘비디오-어-서비스(Video-as-a-Service)’ 제공 형태는 이러한 변화를 여실히 보여줍니다. 프로바이더는 예측 가능한 월정액 요금제 하에 관리형 인코더 랙, 트랜스코딩 소프트웨어, 분석 대시보드를 제공하며, 예방적 유지보수 및 기능 업데이트를 번들로 포함하고 있습니다. 이 모델은 총 소유 비용(TCO)을 절감하여, 지금까지 전담 비디오 팀을 구성할 타당한 이유가 없었던 중소기업을 지원합니다. 그 결과, 서비스 제공업체들은 컨설팅 부문, 인증 프로그램, 관리형 eCDN 포트폴리오를 빠르게 확장하고 있으며, 순수 소프트웨어 라이선싱 분야의 가격 경쟁이 치열해지는 상황에서도 수익성을 유지하고 있습니다.
지역별 분석
북미는 높은 광대역 보급률, SaaS의 조기 도입, 그리고 재택근무 인프라에 대한 연방 정부의 꾸준한 투자를 배경으로 2025년에는 기업용 비디오 시장의 34.05% 점유율을 확보했습니다. 대기업들이 기존 도입 환경을 최적화하고, 신규 사용자 라이선스보다 AI 애드온 및 고급 분석 기능을 우선시하게 되면서 성장은 둔화되고 있습니다. 그럼에도 불구하고, 2선 도시 주변의 엣지 가속화 노드를 통해 서비스가 미치지 않는 지역에도 저지연 스트리밍이 제공되면서 증분 수익이 유지되고 있습니다.
아시아태평양은 모바일 광대역 업그레이드와 5G 프라이빗 네트워크 시범 도입이 확대되는 가운데 연평균 성장률(CAGR) 12.6%를 기록하며 가장 빠르게 성장하는 지역입니다. 중국에서는 ‘Tencent Meeting’, 일본에서는 이토추 상사가 지원하는 ‘EasyRooms’와 같은 현지 유력 기업들이 인터페이스, 규정 준수 모듈, 언어 팩을 현지 규범에 맞추어 맞춤화하고 있습니다. 정부의 디지털화 프로그램과 제조업 현대화 노력이 검사 수준의 비디오 분석에 대한 수요를 뒷받침하고 있으며, 이로 인해 기업용 비디오 시장의 지역 내 확산이 더욱 가속화되고 있습니다.
유럽에서는 GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정) 준수 요건에 힘입어 꾸준한 성장 궤도를 그리고 있습니다. 기업들은 해당 지역 내에 데이터센터를 보유하고 엄격한 개인정보 보호 인증을 취득한 벤더를 선호하는 경향이 있으며, 이는 미국계 플랫폼과 EU 기반 클라우드 호스트 간의 협력을 촉진하고 있습니다. 남미, 중동 및 아프리카는 클라우드 우선 전략이 기존의 On-Premise 도입을 비약적으로 추월하고 있는 신흥 시장입니다. 비디오 제품군과 고속 연결을 묶어 제공하는 통신 사업자와의 제휴를 통해, 이 지역 중견 기업의 도입 장벽이 낮아지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 세분화
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the enterprise video market size is expected to grow from USD 26.32 billion in 2025 to USD 28.98 billion in 2026 and is forecast to reach USD 46.93 billion by 2031 at 10.12% CAGR over 2026-2031.
This report is Segmented by Type (Video Conferencing, Video Content Management, Webcasting and Live Streaming, Video Analytics, and Other Types), Component (Hardware, Software, and Services), Deployment (On-Premises, and Cloud), End-User Industry (BFSI, Healthcare, IT and Telecommunications, and More), Organization Size (SMEs, and Large Enterprises), and Geography.
Global Enterprise Video Market Trends and Insights
Cloud-first video architecture adoption
The migration to cloud-native stacks enables elastic scaling, API-driven integrations, and global content distribution at lower upfront cost. Enterprises retain sensitive archives on-premises yet push compute-heavy analytics to public clouds, reducing local hardware refresh cycles. Multi-cloud routing safeguards against vendor lock-in and latency variation, and it lets IT teams match diverse workloads with the optimal cost-performance region. Even so, "cloud-exit" strategies are surfacing as some firms rebalance spend toward private infrastructure when monthly egress fees outweigh elasticity benefits.
AI-powered live-caption accuracy breakthroughs
Automatic speech recognition models now deliver up to 98% precision under favorable acoustics, lifting video accessibility beyond regulatory compliance into a productivity advantage. Rich language support-spanning 140 tongues-facilitates cross-border collaboration while searchable transcripts unlock evergreen knowledge repositories. Enterprises embed these AI captions directly in content management systems to raise engagement metrics and speed content localization. The advance also fuels inclusive hiring practices because Deaf and hard-of-hearing employees access meetings in real time without third-party captioners.
High total cost of ultra-low-latency infrastructure
Enterprises seeking sub-25 millisecond round-trip performance must invest in private 5G, edge CDN nodes, and GPU-accelerated encoders. Capital plans frequently exceed budget allocations, as hyperscalers earmark USD 75 billion in 2025 capex for AI and networking backbones that downstream customers must partially absorb. LED video walls alone range between USD 380 and USD 1,200 per ft2, making large-format displays viable only for cash-rich organizations. Ongoing operational costs-from on-call engineers to redundancy circuits-further widen total cost of ownership.
Other drivers and restraints analyzed in the detailed report include:
- Growth of hybrid and remote workforces
- BYOD proliferation across enterprises
- IT staff skill shortages in video-workflow orchestration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Video Conferencing segment delivered USD 10.91 billion and held 41.45% of enterprise video market share in 2025, reflecting its entrenchment as the default collaboration medium. Video Analytics, though smaller in absolute value, is projected to outpace all other categories at an 18.2% CAGR, adding more than USD 4 billion to enterprise video market size by 2031. This momentum stems from AI engines that detect anomalies, extract metadata, and trigger workflow automations across security, manufacturing, and retail settings.
Adoption patterns reveal convergence between once-distinct categories. Conferencing vendors bundle analytics for speaker sentiment, while content-management platforms embed live-stream modules to support hybrid events. AI video generators, such as Google's Veo 3, blur production and distribution boundaries by enabling non-specialists to create branded assets in seconds. The result is a mosaic ecosystem where enterprises choose flexible modules that integrate through open APIs rather than monolithic suites, a dynamic that further accelerates innovation cycles within the enterprise video market.
Software products retained 50.92% share of enterprise video market size in 2025, underpinning meeting, streaming, and archival functions. Yet the Services category will rise fastest at a 14.05% CAGR. Outsourced orchestration, 24/7 monitoring SLAs, and AI tuning services appeal to organizations lacking in-house expertise. Hardware remains essential for encoding, room endpoints, and edge caching, but value is migrating to software-defined components pre-installed on commodity devices.
Bundled "video-as-a-service" offerings illustrate the shift. Providers supply managed encoder racks, transcoding software, and analytics dashboards under a predictable monthly fee, bundling proactive maintenance and feature updates. This model lowers total cost of ownership and supports SMEs that previously could not justify dedicated video teams. As a result, service providers are rapidly expanding consulting arms, certification programs, and managed eCDN portfolios, defending margins as pure software licensing becomes price-competitive.
Complete Report Scope:
- By Type
- Video Conferencing
- Video Content Management
- Webcasting and Live Streaming
- Video Analytics
- Other Types
- By Component
- Hardware
- Software
- Services
- By Deployment Mode
- On-Premises
- Cloud
- By End-user Industry
- BFSI
- Healthcare
- IT and Telecommunications
- Retail and E-commerce
- Education
- Government and Public Sector
- Manufacturing
- Media and Entertainment
- Others
- By Organization Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Rest of Europe
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia
- New Zealand
- Rest of Asia-Pacific
- North America
Geography Analysis
North America secured 34.05% of enterprise video market share in 2025 on the back of expansive broadband penetration, early SaaS adoption, and robust federal investment in telework infrastructure. Growth is moderating as large enterprises optimize existing deployments, prioritizing AI add-ons and advanced analytics rather than net-new seat licenses. Even so, edge acceleration nodes around tier-2 cities extend low-latency streaming into under-served areas, preserving incremental revenue.
Asia-Pacific is the fastest-growing territory, registering a 12.6% CAGR as mobile broadband upgrades and 5G private-network pilots proliferate. Indigenous champions-Tencent Meeting in China and Itochu-backed EasyRooms in Japan-tailor interfaces, compliance modules, and language packs to local norms. Government digitalization programs and manufacturing modernization efforts underpin demand for inspection-grade video analytics, further bolstering regional uptake within the enterprise video market.
Europe follows a steady trajectory shaped by GDPR compliance mandates. Enterprises gravitate toward vendors offering in-region data centers and stringent privacy certifications, driving cooperation between U.S. platforms and EU-based cloud hosts. South America plus the Middle East and Africa represent emerging footholds where cloud-first strategies leapfrog legacy on-premises rollouts. Telco partnerships that bundle video suites with high-speed connectivity lower adoption hurdles for mid-market firms across these regions.
- Cisco Systems, Inc.
- Microsoft Corporation
- Zoom Video Communications, Inc.
- Google LLC
- Adobe Inc.
- Brightcove Inc.
- IBM Corporation
- Kaltura Inc.
- Panopto
- Poly (HP Inc.)
- Avaya Inc.
- Vbrick Systems, Inc.
- Mediaplatform, Inc.
- Vidyo, Inc.
- Vimeo, Inc.
- Qumu Corporation
- Harmonic Inc.
- JW Player
- Lifesize, Inc.
- Ooyala (Telstra)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-first video architecture adoption
- 4.2.2 AI-powered live-caption accuracy breakthroughs
- 4.2.3 Growth of hybrid and remote workforces
- 4.2.4 BYOD proliferation across enterprises
- 4.2.5 Low-latency 5G private networks in campuses
- 4.2.6 Compliance-driven demand for secure archival
- 4.3 Market Restraints
- 4.3.1 High total cost of ultra-low-latency infrastructure
- 4.3.2 Inter-country data-sovereignty barriers
- 4.3.3 IT staff skill shortages in video-workflow orchestration
- 4.3.4 Rising cyber-insurance premiums on video breaches
- 4.4 Evaluation of Critical Regulatory Framework
- 4.5 Value Chain Analysis
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact Assessment of Key Stakeholders
- 4.9 Key Use Cases and Case Studies
- 4.10 Impact on Macroeconomic Factors of the Market
- 4.11 Investment Analysis
5 MARKET SEGMENTATION
- 5.1 By Type
- 5.1.1 Video Conferencing
- 5.1.2 Video Content Management
- 5.1.3 Webcasting and Live Streaming
- 5.1.4 Video Analytics
- 5.1.5 Other Types
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services
- 5.3 By Deployment Mode
- 5.3.1 On-Premises
- 5.3.2 Cloud
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 Healthcare
- 5.4.3 IT and Telecommunications
- 5.4.4 Retail and E-commerce
- 5.4.5 Education
- 5.4.6 Government and Public Sector
- 5.4.7 Manufacturing
- 5.4.8 Media and Entertainment
- 5.4.9 Others
- 5.5 By Organization Size
- 5.5.1 Small and Medium Enterprises (SMEs)
- 5.5.2 Large Enterprises
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Nordics
- 5.6.3.7 Rest of Europe
- 5.6.4 Middle East and Africa
- 5.6.4.1 Middle East
- 5.6.4.1.1 Saudi Arabia
- 5.6.4.1.2 United Arab Emirates
- 5.6.4.1.3 Turkey
- 5.6.4.1.4 Rest of Middle East
- 5.6.4.2 Africa
- 5.6.4.2.1 South Africa
- 5.6.4.2.2 Egypt
- 5.6.4.2.3 Nigeria
- 5.6.4.2.4 Rest of Africa
- 5.6.4.1 Middle East
- 5.6.5 Asia-Pacific
- 5.6.5.1 China
- 5.6.5.2 India
- 5.6.5.3 Japan
- 5.6.5.4 South Korea
- 5.6.5.5 ASEAN
- 5.6.5.6 Australia
- 5.6.5.7 New Zealand
- 5.6.5.8 Rest of Asia-Pacific
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cisco Systems, Inc.
- 6.4.2 Microsoft Corporation
- 6.4.3 Zoom Video Communications, Inc.
- 6.4.4 Google LLC
- 6.4.5 Adobe Inc.
- 6.4.6 Brightcove Inc.
- 6.4.7 IBM Corporation
- 6.4.8 Kaltura Inc.
- 6.4.9 Panopto
- 6.4.10 Poly (HP Inc.)
- 6.4.11 Avaya Inc.
- 6.4.12 Vbrick Systems, Inc.
- 6.4.13 Mediaplatform, Inc.
- 6.4.14 Vidyo, Inc.
- 6.4.15 Vimeo, Inc.
- 6.4.16 Qumu Corporation
- 6.4.17 Harmonic Inc.
- 6.4.18 JW Player
- 6.4.19 Lifesize, Inc.
- 6.4.20 Ooyala (Telstra)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


