

|
시장보고서
상품코드
2122580
온라인 약국 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)E-pharmacy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
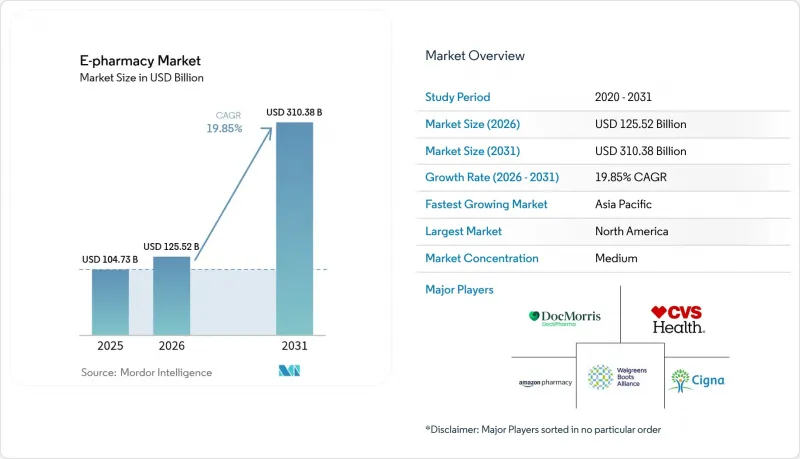
에 의하면, 온라인 약국 시장 규모는 2025년 1,047억 3,000만 달러로 평가되었습니다. 2026년에는 1,255억 2,000만 달러로 확대되어 2031년까지 3,103억 8,000만 달러에 이를 것으로 예상되고 2026년부터 2031년에 걸쳐 CAGR 19.85%로 성장할 전망입니다.

본 보고서는 약제 유형(처방약 및 일반의약품), 제품 유형(스킨케어 등), 치료 분야(당뇨병, 심혈관 질환, 호흡기 질환 등), 플랫폼(모바일 사용자 및 데스크톱 사용자), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 온라인 약국 시장 동향 및 인사이트
전자 처방전에 관한 정부 규제
미국 HTI-4와 같은 새로운 규정에 따라 2027년까지 NCPDP SCRIPT 및 실시간 급여 확인이 표준화되어 종이 문서의 번거로움이 해소될 뿐만 아니라, 이미 인증된 API를 운영 중인 플랫폼이 우대받게 될 것입니다. 그리스는 2024년에 공적 보험 환급에 있어 유사한 완전 디지털화 방침을 채택할 예정이며, EU는 2025년을 목표로 국경을 초월한 정보 교환을 추진하고 있습니다. 이러한 규제로 인해 처방전 전달 시간이 단축되고 창구에서의 처방전 포기 사례가 줄어들겠지만, 독립 약국에는 고액의 소프트웨어 업그레이드 비용 부담이 따르게 됩니다. 그 결과, 규정 준수 최소 기준을 충족함으로써 통합 비용을 상쇄할 수 있는 대규모 사업자로 시장 점유율이 이동하게 되어, 온라인 약국 시장의 통합이 더욱 가속화될 것입니다.
고령화 진행과 만성 질환의 부담
세계 60세 이상 인구는 2030년까지 14억 명에 달할 것으로 예상되며, 이는 당뇨병, 심혈관 질환, 호흡기 질환에 대한 의약품 수요를 끌어올릴 전망입니다. 자동화된 처방전 갱신 알림 및 자택 배송은 이동상의 장벽을 해소하고 복약 순응도를 향상시킬 뿐만 아니라, 가치 기반 의료 모델에서 보험사가 추적 대상으로 삼고 있는 재입원율을 감소시킵니다. LillyDirect를 통한 인슐린 자택 배송은 전문 치료, 원격 의료 및 온라인 약국의 조제 업무가 융합된 형태를 구현하고 있습니다. 이러한 동향은 지속적인 수익을 확보하는 동시에, 온라인 약국 시장을 단순한 유통 거점이 아닌 임상 파트너로서의 위상을 강화하고 있습니다.
분절화된 국제 규제 체계
EU 역내 국경을 넘는 조제 서비스의 경우, 2024년 중반 시점에서 27개국 중 12개국만이 전자 처방전 교환을 실시하고 있었기 때문에 많은 주에서 수작업에 의한 재확인 절차가 필요하게 되었습니다. 인도에서는 주별로 개별 면허 취득이 의무화되어 있으며, 이것이 2024년 PharmEasy의 기업 가치가 4억 5,800만 달러까지 급락한 원인 중 하나가 되었습니다. 미국에서는 2024년 기준에서 NABP의 VIPPS 인증 마크를 취득한 웹사이트가 고작 53개에 그쳤습니다. 이러한 불일치로 인해 도입에 소요되는 시간이 증가하고, 감사가 중복되며, 법적 리스크가 발생하여 온라인 약국 시장의 성장세가 둔화되고 있습니다.
부문별 분석
2025년에는 처방약이 온라인 약국 시장의 71.62%를 차지했으나, 2031년까지 일반의약품은 연평균 성장률(CAGR) 21.54%로 성장하여 처방약의 성장률을 상회할 전망입니다. ACNU 규정에 따라 일반의약품으로의 전환 기간이 18개월로 단축됨에 따라, 각 제약사는 스타틴 계열 약물 및 PPI(양성자 펌프 억제제)의 일반의약품 전환을 추진하고 있습니다. 앱 내 정기 구독 플랜은 재구매 장벽을 낮추고 브랜드 충성도를 강화합니다. 하지만 고가의 생물학적 제제, 특히 전문 분야의 적응증에 있어서는 처방약의 수익이 여전히 지배적이며, 온라인 약국 시장 수익의 핵심을 유지하고 있습니다.
자가 관리의 추세가 디지털화된 안내 도구와 결합됨에 따라, OTC 제품이 차지하는 온라인 약국 시장 규모는 꾸준히 확대될 것입니다. 보험사가 비처방약을 보상하는 경우는 거의 없기 때문에 가격에 대한 민감도는 여전히 지속되고 있으며, 이로 인해 구매자들은 제네릭 의약품으로 눈을 돌리고 있습니다. 처방약은 성장 속도가 둔화되고 있지만, 임상적 감독이 필요한 만성 질환에 있어 필수적이며, HTI-4에 따라 도입된 실시간 급여 확인의 혜택을 받고 있습니다.
2025년 제품 점유율에서 감기·독감 치료제는 24.85%를 차지했으나, 소비자들이 예방적 건강 관리로 전환함에 따라(3), 비타민 및 영양 보충제는 2031년까지 연평균 성장률(CAGR) 22.32%를 기록할 전망입니다. 아마존은 온라인 영양 보충제 판매의 73%를 차지하고 있으며, 추천 기능과 프라임 배송을 활용하여 월간 구독 서비스를 정착시키고 있습니다. 이러한 움직임으로 인해 온라인 약국 시장에서 아마존의 입지는 더욱 공고해지고 있습니다.
현재 전자상거래 지침에 따라 NSF 또는 USP 검사 인증 마크 표시가 의무화되어 있어, 이에 따른 규정 준수 장벽이 높아지면서 대규모 판매업체에 유리한 상황이 되고 있습니다. 면역력을 높이는 비타민, 프로바이오틱스, 식물성 단백질과 같은 ‘웰니스 스택’ 상품은 평균 주문 금액을 끌어올리고 계절적 변동을 완화합니다. 따라서 영양보충제 온라인 약국 시장 규모는 일시적인 질병과 관련된 기존의 OTC(일반의약품) 카테고리보다 빠르게 확대될 것입니다.
지역별 분석
북미는 2025년 매출의 42.65%를 차지했으며, 이는 1인당 1,300달러의 의약품 지출과 종합적인 보험 적용 범위에 힘입은 것입니다. 2024년부터 2027년에 걸쳐 CVS, 월그린, 라이트에이드의 매장 폐쇄로 인해 발생하는 접근성 격차는 아마존 파머시(Amazon Pharmacy)와 옵텀 Rx(Optum Rx)의 당일 배송 서비스로 메워질 것입니다. 미국의 HTI-4 기준에 따라 처방에 대한 장벽이 제거되고, VIPPS 인증을 통해 정식 사이트가 차별화될 것입니다. 캐나다와 멕시코는 규제가 제각각이라 뒤처지고 있지만, 캐나다에서의 국경 간 수입은 여전히 소비자들의 우회 수단이 되고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 2031년까지 연평균 성장률(CAGR)은 20.54%에 달할 전망입니다. 중국의 6억 명의 디지털 헬스 사용자가 알리바바 헬스의 2024년 매출 23억 달러와 JD 헬스의 2023년 매출 48억 달러를 견인했습니다. 인도에서는 주마다 다른 라이선스 제도로 어려움을 겪고 있으며, 타타 1mg과 아폴로 파마시가 온라인 및 오프라인 자산을 통합하는 등 업계 재편이 진행되고 있습니다. 일본에서는 고령화와 약사의 엄격한 상담이 성장을 저해하고 있는 반면, 호주의 MedAdvisor는 복약 순응도 향상을 보여주고 있어 보험사들로부터 높은 평가를 받고 있습니다.
유럽은 25%의 시장 점유율을 차지하고 있지만, 국경을 넘는 장벽에 직면해 있습니다. EU 회원국 중 전자 처방전을 원활하게 교환할 수 있는 국가는 극히 일부에 그치고 있어, 2024년 상반기에 8,480만 스위스 프랑의 손실을 기록한 DocMorris의 사업 확장에 제약을 주고 있습니다. 그리스는 2024년에 전자 처방전의 전면 도입을 의무화하여 남유럽 국가들의 모범 사례가 되고 있습니다. 영국의 NHS 앱은 오프라인 약국에서의 조제와 연계되어 있어, 온라인 전문 기업의 성장 여지는 제한적입니다. 걸프 국가들과 남아프리카공화국에서는 디지털화의 시범 운영이 진행되고 있지만, 브라질과 아르헨티나에서는 물류 및 규제의 불확실성으로 인해 그 진전이 더딘 임베디드니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the e-pharmacy market size is expected to increase from USD 104.73 billion in 2025 to USD 125.52 billion in 2026 and reach USD 310.38 billion by 2031, growing at a CAGR of 19.85% over 2026-2031.
This report is Segmented by Drug Type (Prescription Drugs and Over-The-Counter Drugs), Product Type (Skin Care, and More), Therapeutic Area (Diabetes, Cardiovascular, Respiratory, and More), Platform (Mobile Users and Desktop Users), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global E-pharmacy Market Trends and Insights
Government Mandates for Electronic Prescriptions
New rules such as the U.S. HTI-4 standardize NCPDP SCRIPT and real-time benefit checks by 2027, removing paper friction and favoring platforms that already run certified APIs. Greece took a similar all-digital stance for public reimbursement in 2024, while the EU targets cross-border exchange in 2025. These mandates compress prescription hand-off times and cut abandonment at the counter, but require independents to fund costly software upgrades. The compliance floor therefore tilts share toward scaled players that can amortize integration costs, deepening consolidation in the E-pharmacy market.
Growing Geriatric Population and Chronic Disease Burden
The world's 60-plus cohort will reach 1.4 billion by 2030, driving medication volume for diabetes, cardiovascular, and respiratory disorders. Automated refill reminders and home shipping solve mobility barriers, lifting adherence and reducing hospital readmissions that payers track under value-based care models. LillyDirect's home insulin delivery exemplifies the convergence of specialty therapy, telehealth, and E-pharmacy fulfillment. These dynamics lock in recurring revenue and reinforce the E-pharmacy market as a clinical partner rather than just a distribution node.
Fragmented International Regulatory Framework
EU cross-border dispensing requires manual re-verification in many states because only 12 of 27 countries exchanged e-prescriptions by mid-2024. India obliges separate state licences, a factor in PharmEasy's valuation crash to USD 458 million in 2024. In the United States, just 53 websites carried NABP's VIPPS seal in 2024. These mismatches add onboarding time, duplicate audits, and legal risk, trimming the E-pharmacy market growth trajectory.
Other drivers and restraints analyzed in the detailed report include:
- Strategic Collaborations Among Payers, PBMs, and E-Pharmacies
- Investments in Advanced Fulfillment and Same-Day Logistics
- Proliferation of Illegitimate Online Pharmacies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Over-the-counter medicines will rise at a 21.54% CAGR through 2031, outstripping prescription growth even though Rx products owned 71.62% E-pharmacy market share in 2025. The ACNU rule trims switch timelines to 18 months, prompting manufacturers to pursue statins and PPIs for consumer use. Subscription bundles inside apps lower refill friction and reinforce brand loyalty. Nevertheless, high-priced biologics keep prescription revenue dominant, especially for specialty indications, maintaining the revenue core of the E-pharmacy market.
The E-pharmacy market size captured by OTC products will climb steadily as self-care trends align with digitized guidance tools. Price sensitivity persists because insurers seldom cover non-prescription items, nudging shoppers toward generics. Rx drugs, while slower growing, remain essential for chronic conditions that demand clinical oversight and benefit from real-time benefit checks introduced under HTI-4.
Cold and flu remedies held 24.85% of 2025 product share, but vitamins and dietary supplements will chart a 22.32% CAGR through 2031 as consumers pivot to preventive wellness[3]. Amazon owns 73% of online supplement sales and leverages recommendations plus Prime shipping to lock in monthly subscriptions, a dynamic that deepens its stake in the E-pharmacy market.
E-commerce guidelines now compel visible NSF or USP testing badges, raising compliance thresholds that favor larger sellers. Wellness stack baskets-immune vitamins, probiotics, plant-based proteins-boost average order value and reduce seasonality. The E-pharmacy market size for supplements will therefore widen faster than legacy OTC categories tied to episodic illness.
Complete Report Scope:
- By Drug Type
- Prescription Drugs
- Over-The-Counter (OTC) Drugs
- By Product Type
- Skin Care
- Dental
- Cold & Flu
- Vitamins & Dietary Supplements
- Weight Management
- Other Product Types
- By Therapeutic Area
- Diabetes
- Cardiovascular
- Respiratory
- Gastrointestinal
- Other Therapeutic Areas
- By Platform
- Mobile Users
- Desktop Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 42.65% of 2025 revenue, driven by USD 1,300 per capita drug spend and abundant insurance coverage. Store closures by CVS, Walgreens, and Rite Aid between 2024-2027 create access gaps that Amazon Pharmacy and Optum Rx fill with same-day logistics. U.S. HTI-4 standards remove prescribing friction, and VIPPS accreditation differentiates legitimate sites. Canada and Mexico lag amid fragmented rules, though cross-border Canadian imports remain a consumer workaround.
Asia-Pacific is the fastest-growing region, with a 20.54% CAGR through 2031. China's 600 million digital health users fuel Alibaba Health's USD 2.3 billion 2024 revenue and JD Health's USD 4.8 billion 2023 revenue. India wrestles with multi-state licences, driving consolidation as Tata 1mg and Apollo Pharmacy blend online and offline assets. Japan's older demographic and strict pharmacist consultations temper growth, whereas Australia's MedAdvisor shows adherence gains that insurers reward.
Europe holds a 25% share but faces cross-border hurdles. Only a minority of EU states exchange e-prescriptions seamlessly, constraining DocMorris, which posted a CHF 84.8 million loss in H1 2024. Greece mandated full e-prescribing in 2024, offering a template for Southern Europe. The U.K.'s NHS App connects to brick-and-mortar fulfillment, limiting pure-play upside. Gulf states and South Africa pursue digital pilots, while Brazil and Argentina move slowly due to logistics and regulatory uncertainty.
- Alibaba Health Information Tech
- Alto Pharmacy
- Amazon Pharmacy (PillPack)
- Apollo Pharmacy
- Axelia Solutions (PharmEasy)
- Capsule Corp.
- Chemist Warehouse Group
- Cigna Corporation (Express Scripts)
- CVS Health
- DocMorris
- Flipkart Health+
- GoodRx Holdings Inc.
- JD Health International
- Netmeds
- NowRx
- Optum
- Phoenix Group (Germany)
- Tata 1mg
- The Kroger
- Walgreens Boots Alliance
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Mandates for Electronic Prescriptions
- 4.2.2 Growing Geriatric Population and Chronic Disease Burden
- 4.2.3 Strategic Collaborations among Payers, PBMs, and E-Pharmacies
- 4.2.4 Investments in Advanced Fulfilment and Same-Day Logistics
- 4.2.5 Integration with Digital Health and Remote Monitoring Platforms
- 4.2.6 Expansion of Direct-to-Consumer Distribution by Drug Manufacturers
- 4.3 Market Restraints
- 4.3.1 Fragmented International Regulatory Framework
- 4.3.2 Proliferation of Illegitimate Online Pharmacies
- 4.3.3 High Cold-Chain and Compliance Costs
- 4.3.4 Complex Reimbursement and Pricing Controls
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory & Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat Of New Entrants
- 4.6.2 Bargaining Power Of Buyers
- 4.6.3 Bargaining Power Of Suppliers
- 4.6.4 Threat Of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Drug Type
- 5.1.1 Prescription Drugs
- 5.1.2 Over-The-Counter (OTC) Drugs
- 5.2 By Product Type
- 5.2.1 Skin Care
- 5.2.2 Dental
- 5.2.3 Cold & Flu
- 5.2.4 Vitamins & Dietary Supplements
- 5.2.5 Weight Management
- 5.2.6 Other Product Types
- 5.3 By Therapeutic Area
- 5.3.1 Diabetes
- 5.3.2 Cardiovascular
- 5.3.3 Respiratory
- 5.3.4 Gastrointestinal
- 5.3.5 Other Therapeutic Areas
- 5.4 By Platform
- 5.4.1 Mobile Users
- 5.4.2 Desktop Users
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Alibaba Health Information Tech
- 6.3.2 Alto Pharmacy
- 6.3.3 Amazon Pharmacy (PillPack)
- 6.3.4 Apollo Pharmacy
- 6.3.5 Axelia Solutions (PharmEasy)
- 6.3.6 Capsule Corp.
- 6.3.7 Chemist Warehouse Group
- 6.3.8 Cigna Corporation (Express Scripts)
- 6.3.9 CVS Health Corporation
- 6.3.10 DocMorris (Zur Rose Group AG)
- 6.3.11 Flipkart Health+
- 6.3.12 GoodRx Holdings Inc.
- 6.3.13 JD Health International
- 6.3.14 Netmeds.com
- 6.3.15 NowRx
- 6.3.16 Optum Rx Inc.
- 6.3.17 Phoenix Group (Germany)
- 6.3.18 Tata 1mg
- 6.3.19 The Kroger Co.
- 6.3.20 Walgreens Boots Alliance
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


