|
시장보고서
상품코드
2122609
미국의 페인트 및 코팅 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Paints And Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 미국의 페인트 및 코팅 시장 규모는 2025년 364억 9,000만 달러로 평가되었고, 2026년 380억 5,000만 달러에서 2031년까지 469억 2,000만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 4.28%를 나타낼 전망입니다.
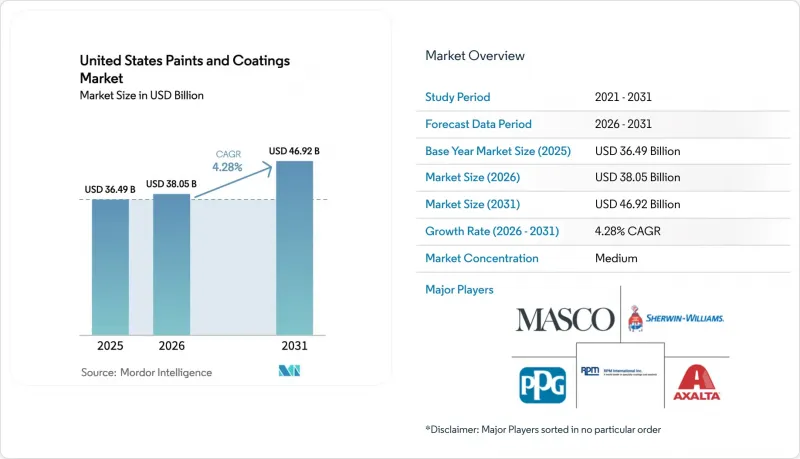
본 보고서는 수지 유형별(아크릴, 알키드, 폴리우레탄,에폭시, 폴리에스테르, 기타 수지), 기술별(수성, 용제형, 분체 도장, UV 기술), 유통 채널별(직영점 등), 최종 사용자 산업별(건축, 자동차, 목재, 보호 코팅 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국의 페인트 및 코팅 시장 동향 및 인사이트
연방 정부의 인프라 지출이 보호용 코팅을 견인
도로 및 교량에 대한 예산 배분으로 인해 아연 리치 프라이머, 에폭시 및 폴리우레탄 탑코트에 대한 수요가 견인되고 있으며, 이들 모두 25년의 내구 수명이 기대됩니다. 시공업체들은 셔윈-윌리엄스(Sherwin-Williams)사의 ‘Acrolon 680’과 같은 단층 도장 제품을 선호하고 있으며, 이를 통해 차선 폐쇄 시간이 단축될 뿐만 아니라 엄격한 SSPC 규격도 준수하고 있습니다. NORSOK 및 ISO 성능 실적을 자랑하는 공급업체들은 높은 수익률을 올리고 있으며, 중서부 지역의 철강 가공 거점에서는 교량 보수 공사 덕분에 수주가 증가하고 있습니다.
주택 리모델링 붐이 건축용 도료 시장을 견인
하버드 대학교 주택 연구 공동 센터의 예측에 따르면, 2025년 3분기까지 주택 리모델링 지출은 꾸준히 증가했으며, DIY(직접 시공) 수요의 견조함이 두드러질 전망입니다. 2024 회계연도, 홈디포는 도료 판매 호조를 보고했습니다. 이러한 매출 급증에 힘입어 홈디포는 SRS 디스트리뷰션 인수를 이어가며 전문 시공업체 대상 플랫폼 강화에 나섰습니다. 2024년, 셔윈-윌리엄스(Sherwin-Williams)는 매장 수를 늘려 사업 규모를 확대하고, 당일 배송을 위한 네트워크를 최적화했습니다. 한편, BEHR는 홈디포와의 독점적 제휴를 활용해 마스코(Masco)의 매출에 크게 기여했습니다. 도료 판매에서 전자상거래가 차지하는 비중은 여전히 미미하지만, ‘클릭 앤 콜렉트’를 통한 재주문이 현저히 증가하고 있어, 특히 업무 일정이 빡빡한 도급업자들에게 큰 이점이 되고 있습니다.
이산화티타늄(TiO2) 가격 변동이 이익률을 압박
케모어스(Chemours)와 트로녹스(Tronox)는 전 세계 이산화티타늄(TiO2) 공급의 대부분을 장악하고 있으며, 두 회사의 염소화 공정에 기반한 미국 내 생산 거점은 배합 제조업체들에게 에너지 가격 변동과 더욱 엄격해진 환경 규제의 두 가지 위험을 안겨주고 있습니다. 안료 가격은 2020년 이전 수준에 비해 여전히 높은 상태를 유지하고 있습니다. 마스코(Masco)사는 헤지 및 충전재 대체를 통해 이익률 향상에 성공했으나, 이러한 대체재의 은폐력이 떨어지기 때문에 고급 인테리어용 도료에서 탄산칼슘이나 카올린이 이산화티타늄을 어느 정도 대체할 수 있는지는 한계가 있습니다.
부문 분석
2025년, 아크릴 수지는 DIY 용도에서 낮은 냄새와 빠른 건조 특성 덕분에 미국 도료 및 코팅 시장의 수지 소비량의 36.18%를 차지했습니다. 폴리우레탄은 교량, 선박 및 산업 분야 사용자들이 내마모성과 내화학성을 우선시함에 따라 2031년까지 연평균 성장률(CAGR) 5.16%를 기록하며 다른 모든 수지를 능가할 전망입니다. 알키드 수지 수요는 VOC 규제로 인해 계속 줄어들고 있지만, 침투성 목재용 스테인에서는 여전히 중요한 역할을 하고 있습니다. 에폭시 수지는 교량 및 해상 풍력 발전에 대한 투자를 호재로 삼아, 고내구성 프라이머 및 바닥용 코팅 시장을 독점하고 있습니다. 분체 도료에 필수적인 폴리에스테르 수지는 가전제품 및 가구 생산 확대에 힘입어 수요가 증가하고 있으며, 제품의 탄소 발자국을 줄이는 BASF사의 신규 네오펜틸글리콜 공급도 이를 뒷받침하고 있습니다.
비닐, 실리콘, 불소 수지 등 기타 수지는 틈새 시장을 담당하고 있습니다. 알케마(Arkema)사가 켄튀르키예주에서 실시한 PVDF 생산 능력 증설은 자외선에 대한 내구성이 요구되는 고층 빌딩의 외벽을 뒷받침하고 있습니다. 다우(Dow)사와 와커(Wacker)사의 실리콘 수지는 배기 시스템에 내열성 마감을 가능하게 하는 반면, 불소 수지의 탑코트는 전기차 배터리 케이스를 전해액 누출로부터 보호합니다. 이처럼 개별 용도에 맞춘 고분자 구조로 인해 배합의 복잡성이 증가하여 상품화를 억제하는 동시에 전환 비용을 상승시키고 있습니다.
2025년 미국의 도료 및 코팅 시장에서 수성 시스템은 총 판매량의 68.24%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR)은 5.36%로 가장 빠른 성장이 예상됩니다. 용제형 코팅은 내습성 및 저온 분사 특성이 배출 규제로 인한 단점을 상쇄하는 항공우주, 선박, 중장비 등 틈새 분야에서 여전히 활용되고 있습니다. 용제를 포함하지 않고 95%의 전사 효율을 자랑하는 분체 도료는 금속 가구 및 가전제품 분야에서 보급이 확대되고 있는 반면, UV 경화형 도료는 순간 경화와 최소한의 에너지 소비를 특징으로 하여 목재 마루 및 포장재 시장에 침투하고 있습니다.
용도별 차이는 현저합니다. 건축 인테리어에서는 거의 모두 라텍스계가 사용되고, 자동차 OEM에서는 하이브리드 필름 스택이 사용되며, 산업용 유지보수에서는 고고형분 에폭시가 주류를 이루고 있습니다. 미국 환경보호청(EPA) 및 각 주 대기질 관리위원회의 규제 강화에 따라, 용제계 도료와 동등한 광택 및 내스크래치성을 실현할 수 있는 수성 및 UV 경화형 도료의 연구 개발 자금 투자가 지속적으로 촉진되고 있습니다. 이러한 전환을 성공적으로 이룬 제조업체는 지속가능성을 중시하는 조달 과정에서 브랜드 가치를 확립하게 될 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the United States paints and Coatings Market size is projected to expand from USD 36.49 billion in 2025 and USD 38.05 billion in 2026 to USD 46.92 billion by 2031, registering a CAGR of 4.28% between 2026 to 2031.
This report is Segmented by Resin Type (Acrylic, Alkyd, Polyurethane, Epoxy, Polyester, and Other Resin Types), Technology (Water-Borne, Solvent-Borne, Powder Coating, and UV Technology), Distribution Channel (Company-Owned Stores, and More), and End-User Industry (Architectural, Automotive, Wood, Protective Coatings, and More). The Market Forecasts are Provided in Terms of Value (USD).
United States Paints And Coatings Market Trends and Insights
Federal Infrastructure Spending Propels Protective Coatings
The allocation for roads and bridges is driving demand for zinc-rich primers, epoxies, and polyurethane topcoats, all promising a 25-year service life. Contractors are leaning towards single-coat products like Sherwin-Williams' Acrolon 680, which not only reduces lane-closure time but also adheres to strict SSPC specifications. Suppliers boasting NORSOK and ISO performance records are reaping premium margins, and steel fabrication hubs in the Midwest are witnessing a boost in orders, thanks to bridge refurbishments.
Home-Remodeling Boom Bolsters Architectural Paints
By Q3 2025, Harvard's Joint Center for Housing Studies projects residential remodeling outlays to grow steadily, underscoring the resilience of do-it-yourself (DIY) demand. In fiscal 2024, Home Depot reported strong paint sales. This surge in sales led Home Depot to bolster its pro-contractor platform, following its acquisition of SRS Distribution. In 2024, Sherwin-Williams expanded its footprint by adding more stores, optimizing its network for same-day deliveries. Meanwhile, BEHR capitalized on its exclusive partnership with Home Depot, significantly contributing to Masco's revenue. Although e-commerce accounts for a modest share of paint sales, there's a notable uptick in repeat orders through click-and-collect, particularly benefiting contractors with tight job schedules.
Volatile TiO2 Prices Pressure Margins
Chemours and Tronox control a significant portion of the global TiO2 supply, and their chlorination-based U.S. assets expose formulators to both energy swings and stricter environmental compliance. Pigment prices remain elevated compared to levels seen before 2020. While Masco has successfully enhanced its margins via hedging and substituting extenders, the diminished hiding power of these substitutes constrains the extent to which calcium carbonate or kaolin can replace TiO2 in high-end interior paints.
Other drivers and restraints analyzed in the detailed report include:
- Low-VOC Systems Gain Share Under Stricter Rules
- Automotive Recovery Lifts OEM Coatings
- Freight-Cost Inflation Strains Dealer Inventories
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, acrylics commanded 36.18% of resin consumption within the United States paints and coatings market, thanks to low odor and quick dry in DIY applications. Polyurethane is slated for a 5.16% CAGR to 2031, outpacing all other resins as bridge, marine, and industrial users prioritize abrasion and chemical resistance. Alkyd demand keeps shrinking under VOC curbs, yet remains relevant for penetrating wood stains. Epoxy dominates heavy-duty primers and floor coatings, benefiting from bridge and offshore wind investments. Polyester, integral to powder coatings, gains from appliance and furniture output, aided by BASF's new neopentyl glycol supply that lowers product carbon footprints.
Other chemistries, such as vinyl, silicone, and fluoropolymers, fill niche roles. Arkema's PVDF capacity addition in Kentucky supports high-rise facades that need ultraviolet durability. Silicone resins from Dow and Wacker enable heat-stable finishes on exhaust systems, while fluoropolymer topcoats protect EV battery casings against electrolyte spills. Tailored polymer architectures therefore multiply formulation complexity, discouraging commoditization and raising switching costs.
Water-borne systems accounted for 68.24% of the 2025 volume in the United States paints and coatings market and exhibit the swiftest 5.36% CAGR outlook to 2031. Solvent-borne coatings still serve aerospace, marine, and heavy-equipment niches where humidity tolerance and cold-spray properties outweigh emission penalties. Powder coatings, free of solvents and offering 95% transfer efficiency, advance in metal furniture and appliances, while UV-curable coatings penetrate wood flooring and packaging thanks to instant cure and minimal energy use.
End-use variation is stark: architectural interiors are nearly all latex, automotive OEM uses hybrid film stacks, and industrial maintenance leans on high-solids epoxies. Regulatory clamp-downs by the EPA and state air-quality boards continue to push research and development funds toward water-borne and UV chemistries that can match solvent-borne gloss and mar resistance. Manufacturers that master these conversions secure brand equity in sustainability-driven procurement.
Complete Report Scope:
- By Resin Type
- Acrylic
- Alkyd
- Polyurethane
- Epoxy
- Polyester
- Other Resin Types
- By Technology
- Water-borne
- Solvent-borne
- Powder Coating
- UV Technology
- By Distribution Channel
- Company-Owned Stores
- Independent Paint Dealers
- Big-Box Retailers and Home Centers
- Direct to Industrial OEM
- E-Commerce
- By End-user Industry
- Architectural
- Automotive
- Wood
- Protective Coatings
- General Industrial
- Transportation
- Packaging
List of Companies Covered in this Report:
- Akzo Nobel N.V.
- Axalta Coating Systems, LLC
- BASF
- Beckers Group
- Benjamin Moore & Co.
- Carboline
- Diamond Vogel
- Dunn-Edwards Corporation
- Hempel A/S
- ICP Group
- Kelly-Moore Paint Company
- Masco Corporation
- Nippon Paint Holdings Co., Ltd.
- Parker Hannifin
- PPG Industries, Inc.
- RPM International Inc.
- Rust-Oleum Corporation
- Sika AG
- The Sherwin-Williams Company
- Tnemec
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Federal Infrastructure and Jobs Act boosts bridge/highway coatings
- 4.2.2 Home-remodeling boom lifts DIY architectural demand
- 4.2.3 Shift to water-borne and UV-curable systems to meet VOC rules
- 4.2.4 Automotive production rebound raises OEM and refinish volumes
- 4.2.5 Antimicrobial coatings adoption in healthcare facilities
- 4.3 Market Restraints
- 4.3.1 Volatile TiO2 prices compress margins
- 4.3.2 Shortage of certified industrial painters delays projects
- 4.3.3 Freight-cost inflation disrupts retailer inventory cycles
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Acrylic
- 5.1.2 Alkyd
- 5.1.3 Polyurethane
- 5.1.4 Epoxy
- 5.1.5 Polyester
- 5.1.6 Other Resin Types
- 5.2 By Technology
- 5.2.1 Water-borne
- 5.2.2 Solvent-borne
- 5.2.3 Powder Coating
- 5.2.4 UV Technology
- 5.3 By Distribution Channel
- 5.3.1 Company-Owned Stores
- 5.3.2 Independent Paint Dealers
- 5.3.3 Big-Box Retailers and Home Centers
- 5.3.4 Direct to Industrial OEM
- 5.3.5 E-Commerce
- 5.4 By End-user Industry
- 5.4.1 Architectural
- 5.4.2 Automotive
- 5.4.3 Wood
- 5.4.4 Protective Coatings
- 5.4.5 General Industrial
- 5.4.6 Transportation
- 5.4.7 Packaging
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Axalta Coating Systems, LLC
- 6.4.3 BASF
- 6.4.4 Beckers Group
- 6.4.5 Benjamin Moore & Co.
- 6.4.6 Carboline
- 6.4.7 Diamond Vogel
- 6.4.8 Dunn-Edwards Corporation
- 6.4.9 Hempel A/S
- 6.4.10 ICP Group
- 6.4.11 Kelly-Moore Paint Company
- 6.4.12 Masco Corporation
- 6.4.13 Nippon Paint Holdings Co., Ltd.
- 6.4.14 Parker Hannifin
- 6.4.15 PPG Industries, Inc.
- 6.4.16 RPM International Inc.
- 6.4.17 Rust-Oleum Corporation
- 6.4.18 Sika AG
- 6.4.19 The Sherwin-Williams Company
- 6.4.20 Tnemec
- 6.4.21 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Self-Healing Protective Coatings for Offshore Wind Infrastructure