|
시장보고서
상품코드
2122667
정전용량식 센서 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Capacitive Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
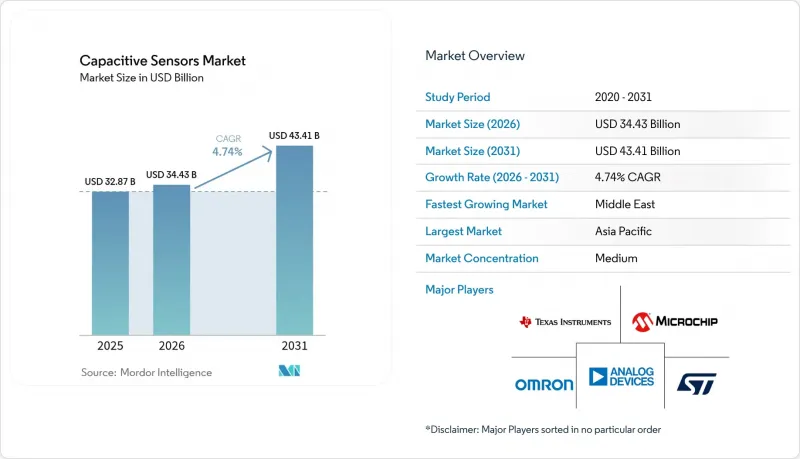
에 의하면, 정전용량식 센서 시장 규모는 2025년에 328억 7,000만 달러로 평가되었습니다. 2026년 344억 3,000만 달러에서 2031년까지 434억 1,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 4.74%를 나타낼 전망입니다.

본 보고서는 유형별(터치 센서, 모션 센서, 기타), 최종 사용자 산업별(가전, 자동차, 기타),감지 원리(자기 정전용량식, 상호 정전용량식, 표면 정전용량식, 기타), 폼 팩터(표면 실장형 센서, 스루홀형 센서, 연질·박막형 센서, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 정전용량식 센서 시장 동향 및 인사이트
가전제품에서의 정전용량식 터치스크린 채택 확대
스마트폰, 태블릿, 웨어러블 기기 제조업체들은 저항막 방식 기술에서 고도의 상호 정전용량 방식 및 투영형 정전용량 방식으로의 전환을 지속하고 있습니다. Samsung Electronics가 2024년에 가동을 시작한 연성 OLED 생산 라인에서는 투영형 정전용량 방식이 채택되어, 굽힘 반경 전체에 걸쳐 균일한 감도를 유지하는 폴더블 디스플레이의 구현이 가능해졌습니다. 자동차 제조업체들도 인포테인먼트 유닛,스티어링 휠 조작부, 증강현실(AR) 헤드업 디스플레이에서 유사한 아키텍처를 채택하고 있습니다. 이러한 설계상의 선택으로 차량 1대당 평균 정전용량식 센서 탑재 수가 증가하여, 산업용 기계나 백색 가전까지 파급되는 규모의 경제가 촉진되고 있습니다. 한편, 유리 아래에 내장된 햅틱 드라이버를 통해 평평한 표면에서 촉각을 통한 확인이 가능해져, 오작동이 감소함과 동시에 시각 장애가 있는 사용자에 대한 접근성이 향상되고 있습니다. 따라서 각 벤더사는 OEM이 새로운 하드웨어 개량을 필요로 하지 않고도 지연 시간 미세 조정, 임계값 설정, 멀티핑거 제스처 구현을 수행할 수 있는 펌웨어 툴킷 제공을 우선시하고 있습니다.
자동차용 인간-기계 인터페이스(HMI)에서 정전용량식 센서 통합의 진전
2024년에 갱신된 Euro NCAP 안전 프로토콜에서는 정전용량식 채널을 통해 운전자의 주의 상태를 추적하는 스티어링 휠 그립 센서가 평가 대상이 되었으며, 이에 따라 Tier 1 공급업체는 자동차용 컨트롤러를 AEC-Q100 규격에 부합하도록 해야 합니다. 테슬라와 BMW는 운전자가 장갑을 착용한 상태에서도 정전용량식 센서 어레이가 ‘핸드 온 휠(Hand on Wheel)’ 상태를 확실하게 감지할 수 있음을 입증했으며, 이는 레벨 2 이상의 자율 주행을 위해 매우 중요한 기능입니다. 또한 정전용량식 표면은 외부 충전 포트 도어나 차량 내 간접 조명용 슬라이더에도 채택되기 시작하여, 먼지가 쉽게 유입되는 기계식 스위치를 대체하고 있습니다. 전동 파워트레인의 보급에 따라 자동차의 전자기 간섭(EMI) 수준이 상승하고 있으므로, 각 공급업체들은 현재 내성을 유지하기 위해 차동 감지와 스펙트럼 확산 변조를 결합하고 있습니다. 이 부문의 제품 수명 주기가 길기 때문에 인증된 센서 IC는 수년에 걸쳐 수익원을 확보하고 있으며, 자동차 부문에의 통합은 정전용량식 센서 시장에 매우 큰 전략적 영향을 미치고 있습니다.
인듐-주석 산화물(ITO)공급 부족 및 가격 변동
2024년, 지정학적 긴장에 따른 공급망 문제로 인해 중국과 한국의 채굴 사업이 혼란을 겪으면서 인듐 가격은 40% 이상 변동했습니다. 동일한 금속을 놓고 경쟁하는 디스플레이 제조업체들의 존재가 공급 부족을 더욱 심각하게 만들었고, 센서 공급업체들은 리드타임을 연장하고 재고를 늘릴 수밖에 없었습니다. 고분자 도체나 은 나노와이어는 잠재적인 해결책이 될 수 있지만, 대량 생산되는 터치스크린 오버레이에 적용하는 데는 여전히 비용이 듭니다. 일부 OEM은 투명 전도체의 면적을 줄이기 위해 사용자 인터페이스를 재설계했으나, 이러한 타협은 제스처 조작 영역이나 브랜드 차별화를 제한하게 됩니다. 따라서 대체 소재가 성숙해질 때까지 전략적 비축이나 다중 공급처와의 계약은 일시적인 대응책에 그칠 것입니다.
부문별 분석
터치 센서 하위 부문은 스마트폰 및 태블릿에 대한 꾸준한 수요에 더해, 카운터탑 가전제품에의 탑재가 증가함에 따라 2025년 정전용량식 센서 시장에서 44.02%의 매출 점유율을 유지했습니다. 이러한 우위 덕분에 안정적인 물량이 확보되어 웨이퍼 수준의 비용 절감을 이끌고 있습니다. 그 결과, 터치 IC는 교육용 태블릿이나 보급형 자동차 등 가격에 민감한 시장으로의 진출이 가능해졌습니다. 또한, 터치 센서는 화학적 멸균을 견뎌야 하는 의료용 모니터에서도 보급이 확대되고 있으며, 유리나 폴리머 오버레이가 정밀도를 저하시키지 않으면서 전극을 보호하고 있습니다. 한편, 개발자들은 회의 시스템에 사용되는 대형 패널에서 고스트 터치를 최소화하기 위해 펌웨어에 팜 리젝션 로직을 구현하고 있습니다.
근접 센서는 가장 빠른 성장세를 보이고 있으며, 비접촉식 엘리베이터 패널과 병실 제어 장치가 표준화됨에 따라 2031년까지 연평균 성장률(CAGR) 5.03%로 확대될 것으로 전망됩니다. 이 하위 부문은 정전용량 필드를 활용하여 비전도성 층을 투과하여 물체를 감지하기 때문에 광학 프로브가 흐려져 작동하지 않게 되는 제약용 용기 내의 액면 레벨 모니터링을 가능하게 합니다. 신규 포장 라인에서는 충전기 주변에 근접 센서 어레이를 통합하여 작업자의 팔이 안전 구역에 침입할 경우 작동을 정지시킴으로써 ISO 13849 준수성을 향상시키고 있습니다. 모션 센서와 위치 센서는 단위 부피는 작지만, 가상현실(VR) 컨트롤러나 정밀 로봇 공학과 같은 수익성이 높은 틈새 시장에서 활용되고 있으며, 5마이크로미터 이하의 양방향 분해능이 필요한 부문에서는 이익률이 30%를 초과합니다.
2025년 정전용량식 센서 시장에서 가전제품이 40.35%를 차지했습니다. 이는 디스플레이 입력, 사이드 키 대체, 카메라 AF 모듈용으로 최대 5개의 독립형 정전용량식 솔루션을 탑재한 휴대전화가 주도하고 있습니다. 포화 상태에 이른 지역에서는 성장이 정체되고 있지만, 폴더블이나 롤러블과 같은 새로운 폼 팩터가 교체 주기를 활성화시키고 있습니다. 게임기에서는 모션 트래킹을 위해 대면적 정전용량식 패널이 채택되어 한 자릿수 중반대의 성장률을 유지하고 있습니다.
헬스케어 부문은 연평균 성장률(CAGR) 4.82%로 가장 높은 성장 궤적을 기록하고 있습니다. 코로나19 위기에 대응해 마련된 규제 체계에 따라 인공호흡기, 환자용 단말기, 검사 장비에는 비접촉식 또는 닦아내기 쉬운 사용자 인터페이스가 의무화되었습니다. PET 필름 아래에 내장된 정전용량식 버튼은 IP67 규격을 준수하여, 기계적 열화를 초래하지 않으면서 철저한 소독이 가능합니다. 또한 병원에서는 병원체 전파를 방지하기 위해 중환자실 외부에 정전용량식 손 제스처 패널을 도입하고 있습니다. 자동차 부문은 여전히 중요한 위치를 차지하고 있으며, 전기차에는 정전용량식 충전 포트 커버와 좌석 점유 감지 기능이 추가되었습니다. 한편, 항공우주 부문에서는 조종실 현대화 프로그램을 위해 방사선 내성 부품이 요구되고 있습니다.
지역별 분석
아시아태평양은 중국의 수직 통합형 디스플레이 및 스마트폰 공급망에 힘입어 2025년 전 세계 매출의 39.05%를 차지했습니다. 한국의 패널 제조업체들은 폴더블 OLED 생산을 확대하고 있으며, 이는 투영형 정전용량식 컨트롤러에 대한 지역적 수요를 견인하고 있습니다. 한편, 대만의 EMS 공급업체들은 노트북 시장의 회복을 뒷받침하기 위해 전략적인 웨이퍼 할당을 확보하고 있습니다. 인도의 반도체 패키징에 대한 우대 조치로 인해 다국적 IDM 기업들이 범프 가공 및 테스트 체계를 구축하게 되었으며, 이로 인해 국내 가전 브랜드들이 현지에서 생산된 센서 IC를 채택할 수 있는 길이 열렸습니다. 일본의 로봇 산업은 특히 서브미크론 단위의 제어가 필수적인 반도체 리소그래피 스테이지용으로, 고정밀 위치 센서의 주요 구매자로 자리매김하고 있습니다.
북미에서는 자동차, 항공우주, 의료용 전자기기 각 부문에서 꾸준한 보급이 이루어지고 있습니다. 미국의 전기차 제조업체들은 800V 급속 충전 중 발생하는 EMI 버스트에 내성이 있는 스티어링 휠용 터치 센서를 사양으로 규정하고 있으며, 디트로이트의 1차 자동차 부품 제조업체와 실리콘밸리의 스타트업 기업 간의 협력을 촉진하고 있습니다. 캐나다의 의료기기 제조업체는 치과용 기기의 ‘갭 없는’ 세척 규정을 준수하기 위해 투영형 정전용량 방식을 채택하고 있습니다. 유럽은 성숙도 면에서 북미와 어깨를 나란히 하고 있지만, 순환형 경제 규칙 등 지속가능성에 관한 규제를 배경으로, 접착식 저항막 방식 터치 필름이 아닌 수리 가능한 정전용량식 패널에 대한 수요가 증가하고 있습니다.
중동은 2031년까지 4.98%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다. 아랍에미리트의 스마트 시티 계획에서는 조명 기둥에 정전용량식 재실 센서를 내장하여 교통량이 적은 시간대의 에너지 소비를 조절하고 있습니다. 사우디아라비아의 ‘비전 2030’ 산업 단지에서는 포장 및 충전 라인에 위생적이고 비접촉식 제어 시스템을 도입하고 있습니다. 남미에서는 브라질의 자동차 공장이 국내 전기차 출시를 대비해 충전 포트 덮개를 정전용량식으로 교체하고 있어 시장이 완만하게 성장하고 있습니다. 아프리카는 여전히 개발도상국 단계이지만, 나이지리아의 핀테크 키오스크에서는 먼지와 높은 습도를 견딜 수 있는 견고한 터치 표면에 대한 초기 수요가 나타나고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the capacitive sensor market size was valued at USD 32.87 billion in 2025 and estimated to grow from USD 34.43 billion in 2026 to reach USD 43.41 billion by 2031, at a CAGR of 4.74% during the forecast period (2026-2031).
This report is Segmented by Type (Touch Sensor, Motion Sensor, and More), End-User Industry (Consumer Electronics, Automotive, and More), Sensing Principle (Self-Capacitance, Mutual Capacitance, Surface Capacitance, and More), Form Factor (Surface-Mount Sensors, Through-Hole Sensors, Flexible/Thin-Film Sensors, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Capacitive Sensors Market Trends and Insights
Growing Adoption of Capacitive Touch Screens in Consumer Electronics
Smartphone, tablet, and wearable device makers continue to replace resistive technologies with advanced mutual and projected capacitance. Flexible OLED production lines commissioned by Samsung in 2024 integrate projected capacitance to enable foldable displays that maintain uniform sensitivity across bending radii. Automakers embrace the same architectures for infotainment units, steering-wheel controls, and augmented-reality head-up displays. These design choices enhance the average capacitive sensor content per vehicle, fostering volume economies that extend to industrial machinery and white goods. Meanwhile, haptic drivers embedded beneath glass enable tactile confirmation on flat surfaces, reducing accidental activations and improving accessibility for visually impaired users. Vendors are therefore prioritizing firmware toolkits that allow OEMs to fine-tune latency, set thresholds, and implement multi-finger gestures without requiring new hardware spins.
Increasing Integration of Capacitive Sensors in Automotive Human-Machine Interfaces
Euro NCAP safety protocols, updated in 2024, evaluate steering-wheel grip sensors that track driver attention through capacitive channels, driving tier-one suppliers to certify automotive-grade controllers to AEC-Q100 standards. Tesla and BMW have demonstrated that capacitive sensor arrays can reliably detect hands-on-wheel conditions, even when operators wear gloves a critical feature for Level 2+ autonomy. Capacitive surfaces are also appearing on exterior charge-port doors and interior ambient-lighting sliders, replacing mechanical switches that are susceptible to dust ingress. Because automotive EMI levels rise with electrified powertrains, suppliers now bundle differential sensing and spread-spectrum modulation to maintain immunity. Long product life cycles in the sector lock in multiyear revenue streams for qualified sensor ICs, giving automotive integrations an outsized strategic impact on the capacitive sensor market.
Supply Shortage and Price Volatility of Indium Tin Oxide
Indium prices fluctuated by more than 40% in 2024 as mining operations in China and South Korea were disrupted by supply chain issues amid geopolitical tensions. Display manufacturers competing for the same metal exacerbated scarcity, forcing sensor vendors to lengthen lead times and carry higher inventories. Polymer conductors and silver nanowires offer potential relief but remain expensive to scale for high-volume touchscreen overlays. Some OEMs redesigned user interfaces to reduce transparent conductor area, but such compromises limit gesture zones and brand differentiation. Strategic stockpiling and multi-sourcing contracts are, therefore, temporary stopgaps until alternative materials mature.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Industrial Automation and Robotics
- Growth of Wearable and IoT Devices Requiring Low Power Capacitive Sensing
- Sensitivity to Electromagnetic Interference in Industrial Environments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The touch-sensor subsegment retained a 44.02% revenue share within the capacitive sensor market in 2025, thanks to entrenched demand for smartphones and tablets, combined with rising installations in countertop appliances. This dominance provides stable volumes that drive wafer-level cost declines, permitting touch ICs to enter price-sensitive markets such as education tablets and entry-level cars. Touch sensors also proliferate in medical-grade monitors that must withstand chemical sterilization, where glass or polymer overlays protect electrodes without compromising accuracy. Meanwhile, developers enrich firmware with palm-rejection logic to minimize ghost touches on large panels used in conference systems.
Proximity sensors exhibit the swiftest momentum, expanding at a 5.03% CAGR to 2031 as contactless elevator panels and hospital room controls become standard. The subsegment leverages capacitive fields to detect objects through non-conductive layers, enabling liquid-level monitoring in pharmaceutical vessels where optical probes cloud over. Emerging packaging lines integrate proximity arrays around fillers to halt operation if an operator's arm breaches safety envelopes, improving compliance with ISO 13849. Motion and position sensors, although smaller in unit volume, find profitable niches in virtual-reality controllers and precision robotics, where bidirectional resolution of under 5 µm commands margins exceed 30%.
Consumer electronics accounted for 40.35% of the capacitive sensor market in 2025, anchored by mobile phones that package up to five separate capacitive solutions for display input, side-key replacement, and camera AF modules. Growth is plateauing in saturated geographies, but new form factors, such as foldables and rollables, refresh replacement cycles. Gaming consoles utilize large surface capacitive panels for motion tracking, sustaining mid-single-digit growth.
Healthcare registers the highest forward trajectory at 4.82% CAGR. Regulatory frameworks that emerged in response to the COVID-19 crisis mandate touchless or wipe-friendly user interfaces for ventilators, patient terminals, and laboratory equipment. Capacitive buttons sealed under PET films meet IP67 standards, allowing for aggressive disinfection without mechanical degradation. Hospitals also deploy capacitive hand-gesture panels outside intensive-care rooms to reduce pathogen transfer. Automotive retains its historical importance, with electric cars adding capacitive charge-port lids and seat-occupancy detection, while aerospace seeks radiation-hardened parts for cockpit modernization programs.
Complete Report Scope:
- By Type
- Touch Sensor
- Motion Sensor
- Position Sensor
- Proximity Sensor
- Other Types
- By End-User Industry
- Consumer Electronics
- Automotive
- Aerospace and Defense
- Healthcare
- Food and Beverages
- Oil and Gas
- Industrial Machinery
- Other End-User Industry
- By Sensing Principle
- Self-Capacitance
- Mutual Capacitance
- Surface Capacitance
- Projected Capacitance
- By Form Factor
- Surface-Mount Sensors
- Through-Hole Sensors
- Flexible/Thin-Film Sensors
- Embedded IC Sensors
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific retained 39.05% of global revenue in 2025, anchored by China's vertically integrated display and smartphone supply chains. South Korea's panel makers scale up foldable OLED production, driving localized demand for projected-capacitance controllers, while Taiwan's EMS providers secure strategic wafer allocations to support the notebook rebound. India's incentives for semiconductor packaging have attracted multinational IDMs to establish bumping and test capacity, opening pathways for domestic appliance brands to adopt local sensor ICs. Japan's robotics sector remains a premium buyer of high-accuracy position sensors, especially for semiconductor lithography stages where sub-micron control is compulsory.
North America demonstrates steady adoption across the automotive, aerospace, and medical electronics sectors. U.S. electric-vehicle makers specify steering-wheel touch sensors that resist EMI bursts generated during 800-V fast charging, fostering collaboration between Detroit's tier-one automakers and Silicon Valley startups. Canadian medical device firms are embracing projected capacitance to meet no-gap cleaning regulations for dental equipment. Europe parallels North America in maturity but channels sustainability mandates-such as circular-economy rules-into a demand for reparable capacitive panels rather than glued-in resistive touch films.
The Middle East is expected to record the fastest 4.98% CAGR through 2031. Smart-city programs in the United Arab Emirates integrate capacitive occupancy sensors within lighting poles to modulate energy consumption during periods of low traffic. Saudi Arabia's Vision 2030 industrial zones are outfitting packaging and bottling lines with hygienic, touchless controls. South America grows moderately as Brazilian automotive plants upgrade to capacitive charge-port lids for domestic electric vehicle launches. Africa remains nascent, but fintech kiosks in Nigeria demonstrate early demand for robust touch surfaces that can withstand dust and high humidity.
- Texas Instruments Incorporated
- STMicroelectronics N.V.
- Analog Devices Inc.
- Microchip Technology Inc.
- Omron Corporation
- Infineon Technologies AG
- NXP Semiconductors N.V.
- Fujitsu Limited
- 3M Company
- Siemens AG
- Sony Group Corporation
- TDK Corporation
- ROHM Co., Ltd.
- Synaptics Incorporated
- Cypress Semiconductor Corporation (Infineon)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of Capacitive Touch Screens in Consumer Electronics
- 4.2.2 Increasing Integration of Capacitive Sensors in Automotive Human Machine Interfaces
- 4.2.3 Rising Demand for Industrial Automation and Robotics
- 4.2.4 Growth of Wearable and IoT Devices Requiring Low Power Capacitive Sensing
- 4.2.5 Emergence of Transparent Conductive Polymers as Alternative to Indium Tin Oxide
- 4.2.6 Regulatory Push for Hygienic Contactless Interfaces in Food Processing and Healthcare
- 4.3 Market Restraints
- 4.3.1 Supply Shortage and Price Volatility of Indium Tin Oxide
- 4.3.2 Sensitivity to Electromagnetic Interference in Industrial Environments
- 4.3.3 Patent Thickets Around Multi-Touch Algorithms Increasing Licensing Costs
- 4.3.4 Limitations in Detecting Gloved Touches in Harsh Environments
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Regulatory Landscape
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Touch Sensor
- 5.1.2 Motion Sensor
- 5.1.3 Position Sensor
- 5.1.4 Proximity Sensor
- 5.1.5 Other Types
- 5.2 By End-User Industry
- 5.2.1 Consumer Electronics
- 5.2.2 Automotive
- 5.2.3 Aerospace and Defense
- 5.2.4 Healthcare
- 5.2.5 Food and Beverages
- 5.2.6 Oil and Gas
- 5.2.7 Industrial Machinery
- 5.2.8 Other End-User Industry
- 5.3 By Sensing Principle
- 5.3.1 Self-Capacitance
- 5.3.2 Mutual Capacitance
- 5.3.3 Surface Capacitance
- 5.3.4 Projected Capacitance
- 5.4 By Form Factor
- 5.4.1 Surface-Mount Sensors
- 5.4.2 Through-Hole Sensors
- 5.4.3 Flexible/Thin-Film Sensors
- 5.4.4 Embedded IC Sensors
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Texas Instruments Incorporated
- 6.4.2 STMicroelectronics N.V.
- 6.4.3 Analog Devices Inc.
- 6.4.4 Microchip Technology Inc.
- 6.4.5 Omron Corporation
- 6.4.6 Infineon Technologies AG
- 6.4.7 NXP Semiconductors N.V.
- 6.4.8 Fujitsu Limited
- 6.4.9 3M Company
- 6.4.10 Siemens AG
- 6.4.11 Sony Group Corporation
- 6.4.12 TDK Corporation
- 6.4.13 ROHM Co., Ltd.
- 6.4.14 Synaptics Incorporated
- 6.4.15 Cypress Semiconductor Corporation (Infineon)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment