|
시장보고서
상품코드
2122673
자동차 스티어링 휠 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Steering Wheel - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 자동차 스티어링 휠 시장 규모는 2025년 349억 8,000만 달러로 평가되었습니다. 2026년에는 364억 1,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 4.08%로 성장을 지속하여, 2031년에는 444억 7,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 기술별(기존 컬럼 스티어링, 기타), 소재 유형별(알루미늄 림, 마그네슘 림, 기타),차종별(승용차, 소형 상용차, 기타), 유통 채널별(OEM 순정, 애프터마켓용 교체 부품), 추진 방식별(내연기관, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 자동차 스티어링 휠 시장 동향 및 인사이트
스티어 바이 와이어(SbW) 플랫폼의 급속한 보급
메르세데스-벤츠는 ZF의 컬럼리스 아키텍처를 채택한 NIO의 ET9가 2025년에 출시되는 데 이어, 2026년 EQS에 완전한 SBW를 도입할 예정입니다. 이 기술로 인해 기계적 연결부가 제거되고, 가변 기어비 및 소프트웨어를 통한 피드백 조정이 가능해져 도심 주행 시 조작성과 고속 주행 시 안정성이 향상됩니다. ZF는 여러 OEM과 계약을 체결했으며, 이는 2030년까지 SBW 하드웨어의 연평균 성장률(CAGR) 7.90%를 뒷받침하고 있습니다. 이러한 전환으로 소프트웨어 정의 섀시 제어가 가능해지는 한편, 기존 공급업체들에게는 전자 기술 및 사이버 보안 역량 구축이 요구되고 있습니다. 중국에서의 초기 성공 사례는 규제 당국이 이 아키텍처에 대한 형식 승인을 할 의향을 시사하고 있어, 전 세계적인 보급을 가속화하고 있습니다.
스티어링 휠에 전면 에어백 장착 의무화
2024년 7월에 발효된 EU 일반 안전 규정 II(General Safety Regulation II)는 긴급 제동 기능과 졸음 경고 기능의 강화를 의무화하고 있으며, 이에 따라 스티어링 휠의 설계가 재구성될 것입니다. 미국에서는 NHTSA가 DADSS 프로그램의 일환으로 운전자의 기능 저하를 감지하기 위한 조사를 진행하고 있으며, 이때 림에 내장된 촉각 센서가 사용되고 있습니다. ZF LIFETEC은 미관과 충돌 성능을 모두 충족시키며, 더욱 엄격해진 패키징 제한을 만족하는 상단 전개식 에어백을 개발했습니다. 규제의 통합으로 인해 시스템의 복잡성과 통합 비용은 증가하지만, 전 세계적 요건이 표준화됨에 따라 1차 공급업체에게는 양산에 따른 규모의 경제 효과가 발생합니다.
알루미늄·마그네슘 가격 변동
2024년부터 2025년에 걸쳐 알루미늄과 마그네슘의 현물 가격은 20% 이상 변동하여 경량 림과 스포크의 이익률을 압박하고 있습니다. 공급업체들은 장기 공급 계약이나 합금 대체를 통해 위험을 헤지하고 있지만, 비용의 급등으로 인해 비용에 민감한 부문에서의 채택이 저해되고 있습니다. 각 OEM 업체들은 가격 변동을 상쇄하기 위해 재생 원료의 활용을 모색하고 있으나, Tier 2 파운드리은 여전히 원자재 위험에 노출되어 있습니다.
부문별 분석
2025년, 자동차 스티어링 휠 시장에서 EPS(전동 파워 스티어링)가 37.86%의 점유율을 차지했습니다. 이는 OEM 업체들이 효율성과 ADAS(첨단 운전자 지원 시스템) 대응을 목적으로 유압 시스템에서 전동 보조 시스템으로 업그레이드했기 때문입니다. 저비용과 기계적 단순성을 우선시하는 시장에서는 기존 컬럼 스티어링이 여전히 주류를 이루고 있습니다. 스티어 바이 와이어는 여전히 틈새 시장으로 남아 있지만, 프리미엄 전기차의 출시와 자율주행 프로그램의 진전에 힘입어 2031년까지 연평균 성장률(CAGR) 7.66%를 나타낼 것으로 예측됩니다.
자동차 스티어링 휠 시장 규모에서 EPS가 차지하는 큰 비중은 현재의 전동화를 뒷받침하고 있는 반면, SbW는 레벨 3 이상의 핸즈프리 주행 모드에 활용될 기반을 마련하고 있습니다. ZF의 ET9 계약은 유압작동유를 사용하지 않고 가변 비와 소프트웨어 정의 조작감을 실현함으로써 상업적 실현 가능성을 입증하고 있습니다. 상용 트럭의 경우, EPS 유닛은 최대 8,000Nm의 토크를 공급하면서도 유압 펌프에 비해 에너지 소비를 줄여, 그 효율성의 우위를 입증하고 있습니다.
2차적인 영향이 공급업체의 입지를 형성하고 있습니다. EPS 유닛은 차선 유지 및 자동 주차 기능에 정보를 제공하는 통합형 토크 센서에 의존하고 있어, 이로 인해 저비용 진출기업의 진입 장벽이 높아지고 있습니다. SbW 아키텍처는 수납식 스티어링 칼럼을 위한 새로운 공간을 창출하여 거실과 같은 실내 공간 콘셉트를 실현합니다. 고대역폭 CAN-FD 및 이더넷 기반 도메인 컨트롤러의 통합으로 섀시와 인포테인먼트 영역 간의 경계가 더욱 모호해졌으며, 기존 컬럼 전문 제조업체가 아닌 소프트웨어 통합업체에 새로운 비즈니스 기회가 생겨나고 있습니다.
2025년 자동차 스티어링 휠 시장에서 알루미늄은 37.12%의 점유율을 유지하며 계속해서 주도적인 위치를 차지했습니다. 이는 40%의 경량화와 무한한 재활용 가능성 덕분입니다. 강철은 내구성이 무게보다 우선시되는 대형 차량용 플리트에서 여전히 주류를 이루고 있습니다. 마그네슘 림은 고성능 틈새 시장용이지만, 가공 및 부식과 관련된 비용 문제에 직면해 있습니다. 천연섬유 복합재, 특히 대마와 아마는 자동차 제조업체의 ‘크래들-투-게이트’ CO₂ 감축 목표에 힘입어 2031년까지 연평균 성장률(CAGR) 7.42%로 성장할 전망입니다. 쿠플라의 ‘ampliTex’ 시트백은 탄소섬유에 비해 CO2 배출량을 49% 줄였으며, 이는 내장 부품 분야에서 확장성의 가능성을 보여줍니다.
자동차 스티어링 휠 시장에서는 알루미늄 골격에 바이오 복합재 표피를 결합함으로써, 구조적 강도와 지속가능성을 구현하는 촉감을 동시에 확보하고 있습니다. 과제 또한 남아 있습니다. 흡습성 문제를 해결하려면 고도의 수지 시스템이 필요하며, 바이오 섬유로 만든 부품은 전기차 도장 라인에서 일반적으로 사용되는 200°C의 소성 사이클을 견디지 못합니다. 2028년 이후 내장 부품에 재활용 소재 또는 바이오 유래 소재를 25% 사용하도록 요구하는 유럽 지침에 따라 천연섬유에 대한 수요는 더욱 증가하고 있습니다.
지역별 분석
아시아태평양은 2025년에 48.21%의 점유율로 자동차 스티어링 휠 시장을 주도했으며, 중국의 전기차 붐과 정책에 힘입은 반도체 현지 생산의 진전을 배경으로 연평균 성장률(CAGR) 6.56%로 성장을 지속하고 있습니다. 베이징은 2025년까지 반도체 현지 조달률 25%를 목표로 하고 있으며, 이에 따라 스티어링 휠에 내장된 센서 및 ECU공급 기반이 확립되고 있습니다. 대규모 생산과 비용 효율화를 통해 햅틱 피드백 등의 프리미엄 기능이 중형차로 빠르게 확산되고 있습니다. 그러나 희토류 자석에 대한 수출 규제로 인해 스즈키나 포드 공장의 일시적 가동 중단에서 볼 수 있듯이, OEM의 생산 일정에 차질이 발생하고 있습니다.
북미는 비용 주도권보다는 여전히 기술 도입 지역으로 자리매김하고 있습니다. 미국의 인프라 법안에서는 운전자의 기능 장애 감지가 의무화되어 있어, 다수의 센서가 탑재된 스티어링 휠에 대한 수요를 뒷받침하고 있습니다. 한편, 캐나다와 멕시코의 공장에서는 디트로이트 3사의 전기차(EV) 프로그램에 대응하기 위해 EPS 생산량을 확대되고 있습니다. 넥스테어의 멕시코에 위치한 새로운 기술 센터에서는 니어쇼어링 추세를 활용하여 컬럼형 EPS와 SbW의 검증을 강화하기 위해 2026년까지 350명의 일자리를 창출할 예정입니다. 멕시코에서 조립된 제품에 대한 미국의 관세 도입 가능성을 둘러싼 무역 정책의 불확실성으로 인해, 운임 급등에도 불구하고 조달처가 다시 아시아로 이동할 가능성이 있습니다.
유럽에서는 프리미엄화와 엄격한 안전 규제의 균형이 잡혀 있습니다. EU의 GSR II 및 Euro NCAP 2026에 따른 물리적 버튼 요건이 스티어링 휠에 통합된 조작 시스템 및 그립 센서에 대한 수요를 견인하고 있습니다. 보쉬(Bosch)의 헝가리 공장은 현재 지역 OEM을 위해 EPS 랙을 생산하고 있으며, 프리미엄 고객과 가까운 곳에서 생산 능력을 확대할 것으로 보입니다. 공급 측면에서는 독일의 1차 공급업체들이 TUV 및 KBA 당국을 통해 SbW 검증을 추진하고 있으며, 그 성능 기준이 전 세계 형식 승인으로 확산되고 있습니다.
신흥 지역-남미, 중동 및 아프리카-에서는 낮은 기저 수준에서 두 자릿수의 판매량 성장이 나타나고 있습니다. 인도의 부품 제조업체들은 1,000억 달러의 수출 목표를 세우고 있으며, 스티어링 휠 어셈블리는 관세 측면에서 유리한 대량 수송품으로 간주되고 있습니다. ZF Rane의 TRW Sun Steering Wheels 인수로 구르가온과 푸네 공장이 추가되면서, 현지 생산 에어백 및 센서의 국내 조달률이 향상되었습니다. 걸프 국가들은 차량의 탈탄소화를 위해 전기차(EV) 도입을 가속화하고 있지만, 인프라 부족으로 인해 SbW의 대규모 확산이 지연되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the automotive steering wheel market size is expected to grow from USD 34.98 billion in 2025 to USD 36.41 billion in 2026 and is forecast to reach USD 44.47 billion by 2031 at 4.08% CAGR over 2026-2031.
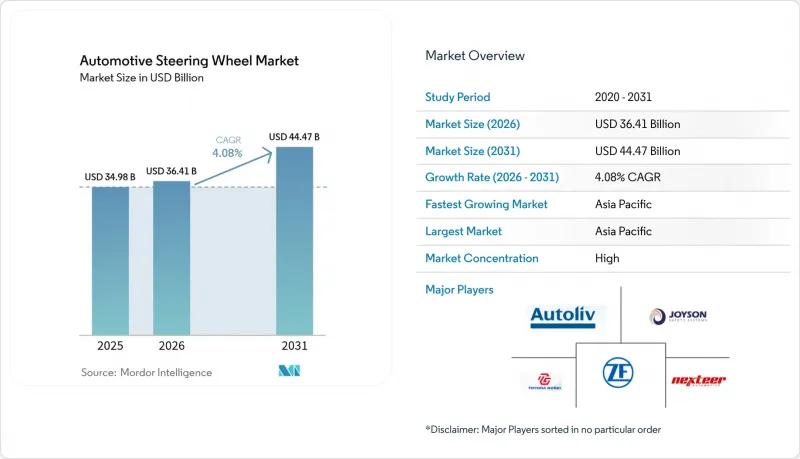
This report is Segmented by Technology (Conventional Column-Steer, and More), Material Type (Aluminum Rim, Magnesium Rim, and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Sales Channel (Original-Fitted and Aftermarket Replacement), Propulsion Type (Internal Combustion Engine, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Steering Wheel Market Trends and Insights
Surging Adoption of Steer-By-Wire (SBW) Platforms
Mercedes-Benz will roll out full SbW on the 2026 EQS, following NIO's 2025 launch of the ET9 that features ZF's column-less architecture. The technology removes mechanical links, enabling variable ratios and software-tuned feedback for urban manoeuvrability and high-speed stability. ZF has secured multi-OEM contracts that underpin a 7.90% CAGR for SbW hardware through 2030. The shift allows software-defined chassis control while challenging traditional suppliers to build electronic and cybersecurity competencies. Early wins in China illustrate regulators' willingness to homologate the architecture, accelerating global uptake.
Mandatory Frontal-Airbag Integration in Steering Wheels
EU General Safety Regulation II, effective July 2024, compels enhanced emergency braking and drowsiness-warning functions that re-shape steering design. In the United States, NHTSA research into driver-impairment detection uses tactile sensors embedded in the rim under the DADSS program. ZF LIFETEC has engineered top-deployment airbags that blend aesthetics with crash performance, meeting stricter packaging limits. Convergence of mandates raises system complexity and integration cost but standardises global requirements, creating volume leverage for tier-ones.
Volatile Aluminum and Magnesium Prices
Spot prices for aluminium and magnesium have swung more than 20% in 2024-2025, squeezing margins on lightweight rims and spokes. Suppliers hedge through long-term supply contracts and alloy substitution, yet cost spikes deter adoption in cost-sensitive segments. OEMs explore recycled feedstock to offset volatility, but tier-two casting shops remain exposed to raw-material risk.
Other drivers and restraints analyzed in the detailed report include:
- Light-Weighting Push From EV OEMs
- Legislative Drive-Impairment Monitoring Via Wheel Sensors
- Global SbW Homologation and Cyber-Security Compliance Lag
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
EPS controlled 37.86% of the automotive steering wheel market in 2025 as OEMs upgraded hydraulic systems to electric assist for efficiency and ADAS readiness. Conventional column-steer persists in markets prioritising low cost and mechanical simplicity. Steer-by-wire remains niche but is forecast at 7.66% CAGR to 2031 thanks to premium EV launches and autonomous drive programs.
The EPS-heavy portion of the steering wheel market size supports today's electrification, while SbW prepares the ground for Level 3+ hands-free modes. ZF's ET9 contract showcases commercial viability, delivering a variable ratio and software-defined feel without hydraulic fluid. In commercial trucks, EPS units provide up to 8,000 Nm torque yet trim energy draw compared with hydraulic pumps, underlining the efficiency case.
Second-order effects shape supplier positioning. EPS units rely on integrated torque sensors that feed lane-keep and auto-park functions, raising entry barriers for low-cost players. SbW architectures create fresh real estate for retractable columns, enabling living-room cabin concepts. Integration of high-bandwidth CAN-FD or Ethernet-based domain controllers further blurs lines between chassis and infotainment domains, offering white-space for software integrators rather than classic column specialists.
Aluminium remained the leader with 37.12% of the automotive steering wheel market share in 2025, credited to 40% mass savings and endless recyclability. Steel endures for heavy-duty fleets where durability trumps weight. Magnesium rims serve high-performance niches but face processing and corrosion cost hurdles. Natural-fibre composites, notably hemp and flax, are set to grow 7.42% CAGR through 2031, propelled by automakers' cradle-to-gate CO2 targets. Cupra's ampliTex seatbacks cut 49% CO2 versus carbon fibre, signalling scalability for interior parts.
The steering wheel market benefits from bio-composite skins over aluminium skeletons, marrying structural integrity with tactile sustainability cues. Challenges persist: moisture absorption demands advanced resin systems, and bio-fibre parts cannot exceed 200 °C bake cycles common in EV paint lines. Nevertheless, European directives urging 25% recycled or bio-based content in interiors post-2028 strengthen the pull for natural fibres.
Complete Report Scope:
- By Technology
- Conventional Column-Steer
- Electric Power-Assist (EPS)
- Steer-by-Wire (SbW)
- By Material Type
- Aluminium Rim
- Magnesium Rim
- Steel Rim
- Natural-fibre Composite Rim
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Bus and Coahes
- By Sales Channel
- OEM Fitted
- Aftermarket Replacement
- By Propulsion Type
- Internal-Combustion Engine
- Battery-Electric Vehicle
- Hybrid Electric Vehicle
- Plug-In Hybrid Electric Vehicles
- Fuel Cell Electric Vehicles
- Alternative Fuels
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Philippines
- Indonesia
- Vietnam
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific led the automotive steering wheel market with 48.21% share in 2025 and is growing at 6.56% CAGR on the strength of China's EV surge and policy-backed chip localisation. Beijing targets 25% local semiconductor content by 2025, anchoring supply for wheel-integrated sensors and ECUs. Large-scale production and cost efficiencies permit rapidly migrating premium features such as haptic feedback into mid-segment vehicles. However, export restrictions on rare-earth magnets have disrupted OEM production schedules, as seen in temporary shutdowns at Suzuki and Ford plants.
North America remains a technology adopter rather than a cost leader. US infrastructure legislation mandates driver-impairment detection, spurring demand for sensor-rich wheels, while Canadian and Mexican plants scale EPS output to serve Detroit Three EV programs. Nexteer's new technical centre in Mexico adds 350 roles by 2026 to hone column-type EPS and SbW validation, exploiting near-shoring trends. Trade-policy uncertainty around potential US tariffs on Mexican assemblies could shift sourcing back to Asia despite freight premiums.
Europe balances premiumisation with strict safety mandates. EU GSR II and Euro NCAP 2026 physical-button requirements anchor demand for integrated wheel controls and grip sensors. Bosch's Hungarian plant now produces EPS racks for regional OEMs, evidencing capacity expansion nearer to premium customers. On the supply side, German tier-ones push SbW validation through TUV and KBA authorities, setting performance benchmarks that ripple through global homologation.
Emerging regions - South America, the Middle East, and Africa - show double-digit unit growth off low bases. India's component makers pursue a USD 100 billion export ambition, with steering wheel assemblies viewed as tariff-friendly volume cargo. ZF Rane's acquisition of TRW Sun Steering Wheels adds Gurugram and Pune plants, enhancing domestic content for localised airbags and sensors. Gulf states accelerate EV adoption for fleet decarbonisation, yet infrastructure gaps delay large-scale SbW rollout.
- Autoliv Inc.
- ZF Friedrichshafen AG
- Joyson Safety Systems
- Toyoda Gosei Co., Ltd.
- Valeo SA
- Nexteer Automotive Group
- Tokai Rika Co., Ltd.
- Hyundai Mobis Co., Ltd.
- JTEKT Corporation
- NSK Ltd.
- Mando Corporation
- Robert Bosch GmbH
- Denso Corporation
- Continental AG
- Thyssenkrupp AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Adoption of Steer-By-Wire (SBW) Platforms
- 4.2.2 Mandatory Frontal-Airbag Integration In Steering Wheels
- 4.2.3 Light-Weighting Push From EV OEMs
- 4.2.4 Premiumisation and In-Cabin UX Upgrades
- 4.2.5 Legislative Drive-Impairment Monitoring Via Wheel Sensors
- 4.2.6 Demand For Stowable/Column-Less Cockpits In L3+ Vehicles
- 4.3 Market Restraints
- 4.3.1 Volatile Aluminium and Magnesium Prices
- 4.3.2 Global Sbw Homologation and Cybersecurity Compliance Lag
- 4.3.3 Chip-Level Shortages For Haptic/Driver-Sense Modules
- 4.3.4 Share-Shift Risk From Joystick/Voice HMI In Robo-Taxis
- 4.3.5 Chip-Level Shortages For Haptic/Driver-Sense Modules
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Technology
- 5.1.1 Conventional Column-Steer
- 5.1.2 Electric Power-Assist (EPS)
- 5.1.3 Steer-by-Wire (SbW)
- 5.2 By Material Type
- 5.2.1 Aluminium Rim
- 5.2.2 Magnesium Rim
- 5.2.3 Steel Rim
- 5.2.4 Natural-fibre Composite Rim
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Heavy Commercial Vehicles
- 5.3.4 Bus and Coahes
- 5.4 By Sales Channel
- 5.4.1 OEM Fitted
- 5.4.2 Aftermarket Replacement
- 5.5 By Propulsion Type
- 5.5.1 Internal-Combustion Engine
- 5.5.2 Battery-Electric Vehicle
- 5.5.3 Hybrid Electric Vehicle
- 5.5.4 Plug-In Hybrid Electric Vehicles
- 5.5.5 Fuel Cell Electric Vehicles
- 5.5.6 Alternative Fuels
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Philippines
- 5.6.4.6 Indonesia
- 5.6.4.7 Vietnam
- 5.6.4.8 Australia
- 5.6.4.9 New Zealand
- 5.6.4.10 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 South Africa
- 5.6.5.5 Egypt
- 5.6.5.6 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves & Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Autoliv Inc.
- 6.4.2 ZF Friedrichshafen AG
- 6.4.3 Joyson Safety Systems
- 6.4.4 Toyoda Gosei Co., Ltd.
- 6.4.5 Valeo SA
- 6.4.6 Nexteer Automotive Group
- 6.4.7 Tokai Rika Co., Ltd.
- 6.4.8 Hyundai Mobis Co., Ltd.
- 6.4.9 JTEKT Corporation
- 6.4.10 NSK Ltd.
- 6.4.11 Mando Corporation
- 6.4.12 Robert Bosch GmbH
- 6.4.13 Denso Corporation
- 6.4.14 Continental AG
- 6.4.15 Thyssenkrupp AG