|
시장보고서
상품코드
2122693
가정용 살충제 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Household Insecticides - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
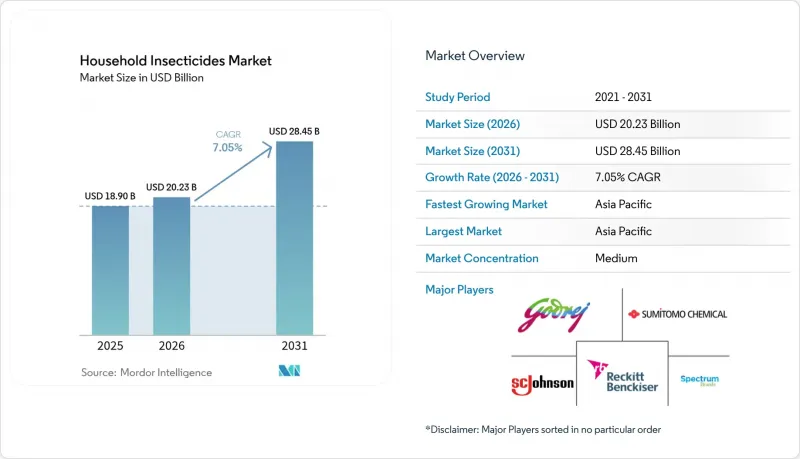
에 의하면, 2026년 가정용 살충제 시장 규모는 202억 3,000만 달러로 추정되고, 2025년 189억 달러에서 확대해, 2031년에는 284억 5,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 7.05%로 성장할 것으로 전망됩니다.
본 보고서는 해충 유형별(흰개미, 빈대, 딱정벌레 등), 화학 물질 유형별(합성·천연), 제형별(분제·과립제, 액체, 에어로졸 스프레이, 크림·로션 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 가정용 살충제 시장 동향 및 인사이트
곤충 매개 질환 증가
뎅기열, 말라리아, 치쿤구니아열의 유행이 과거 기준치를 크게 상회하는 기세로 급증하고 있으며, 질병 예방이 가정용 살충제 시장의 주요 구매 동기가 되고 있습니다. 전 세계 뎅기열 발생 건수는 2023년부터 2024년에 걸쳐 230% 급증했으며, 소비자들은 고가이면서 지속적인 방충 효과를 가진 제품을 찾고 있습니다. 기후 변화로 인해 모기의 번식기가 장기화되고, 이집트얼룩모기(Aedes aegypti)의 서식 범위가 온대 지역으로 확대됨에 따라 유럽과 북미에서 새로운 판매 시장이 열리고 있습니다. 각국 정부는 특히 뎅기열의 부담이 경제 생산성을 위협하고 있는 남미 지역에서 취약 계층을 대상으로 살충 스프레이나 모기향 구매에 대한 보조금을 지급하고 있습니다. 살충제가 단순한 생활용품에서 필수적인 건강 보호 수단으로 전환되는 가운데, 의료 전문가의 권고와 과학적 메시지를 효과적으로 활용하는 브랜드는 가정 내 보급률을 높이고 있습니다. 브라질에서 뎅기열 감염 건수가 사상 최고치를 기록한 해를 계기로, 장기간 효과가 지속되는 제제의 혁신이 진행되면서 역학적 압력과 연구 개발의 중점 간의 연관성이 더욱 강화되었습니다.
현대적인 소매 및 전자상거래 채널의 확대
DIY(직접 해충 방제) 분야에서 디지털 플랫폼은 현재 기존의 홈센터를 능가하고 있습니다. 2024년 독일에서는 아마존에서만 13억 달러 상당의 해충 방제 제품이 판매되어 전문 소매점의 판매량을 훨씬 웃돌았습니다. 온라인에서의 접근성은 제품의 투명성을 높이고, 풍부한 컨텐츠를 갖춘 상품 페이지와 리뷰 엔진을 통해 신생 기업이 기존 기업과 경쟁할 수 있게 해줍니다. 구독 모델은 정기적인 재고 보충을 보장하고 고객 생애 가치를 높이는 동시에, 가정용 살충제 시장의 계절적 수요 변동을 완화하고 있습니다. 클릭 스트림 및 구매 내역에서 수집된 데이터는 타겟팅된 프로모션의 지침이 되며, 제품 성분의 미세 조정에도 기여하고 있습니다. 이러한 채널 전환으로 인해 브랜드는 기존의 도매업체를 우회할 수 있게 되어 국경을 초월한 사업 확장이 가속화되고 있지만, 복잡한 표시 규제로 인해 현지 상황에 맞춘 포장이 여전히 요구되고 있습니다. 밀레니얼 세대와 Z세대 쇼핑객이 온라인 이용의 주축을 이루고 있으며, 모바일 기기를 통한 방충제 구매 빈도는 고령 소비자보다 60% 더 높습니다.
엄격한 국제 및 국가별 화학물질 규제
주요 공급업체의 경우, REACH 등록비와 시험 비용은 현재 연간 5,000만 유로(5,400만 달러)를 초과하고 있습니다. 피레스로이드계 살충제의 재평가로 인해 신제품 출시가 최대 2년 지연되고 있습니다. 중소기업은 이러한 장벽을 극복할 자금이 부족하여, 결과적으로 업계 재편이 진행되고 혁신의 다양성이 저하될 가능성이 있습니다. 국가마다 다른 규제로 인해 브랜드는 여러 가지 배합을 유지할 수밖에 없으며, 운영 비용은 규제가 통일된 경우에 비해 15-20% 더 높습니다. 예방 원칙이 불확실성을 조장하고 있어, 장기적인 연구개발 투자의 위험을 높이고 있습니다.
부문 분석
2025년, 가정용 살충제 시장 점유율의 33.62%를 모기 및 파리 방제가 차지했습니다. 이는 뎅기열과 말라리아에 대한 우려가 커지면서 지속적인 스프레이 및 모기향 사용이 확대되었기 때문입니다. 기후 변화로 인해 풍토병 유행 지역이 확대됨에 따라, 이러한 매개체로 인한 가정용 살충제 시장 규모는 계속해서 주도적인 위치를 유지할 것으로 보입니다. 고드레이(Godley)사가 출시한 레노플루트린은 피레스로이드 내성 모기를 직접적으로 처리하는 제품으로, 매개체에 의한 압력이 연구 개발의 초점을 어떻게 이끌고 있는지를 여실히 보여줍니다. 침대벌레와 딱정벌레류는 여행이 재개되면서 도시 지역에서의 발생이 가속화되고 있어 연평균 성장률(CAGR) 9.41%로 가장 빠르게 성장하고 있습니다. 인구 밀도가 높은 도시의 집주인들은 입주자 이동을 방지하기 위해 잔류 효과가 있는 에어로졸 제제를 구매하고 있습니다. 흰개미 방제는 열대 지역에서 여전히 중요하며, 재산 피해 방지로 이어지는 고가 제품군이 유지되고 있습니다. 쥐 방제는 정체 상태이지만, 음식물 쓰레기 수거가 지연되는 고층 아파트에서는 하이브리드형 미끼와 덫을 결합한 시스템의 도입으로 판매량이 서서히 증가하고 있습니다.
소비자의 지출 패턴을 보면, 재산 보호보다 건강 보호를 우선시하는 경향이 뚜렷하게 나타나고 있습니다. 벡터 방제 제품의 경우, 유효 성분의 비용이 동일하더라도 10-15%의 가격 프리미엄이 용인되고 있습니다. 마케팅에서는 긴급성을 강조하기 위해 질병 통계가 점점 더 많이 활용되고 있습니다. 여행 수요가 회복됨에 따라, 여행 가방에 수납 가능한 빈대용 스프레이나 세탁용 첨가제가 대형 유통 체인에 도입되고 있습니다. 고층 아파트의 설비용 통로는 바퀴벌레와 개미의 ‘고속도로’가 되어, 건물 전체에 해충이 만연하기 전에 관리 직원에게 경고해 주는 잔류성 제제나 스마트 모니터링 트랩에 대한 수요가 증가하고 있습니다.
지역별 분석
아시아태평양은 2025년에 가정용 살충제 시장 규모의 39.58%를 차지한 것으로 평가되었으며, 대도시의 확장, 높은 질병 부담, 그리고 일년 내내 따뜻한 기후에 힘입어 연평균 성장률(CAGR) 7.12%로 성장할 것으로 전망됩니다. 인도는 판매량에서 1위를 차지하고 있으며, 고드레지(Godrej)사가 국산 유효 성분 개발을 주도하고 일반 소매점 네트워크를 활용하여 판매를 확대되고 있습니다. 중국에서는 확대되는 중산층이 프리미엄 천연 모기향이나 스마트 기기로 지출을 전환하고 있지만, 일본의 어스(EARTH) 주식회사는 특허를 취득한 바퀴벌레용 유인제를 통해 우위를 유지하고 있으며, 2024년에는 1,390억 엔(9억 3,000만 달러)의 매출을 기록했습니다(EARTH.JP). 동남아시아에서는 에어로졸 제품 구매를 지원하는 정부의 뎅기열 대책 캠페인 덕분에 가장 빠른 성장세를 보이고 있습니다.
미국에서는 화학 물질에 대한 감시가 강화되는 가운데 천연 성분 제품이 합성 성분 제품 시장 점유율을 잠식하고 있지만, 캠핑이나 하이킹에서는 여전히 DEET가 자리 잡고 있습니다. 캐나다에서는 더욱 엄격해진 표시 규제로 인해 신제품 출시가 주춤하고 있지만, 승인된 브랜드에 대한 소비자의 신뢰는 높아지고 있습니다. 멕시코는 뎅기열이 북쪽으로 확산되고 소매 인프라가 현대화됨에 따라 고성장 지역으로 부상하고 있습니다. 지역별 전자상거래 보급률이 40%를 넘어서면서, 도시 지역 가구에서는 소비자 직접 판매형 구독 서비스가 일반화되고 있습니다.
유럽에서는 REACH 규제에 대응해야 하는 부담과 온대 지역의 해충 발생 시즌이 짧아진 점이 시장 확대를 억제하고 있습니다. 스페인에서 그리스에 이르는 남유럽에서는 여름이 길어짐에 따라 1인당 사용량이 증가하고 있습니다. 독일에서는 DIY 체인점이나 온라인 플랫폼을 통한 판매량이 가장 많지만, 영국 시장에서는 천식에 대한 우려가 언론을 통해 대대적으로 보도됨에 따라 반려동물에게 안전하고 무취인 스프레이로의 전환이 현저히 진행되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 세계의 가정용 살충제 시장 목차
제2장 서론
제3장 조사 방법
제4장 주요 요약
제5장 시장 구도
제6장 시장 규모 및 성장 예측
제7장 경쟁 구도
제8장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the household insecticides market size in 2026 is estimated at USD 20.23 billion, growing from 2025 value of USD 18.9 billion with 2031 projections showing USD 28.45 billion, growing at 7.05% CAGR over 2026-2031.
This report is Segmented by Insect Type (Termites, Bedbugs and Beetles, and More), Chemical Type (Synthetic and Natural), Form (Dust and Granules, Liquids, Aerosol Sprays, Creams and Lotions, and More), and Geography (North America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Household Insecticides Market Trends and Insights
Rising Prevalence of Insect-Borne Diseases
Dengue, malaria, and chikungunya outbreaks are surging far beyond historical baselines, making disease prevention the primary purchase trigger in the household insecticides market. Global dengue incidence jumped 230% from 2023 to 2024, propelling consumers toward continuous protection products that command premium price points. Climate change lengthens mosquito breeding seasons and expands Aedes aegypti into temperate zones, which opens new sales pockets in Europe and North America. Governments subsidize spray and coil purchases for vulnerable communities, especially in South America, where the dengue burden threatens economic productivity. Brands leveraging medical endorsements and scientific messaging enjoy stronger household penetration, as insecticides shift from convenience goods to essential health safeguards. Brazil's record dengue year drove innovation in long-lasting formulations, reinforcing the link between epidemiological pressure and research and development focus.
Expansion of Modern Retail and E-commerce Channels
Digital platforms now outpace traditional hardware stores for do-it-yourself pest control. Amazon alone moved USD 1.3 billion of pest control products in Germany during 2024, dwarfing specialty retail volumes. Online availability elevates product transparency, letting challengers compete with incumbents through content-rich listings and review engines. Subscription models lock in replenishment, increasing customer lifetime value and smoothing demand seasonality in the household insecticides market. Data captured from clickstream and purchase histories guides targeted promotions and informs formulation tweaks. The channel shift accelerates cross-border expansion because brands bypass legacy wholesalers, although complex labeling laws still require localized packaging. Millennial and Gen Z shoppers lead the online cohort, purchasing insect repellents 60% more often via mobile than older consumers.
Stringent Global and National Chemical Regulations
REACH registration fees and testing costs now exceed EUR 50 million (USD 54 million) annually for leading suppliers. Pyrethroid re-evaluations delay launches by up to two years. Smaller firms lack the capital to clear such hurdles, leading to potential consolidation and reduced innovation diversity. Divergent national rules force brands to maintain multiple formulations, pushing operational costs 15-20% higher than under harmonized regimes. The precautionary principle fuels uncertainty, making long-horizon research and development investments riskier.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Urbanization and Population Density Growth
- Regulatory Shift Toward Low-Toxicity Bio-based Actives
- Health and Environmental Toxicity Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mosquitoes and flies controlled 33.62% of the household insecticides market share in 2025, propelled by dengue and malaria fears and boosted by continuous spray and coil adoption. The household insecticides market size attributable to these vectors will maintain leadership as climate change widens endemic zones. Godrej's renofluthrin launch directly tackles pyrethroid-resistant mosquitoes and underscores how vector pressure guides research and development focus. Bedbugs and beetles climb fastest at 9.41% CAGR because resurgent travel accelerates urban infestations; landlords in dense cities purchase residual aerosols to avert tenant turnover. Termite treatments remain regionally important in the tropics, sustaining premium pricing tied to property damage prevention. Rodent control plateaus but gains incremental volume in high-rise complexes where food waste collection lags, prompting hybrid bait and snap systems.
Consumer spending patterns reveal a hierarchy that favors health protection over property preservation. Vector control products tolerate 10-15% price premiums even when active ingredient costs are similar. Marketing increasingly highlights disease statistics to reinforce urgency. As travel rebounds, luggage-compatible bedbug sprays and laundry additives enter big box chains. Utility corridors in apartment towers serve as superhighways for cockroaches and ants, elevating demand for residual formulations and smart monitoring traps that alert maintenance staff before infestations spread building-wide.
Complete Report Scope:
- By Insect Type (Value)
- Mosquitoes and Flies
- Rats and Other Rodents
- Termites
- Bedbugs and Beetles
- Other Insect Types
- By Chemical Type (Value)
- Synthetic
- DEET
- Picaridin
- Other Synthetic Chemicals
- Natural
- Citronella Oil
- Geraniol Oil
- Other Natural Oils
- Synthetic
- By Form (Value)
- Dust and Granules
- Liquids
- Aerosol Sprays
- Coils and Vaporizers
- Creams and Lotions
- Other Forms
- By Geography (Value)
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Singapore
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific commanded a 39.58% share of the household insecticides market size in 2025 and is projected to rise at a 7.12% CAGR driven by megacity sprawl, high disease burden, and year-round warmth. India leads volume as Godrej pioneers indigenous actives and leverages vast distribution across general trade outlets. China's expanding middle class channels spending into premium natural coils and smart devices, while Japan's Earth Corporation sustains dominance through patented cockroach baits and recorded sales of JPY 139 billion (USD 930 million) in 2024 EARTH.JP. Southeast Asia shows the fastest incremental growth owing to government dengue campaigns that subsidize aerosol purchases.
The United States sees naturals encroaching on synthetic market share amid heightened chemical scrutiny, yet DEET remains entrenched for camping and hiking. Canada's stricter labeling laws slow new product launches but reinforce consumer trust in approved brands. Mexico emerges as a high-growth pocket as dengue spreads northward and retail infrastructure modernizes. Regional e-commerce penetration above 40% makes direct-to-consumer subscriptions the norm for urban households.
REACH compliance burdens and shorter pest seasons in temperate zones restrain Europe's market expansion. Southern Europe, from Spain to Greece, exhibits higher per-capita usage due to extended summers. Germany leads unit sales through DIY chains and online platforms, whereas the United Kingdom market pivots heavily toward pet-safe fume-free sprays following high press coverage of asthma concerns.
- SC Johnson & Son, Inc.
- Reckitt Benckiser Group plc
- Godrej Consumer Products Ltd.
- Spectrum Brands Holdings, Inc.
- Sumitomo Chemical Co., Ltd.
- Henkel AG & Co. KGaA (Combat)
- Bayer AG
- BASF SE
- FMC Corporation
- Central Garden & Pet Company
- Rentokil Initial plc
- Rollins, Inc.
- Ecolab Inc.
- UPL Limited
- Dabur India Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Table of Contents for Global Household Insecticides Market
2 Introduction
- 2.1 Study Assumptions and Market Definition
- 2.2 Scope of the Study
3 Research Methodology
4 Executive Summary
5 Market Landscape
- 5.1 Market Overview
- 5.2 Market Drivers
- 5.2.1 Rising prevalence of insect-borne diseases
- 5.2.2 Expansion of modern retail and e-commerce channels
- 5.2.3 Rapid urbanization and population density growth
- 5.2.4 Regulatory shift toward low-toxicity bio-based actives
- 5.2.5 Emergence of smart/IoT-enabled insect-control devices
- 5.2.6 Outdoor living trend boosting demand for patio/yard solutions
- 5.3 Market Restraints
- 5.3.1 Stringent global and national chemical regulations
- 5.3.2 Health and environmental toxicity concerns
- 5.3.3 Tariff-driven volatility in raw-material supply chains
- 5.3.4 Rising pest resistance reducing product efficacy
- 5.4 Technological Outlook
- 5.5 Regulatory Landscape
- 5.6 Porter's Five Forces Analysis
- 5.6.1 Bargaining Power of Suppliers
- 5.6.2 Bargaining Power of Buyers
- 5.6.3 Threat of New Entrants
- 5.6.4 Threat of Substitute Products
- 5.6.5 Intensity of Competitive Rivalry
6 Market Size and Growth Forecasts
- 6.1 By Insect Type (Value)
- 6.1.1 Mosquitoes and Flies
- 6.1.2 Rats and Other Rodents
- 6.1.3 Termites
- 6.1.4 Bedbugs and Beetles
- 6.1.5 Other Insect Types
- 6.2 By Chemical Type (Value)
- 6.2.1 Synthetic
- 6.2.1.1 DEET
- 6.2.1.2 Picaridin
- 6.2.1.3 Other Synthetic Chemicals
- 6.2.2 Natural
- 6.2.2.1 Citronella Oil
- 6.2.2.2 Geraniol Oil
- 6.2.2.3 Other Natural Oils
- 6.2.1 Synthetic
- 6.3 By Form (Value)
- 6.3.1 Dust and Granules
- 6.3.2 Liquids
- 6.3.3 Aerosol Sprays
- 6.3.4 Coils and Vaporizers
- 6.3.5 Creams and Lotions
- 6.3.6 Other Forms
- 6.4 By Geography (Value)
- 6.4.1 North America
- 6.4.1.1 United States
- 6.4.1.2 Canada
- 6.4.1.3 Mexico
- 6.4.1.4 Rest of North America
- 6.4.2 Europe
- 6.4.2.1 Germany
- 6.4.2.2 United Kingdom
- 6.4.2.3 France
- 6.4.2.4 Italy
- 6.4.2.5 Spain
- 6.4.2.6 Russia
- 6.4.2.7 Rest of Europe
- 6.4.3 Asia-Pacific
- 6.4.3.1 China
- 6.4.3.2 India
- 6.4.3.3 Japan
- 6.4.3.4 Australia
- 6.4.3.5 Singapore
- 6.4.3.6 Rest of Asia-Pacific
- 6.4.4 Middle East
- 6.4.4.1 Saudi Arabia
- 6.4.4.2 United Arab Emirates
- 6.4.4.3 Rest of Middle East
- 6.4.5 Africa
- 6.4.5.1 South Africa
- 6.4.5.2 Egypt
- 6.4.5.3 Rest of Africa
- 6.4.1 North America
7 Competitive Landscape
- 7.1 Market Concentration
- 7.2 Strategic Moves
- 7.3 Market Share Analysis
- 7.4 Company Profiles (Includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 7.4.1 SC Johnson & Son, Inc.
- 7.4.2 Reckitt Benckiser Group plc
- 7.4.3 Godrej Consumer Products Ltd.
- 7.4.4 Spectrum Brands Holdings, Inc.
- 7.4.5 Sumitomo Chemical Co., Ltd.
- 7.4.6 Henkel AG & Co. KGaA (Combat)
- 7.4.7 Bayer AG
- 7.4.8 BASF SE
- 7.4.9 FMC Corporation
- 7.4.10 Central Garden & Pet Company
- 7.4.11 Rentokil Initial plc
- 7.4.12 Rollins, Inc.
- 7.4.13 Ecolab Inc.
- 7.4.14 UPL Limited
- 7.4.15 Dabur India Limited