

|
시장보고서
상품코드
2122731
의료 청구 업무 아웃소싱 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Global Medical Billing Outsourcing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
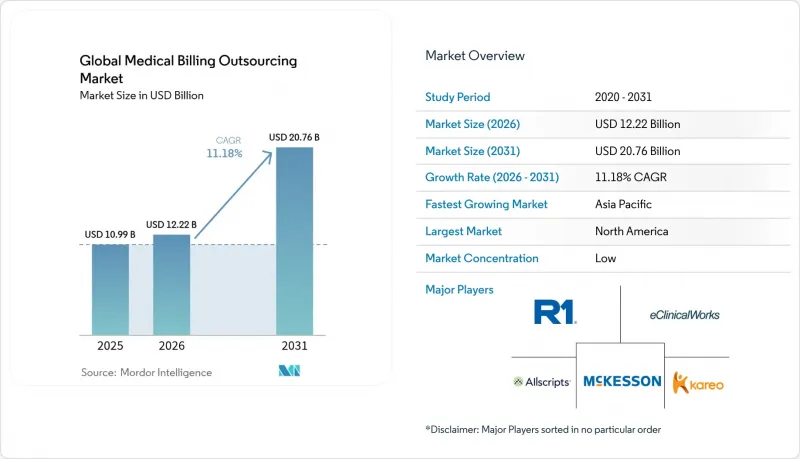
에 의하면, 2026년 의료 청구 업무 아웃소싱 시장 규모는 122억 2,000만 달러로 추정되고 2025년 109억 9,000만 달러에서 확대해, 2031년에는 207억 6,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안의 연평균 성장률(CAGR)은 11.18%가 될 것으로 전망됩니다.

본 보고서는 서비스별(프론트엔드, 미들엔드, 백엔드), 도입 형태별(On-Premise, 클라우드 기반), 최종 사용자별(병원, 클리닉, 외래 진료 및 기타 의료 제공업체), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 의료 청구 업무 아웃소싱 시장 동향 및 인사이트
청구 처리의 복잡화와 문서 작성 부담 증가
코딩 규정은 계속 늘어나고 있으며, 의료 제공업체는 모든 업데이트 정보를 추적하고 연중 교육 프로그램을 유지할 수 있는 외부 전문가를 확보할 수밖에 없는 상황입니다. 현재 아웃소싱 파트너들은 AI를 활용한 문서 작성 도구를 제공하고 있으며, 이를 통해 정확한 청구율이 향상되고 수익 주기가 단축되고 있습니다. 이미 46%의 병원이 AI를 활용한 청구 서비스를 이용하고 있는 만큼, 의료 청구 업무 아웃소싱 시장은 전술적인 측면보다 전략적인 중요성을 띠고 있습니다.
원격의료 및 디지털 헬스 청구 건수의 급증
원격 진료에는 고유한 수정 코드와 주를 넘나드는 수혜 자격 확인이 필요하지만, 많은 사내 팀에서는 이를 신속하게 습득하기 어렵습니다. 전문 벤더가 이러한 격차를 메우고, 원격 의료 코드를 다양한 지급 기관의 규정에 부합하도록 조정함으로써 수익 누수를 방지하고 있습니다. 북미와 아시아태평양 수요 급증은 의료 청구 업무 아웃소싱 시장의 두 자릿수 성장을 지속시키는 요인 중 하나입니다.
데이터 개인정보 보호 및 사이버 보안에 대한 우려
제안된 HIPAA 보안 개정안에 따라, 업계는 규정 준수 대응 첫해에만 93억 달러의 비용을 부담하게 될 가능성이 있습니다. 이러한 부담은 서비스 가격 상승을 초래하고, 벤더 심사를 더욱 엄격하게 만드는 요인이 될 것으로 보입니다. 대규모 제3자 파트너들은 암호화 및 다단계 인증에 막대한 투자를 하고 있지만, 일부 제공업체들은 기밀 데이터를 외부에 위탁하는 것을 주저하고 있어, 개인정보 보호를 중시하는 지역에서는 단기적인 도입이 억제되고 있습니다.
부문별 분석
미들엔드 아웃소싱은 연평균 성장률(CAGR) 12.26%로 성장하고 있으며, 코딩 정확도가 순상환액을 결정하기 때문에 그 기여도는 더욱 확대될 전망입니다. 2024년 이 부문의 성장은 즉각적인 현금 흐름 효과를 추구하는 제공업체들에게 정확한 청구 처리 성과가 의료 청구 업무 아웃소싱 시장 규모를 얼마나 좌우하는지를 보여줍니다. 4,000만 달러 규모의 자금 조달 라운드를 유치한 인공지능(AI) 코더의 등장은 투자자들의 신뢰를 뒷받침하고 있습니다.
각 의료 시스템 기업의 보고에 따르면, AI를 활용한 코딩의 첫 번째 통과율은 96%인 반면, 수작업의 경우 88%에 그치고 있어, 이에 따라 더 많은 조직이 전문 파트너로 전환하고 있습니다. 프런트엔드 업무는 수급 자격 확인이 보편적으로 필요하기 때문에 42.68%의 점유율을 유지하고 있지만, 성장의 핵심은 미들엔드의 정확도 향상 도구에 있습니다. 백엔드 채권 회수는 회수가 어려운 미수금에 대해 여전히 필수적이지만, 의료 청구 업무 아웃소싱 시장에서는 우수한 코딩을 중심으로 한 풀사이클형 패키징 서비스가 점점 더 주목받고 있습니다.
지역별 분석
2025년 북미의 매출 점유율 49.21%는 HIPAA 갱신 및 금액 기준 결제에 대응하기 위해 의료 제공업체가 외부 파트너에 의존하고 있는 실정을 여실히 보여줍니다. 청구 기각 건수 증가로 어려움을 겪고 있는 미국의 병원들은 전문 이의 제기 팀이나 AI 연구소를 보유한 벤더를 선택하고 있으며, 이것이 의료 청구 업무 아웃소싱 시장을 견인하고 있습니다. 캐나다의 의료 기관들은 현대화된 개인정보 보호 협약에 따라 청구 처리가 허용된 국경 간 기업들과 제휴하고 있습니다.
아시아태평양의 연평균 성장률(CAGR) 12.85%는 두 가지 원동력을 반영하고 있습니다. 마닐라와 방갈로르의 해외 아웃소싱 센터가 전 세계의 청구 처리를 대규모로 수행하는 한편, 일본, 호주, 동남아시아의 국내 병원들은 증가하는 디지털 헬스 업무 부하에 대응하기 위해 아웃소싱을 도입하고 있습니다. 정부의 e-헬스 이니셔티브로 인해 문서화 과정이 복잡해지면서 지역 내 수요가 더욱 증가하고 있습니다.
유럽은 성숙한 시장임에도 불구하고 여전히 진화를 거듭하는 기회로 남아 있습니다. GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정)에 따라 엄격한 데이터 처리 규정이 마련되어 있어, 규정 준수를 충족하는 클라우드 환경을 갖춘 지역 공급업체가 유리한 입장에 있습니다. 서비스 제공업체들은 고령화에 따른 비용 압박을 완화하기 위해 아웃소싱을 활용하고 있으며, 이로 인해 의료 청구 업무 아웃소싱 시장은 안정세를 유지하고 있습니다. 중동 및 아프리카에서는 GCC(걸프협력회의) 회원국의 공립병원에서 EHR(전자건강기록) 보급률이 75%를 넘어섬에 따라, 낮은 기반에서 활발한 성장이 나타나고 있습니다. 남미에서는 경제 변동으로 인해 발전 속도에 편차가 나타나고 있지만, 브라질과 콜롬비아의 공공 부문 현대화 프로그램이 이를 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the medical billing outsourcing market size in 2026 is estimated at USD 12.22 billion, growing from 2025 value of USD 10.99 billion with 2031 projections showing USD 20.76 billion, growing at 11.18% CAGR over 2026-2031.
This report is Segmented by Service (Front-End, Middle-End, and Back-End), Type of Deployment (On-Premise and Cloud-Based), End User (Hospitals, Physicians' Offices, and Ambulatory/Other Providers), and Geography (North America, Europe, Asia-Pacific, Middle-East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Billing Outsourcing Market Trends and Insights
Rising Claim Complexity & Documentation Burden
Coding rules continue to multiply, forcing providers to secure outside specialists who track every update and maintain year-round training programs. Outsourcing partners now supply AI-aided documentation tools that raise clean claim rates and shorten revenue cycles. As 46% of hospitals already use AI-enabled billing services, the medical billing outsourcing market gains strategic rather than tactical relevance.
Surge in Telehealth & Digital-Health Billing Volumes
Virtual visits require unique modifiers and cross-state eligibility checks that many internal teams cannot master quickly. Specialist vendors fill the gap, preventing revenue leakage by aligning telehealth codes with diverse payer rules. Demand spikes in North America and Asia Pacific help sustain double-digit growth for the medical billing outsourcing market.
Data-Privacy & Cybersecurity Concerns
Proposed HIPAA Security amendments could cost the industry USD 9.3 billion in year one compliance, a burden likely to lift service prices and prompt closer vendor vetting. Larger third-party partners invest heavily in encryption and multi-factor authentication, yet some providers hesitate to place sensitive data off-premise, tempering short-term adoption in privacy-focused regions.
Other drivers and restraints analyzed in the detailed report include:
- Efforts to Contain In-House Processing Costs
- Climbing Payor Denial Rates & Audit Intensity
- Increasing Legislative and Regulatory Pressure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Middle-End outsourcing grew at 12.26% CAGR and is poised to widen its contribution as coding precision defines net reimbursement. The segment's 2024 expansion illustrates how clean-claim performance shapes the medical billing outsourcing market size for providers seeking immediate cash impacts. Artificial-intelligence coders funded by USD 40 million rounds demonstrate investor confidence.
Health systems report that AI-guided coding drives 96% first-pass rates against 88% for manual efforts, pushing more organizations toward specialist partners. Front-End tasks keep their 42.68% lead due to universal need for eligibility verification, but growth centers on Middle-End accuracy tools. Back-End collections remain essential for difficult balances, yet the medical billing outsourcing market increasingly markets full-cycle bundles anchored by coding excellence.
Complete Report Scope:
- By Service
- Front-End
- Middle-End
- Back-End
- By Type of Deployment
- On-Premise
- Cloud-based
- By End User
- Hospitals
- Physicians' Offices
- Ambulatory/Other Providers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America's 49.21% revenue share in 2025 highlights providers' reliance on external partners to navigate HIPAA updates and value-based payments. United States hospitals, burdened by rising denial volumes, choose vendors with specialized appeals teams and AI labs that push the medical billing outsourcing market forward. Canadian institutions align with cross-border firms now permitted to handle claims under modernized privacy pacts.
Asia Pacific's 12.85% CAGR reflects dual momentum. Offshore centers in Manila and Bangalore process global claims at scale, while domestic hospitals in Japan, Australia and Southeast Asia adopt outsourcing to handle growing digital-health workloads. Government e-health initiatives raise documentation complexity, further lifting regional demand.
Europe remains a mature but evolving opportunity. GDPR shapes strict data-handling rules, favoring regional providers with compliant cloud setups. Providers use outsourcing to curb cost pressures tied to aging populations, keeping the medical billing outsourcing market stable. Middle East and Africa experience brisk growth off small bases as EHR penetration expands past 75% in GCC public hospitals. South America's progress is uneven, slowed by economic swings yet buoyed by public-sector modernization programs in Brazil and Colombia.
- R1 RCM
- Optum / Change Healthcare
- Allscripts (Veradigm)
- Cerner (Oracle Health)
- GE Healthcare
- eClinicalWorks
- Experian Health
- Genpact
- Kareo Inc.
- Mckesson
- Quest Diagnostics
- The SSI Group
- Conifer Health Solutions
- GeBBs Healthcare Solutions
- Athenahealth
- AdvantEdge Healthcare Solutions
- Firstsource Solutions
- 247 MBS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising claim complexity & documentation burden
- 4.2.2 Surge in telehealth & digital-health billing volumes
- 4.2.3 Efforts to contain and decrease in-house processing costs
- 4.2.4 Climbing payor denial rates & audit intensity
- 4.2.5 Global coder workforce shortages
- 4.2.6 Shift to value-based reimbursement models
- 4.3 Market Restraints
- 4.3.1 Data-privacy & cybersecurity concerns
- 4.3.2 Increasing legislative and regulatory pressue
- 4.3.3 High costs of technology
- 4.3.4 In-house platform investments by large IDNs
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Service
- 5.1.1 Front-End
- 5.1.2 Middle-End
- 5.1.3 Back-End
- 5.2 By Type of Deployment
- 5.2.1 On-Premise
- 5.2.2 Cloud-based
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Physicians' Offices
- 5.3.3 Ambulatory/Other Providers
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 R1 RCM Inc.
- 6.3.2 Optum / Change Healthcare
- 6.3.3 Allscripts (Veradigm)
- 6.3.4 Cerner (Oracle Health)
- 6.3.5 GE Healthcare
- 6.3.6 EClinicalWorks
- 6.3.7 Experian Health
- 6.3.8 Genpact
- 6.3.9 Kareo Inc.
- 6.3.10 McKesson Corporation
- 6.3.11 Quest Diagnostics
- 6.3.12 The SSI Group
- 6.3.13 Conifer Health Solutions
- 6.3.14 GeBBS Healthcare Solutions
- 6.3.15 Athenahealth
- 6.3.16 AdvantEdge Healthcare Solutions
- 6.3.17 Firstsource Solutions
- 6.3.18 247 MBS
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


