

|
시장보고서
상품코드
2122735
응급실 정보 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Global Emergency Department Information System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
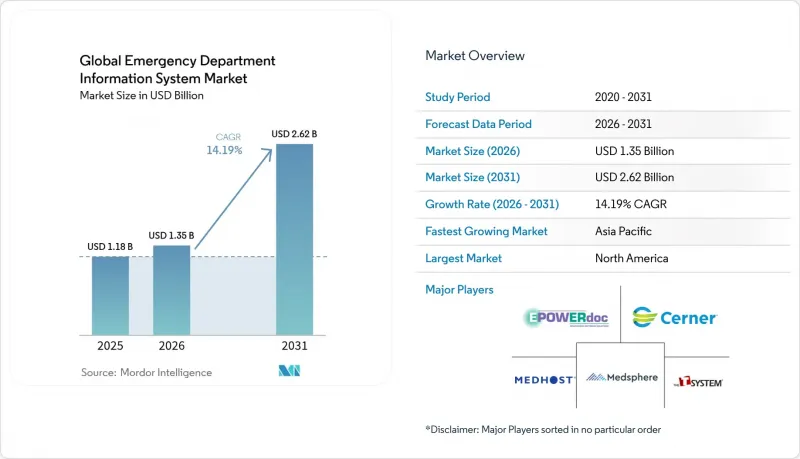
에 의하면, 2026년 응급실 정보 시스템 시장 규모는 13억 5,000만 달러로 추정되고 2025년 11억 8,000만 달러에서 확대해, 2031년에는 26억 2,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안 연평균 성장률(CAGR) 14.19%로 성장할 것으로 전망됩니다.

본 보고서에서는 산업을 용도별(의사 컴퓨터 처방 입력(CPOE), 임상 문서 작성, 환자 추적·트라이아지, 기타),배포 방식별(On-Premise, SaaS(Software-as-a-Service)), 소프트웨어 유형별(엔터프라이즈 솔루션, 베스트 오브 브リ?ド(BoB) 솔루션), 최종 사용자별(소규모 병원, 중규모 병원, 대규모 병원), 지역별로 분류하고 있습니다.
세계의 응급실 정보 시스템 시장 동향 및 인사이트
AI를 활용한 임상 의사결정 지원의 통합
현재 AI 도구는 89%의 정확도로 인간의 중증도 분류에 필적하며, 응급 심혈관 질환의 치료 시작까지 소요되는 시간을 205.4분 단축함으로써 실제 임상 현장에서의 트리아지 가치를 입증하고 있습니다. HCA Healthcare와 같은 대형 의료 서비스 제공업체는 184개 진료과에서 앰비언트 문서화(Ambient Documentation)를 도입하고 있으며, 환자의 수용률은 99%에 달할 전망입니다. 마찬가지로 중요한 점은 예측 모델이 AUROC 값 0.92를 초과하는 등 기존 스코어링 기법을 능가하는 성능을 보여주고 있어, AI는 치료 성과와 업무 효율성 양면에서 중요한 차별화 요인으로서의 입지를 확고히 하고 있습니다.
환자 중심의 품질 지표를 기반으로 한 보상 모델의 확대
메디케어의 ‘가치 기반 구매(Value-Based Purchasing)’ 제도에서는 병원에 대한 결제가 처리 능력이나 환자 경험 점수와 연동되어 있어, 응급실의 성과가 직접적인 수익원이 되고 있습니다. 민간 보험의 보상액 감소로 인해 워크플로우 효율화가 시급한 과제로 대두된 반면, 2024년에 도입될 새로운 형평성 지표에서는 사회적 결정 요인이 응급실 평가 지표에 반영될 예정입니다. 조기에 이에 적응한 병원은 이익률을 유지하고, 2018년부터 2022년까지 기록된 3.8%의 수익 감소를 완화할 수 있습니다.
사이버 보안 침해로 인한 배상 책임 및 보험료
2024년에는 1건당 침해로 인한 평균 비용이 977만 달러로 상승하고, 공격 발생 시 병원이 하루에 200만 달러의 손실을 입을 가능성도 있어, CFO(최고재무책임자)는 비필수적인 IT 도입을 연기해야 하는 압박을 받고 있습니다. 사이버 보험의 손해율 상승으로 인해, 특히 클라우드에 의존하는 워크플로우에서 보험료가 상승하고 있습니다.
부문별 분석
2025년, 병원이 실시간 병상 현황 및 중증도 대시보드를 우선시한 결과, ‘환자 추적 및 분류’는 응급실 정보 시스템 시장 점유율의 35.78%를 차지했습니다. 이 부문의 우위는 ‘도어 투 닥터(Door-to-Doctor)’ 벤치마크에 대한 규제 당국의 관심과, 수동 점검보다 더 조기에 패혈증 및 뇌졸중을 감지하는 AI 도구 덕분에 더욱 공고해지고 있습니다. 전자 처방(E-Prescribing)은 연평균 성장률(CAGR) 14.73%라는 가장 높은 성장률을 보이고 있으며, 미국 내 많은 주에서 전자 처방을 의무화하는 오피오이드 위험 모니터링이 이를 뒷받침하고 있습니다. 대규모 의료 제공업체들이 의사의 화면 조작 시간을 단축하기 위해 환경 음성 기록을 도입하고 있는 만큼, 임상 문서화도 중요한 위치를 차지하고 있습니다. 약물 안전 프로토콜이 폐쇄형 루프 주문을 요구하고 있기 때문에 CPOE 도입은 안정적으로 진행되고 있습니다. 예측 중증도 점수 산정 기능을 트라이아지 모듈에 통합하는 새로운 분석 기술은 초기 평가부터 문서화까지를 단일 워크플로우로 아우르는 미래의 통합을 시사합니다.
앞으로 환자 추적 모듈은 5G 원격 측정 기술과 연동되어 구급차가 도착하기 훨씬 전에 생체 신호 데이터를 확보할 수 있게 될 것입니다. 한편, 트리아지 엔진은 머신러닝을 통한 권장 사항 위에 자연어 쿼리를 중첩해 나가는 방식으로 발전할 것으로 보입니다. 분리된 추적 보드를 계속 운영하는 병원은 AI가 몇 분 더 빨리 감지할 수 있는 수용 능력 트리거를 놓칠 위험이 있습니다. 품질 지표에 따른 보상 제도가 정착됨에 따라, 현재는 대학병원 등에만 도입된 고도 트리아지 대시보드를 소규모 시설에서도 도입하게 될 것으로 보입니다. 따라서 응급실 정보 시스템 시장에서는 추적, 배정, 기록을 통합한 기록 시스템으로 통합하는 멀티 모듈 제품군의 라이선스 보급률이 상승할 전망입니다.
2025년, 응급실 정보 시스템 시장 규모 중 SaaS를 통한 제공이 64.62%의 점유율을 차지했습니다. 의료 기관들은 초기 투자 비용 절감, 도입 기간 단축, 규제에 대한 자동 대응을 주요 이유로 꼽고 있습니다. IT 팀이 소규모인 지역 병원의 경우, 유지보수를 벤더에 위탁함으로써 분석 기능 애드온에 예산을 할당할 수 있게 됩니다. 대규모 의료 시스템의 경우, 여전히 클라우드 도입 범위를 확대하고 있지만 지연에 민감한 영상 진단을 위해 On-Premise 클러스터를 유지하고 있으며, 이것이 해당 부문의 연평균 성장률(CAGR) 14.85%라는 전망을 설명해 줍니다. 팬데믹 이후의 인력 부족으로 인해 원격 업그레이드에는 사내 엔지니어가 별로 필요하지 않기 때문에 클라우드 도입이 가속화되고 있습니다.
엣지 게이트웨이가 빈번하게 발생하는 생체 신호 데이터를 로컬에서 처리하면서 요약 데이터를 중앙 클라우드에 아카이브함에 따라, 하이브리드 운영 형태는 더욱 정착될 것으로 보입니다. 사이버 보험 계약 조건에 따라 현재 명확한 재해 복구 절차서 작성이 의무화되어 있어, 감사된 중복성을 갖춘 SaaS 공급업체가 유리한 입장에 있습니다. 국제적인 사업 확장에 따라 대역폭 관련 과제가 부각되고 있지만, 멀티존 아키텍처 및 오프라인 동기화를 통해 서비스 중단은 완화되고 있습니다. 규제 당국의 감사에서 변조가 불가능한 로그 트레일 제출이 점점 더 요구되는 가운데, 실시간 규정 준수 대시보드를 제공하는 클라우드 공급자의 인지도가 높아지고 있습니다. 따라서 응급실 정보 시스템 시장의 성장은 클라우드의 경제성과 병원 수준의 내결함성을 동시에 갖춘 공급자의 역량에 달려 있습니다.
지역별 분석
2025년, 북미는 응급실 정보 시스템 시장 매출의 44.78%를 차지했습니다. CMS(미국 의료보험서비스센터)의 품질 보고 및 조인트 커미션(Joint Commission) 인증에 따라, 병원은 입원 결정부터 퇴원까지의 지표를 기록해야 할 의무가 있으며, 연간 1억 3,000만 건이 넘는 응급실 내원 건수로 인해 정확한 환자 추적의 필요성이 더욱 높아지고 있습니다. 2018년부터 2022년까지 기록된 메디케어 지급액 감소는 효율화 노력에 재정적 시급성을 더하고 있습니다. TEFCA 도입과 FHIR 인센티브는 실시간 상호 운용성을 보장하는 플랫폼 업그레이드를 더욱 촉진하고 있습니다. 프로비던스 헬스 앤 서비스(Providence Health & Services)와 같은 대규모 네트워크는 적극적인 비용 절감을 추구하고 있으며, 이는 상환 압력을 상쇄하는 데 있어 기술의 역할을 부각시키고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 15.53%로 가장 빠르게 성장하는 지역입니다. 각국 정부는 병원의 현대화에 자금을 지원하고 있으며, 민간 병원 체인은 디지털화의 확대를 통해 높은 수익률을 기대하고 있습니다. 중국의 5G 의료 지휘 센터는 응급 대응 범위를 확대하고 지역 간 이송 시간을 단축함으로써 고도화된 연결성의 가치를 입증하고 있습니다. 그러나 중국 병원의 파산 건수 증가는 재무 상황의 편차를 여실히 드러내고 있으며, 진료량에 따라 규모를 조정할 수 있는 모듈형 가격 책정이 요구되고 있습니다. 동남아시아에서는 병원 경영진이 영상 진단 및 1차 진료에 대한 투자를 우선시하고 있으며, 이는 응급 부문의 디지털 도구와 자연스럽게 연계되고 있습니다.
유럽에서는 각국의 국민보건서비스 체계와 상호운용성에 관한 규제의 뒷받침을 받아 꾸준한 도입이 진행되고 있습니다. 독일의 ‘병원 미래법’에서는 40억 유로 이상이 디지털 프로젝트에 투입되었으며, 감사 결과 병원은 인프라 면에서는 우수하지만 원격의료 보급률에서는 뒤처지고 있는 것으로 밝혀졌습니다. ‘유럽 헬스 데이터 스페이스’는 기록 형식을 표준화하고 국경을 넘는 환자 이동을 촉진합니다. eCREAM 등의 프로젝트는 응급 의료 문서화를 통일하는 것을 목표로 하고 있으며, 한편 이탈리아의 연구에 따르면 특히 응급실이 변혁의 거점이 되고 있는 대규모 교육 병원일수록 디지털화 진척이 빠르다는 사실이 밝혀졌습니다. 동유럽의 의료 시스템에서는 성숙도 격차를 해소하기 위해 협력적인 자금 조달 방안을 모색하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, emergency department information system market size in 2026 is estimated at USD 1.35 billion, growing from 2025 value of USD 1.18 billion with 2031 projections showing USD 2.62 billion, growing at 14.19% CAGR over 2026-2031.
This report Segments the Industry Into by Application (Computerized Physician Order Entry (CPOE), Clinical Documentation, Patient Tracking & Triage, and More), by Deployment (On-Premise EDIS, Software-As-A-Services (SaaS)), by Software Type (Enterprise Solutions, Best of Breed (B. O. B. ) Solutions), by End User (Small Hospitals, Medium-Sized Hospitals, Large Hospitals), and Geography.
Global Emergency Department Information System Market Trends and Insights
AI-enabled clinical decision support integration
AI tools now match human acuity classification accuracy at 89% and have cut emergency cardiovascular time-to-treatment by 205.4 minutes, proving value in real-world triage . Large providers such as HCA Healthcare run ambient documentation across 184 departments with 99% patient acceptance. Equally important, predictive models outperform traditional scoring with AUROC readings above 0.92, positioning AI as a core differentiator in both outcomes and operational efficiency.
Increasing patient-centric quality-metric reimbursement models
Medicare's Value-Based Purchasing ties hospital payment to throughput and experience scores, making emergency department performance a direct revenue lever. Declining commercial reimbursements heighten the urgency to streamline workflows, while new equity measures rolling out in 2024 embed social determinants into emergency metrics. Hospitals that adapt early can safeguard margins and mitigate the 3.8% revenue erosion documented from 2018 to 2022.
Cyber-security breach liabilities and insurance premiums
Average breach cost climbed to USD 9.77 million in 2024 and hospitals can lose USD 2 million daily during attacks, prompting CFOs to delay non-essential IT rollouts. Rising cyber-insurance loss ratios are pushing premiums up, particularly for cloud-dependent workflows.
Other drivers and restraints analyzed in the detailed report include:
- Rapid growth of SaaS-based EDIS in community hospitals
- Mandatory time-to-treatment key performance indicators
- Surge in real-time health-data exchange frameworks (FHIR, TEFCA)
- Edge analytics & 5G deployment in ambulance-to-ED data flow
- Clinician burnout linked to complex EHR interfaces
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Patient Tracking & Triage captured 35.78% of Emergency Department Information System market share in 2025 as hospitals prioritized real-time bed status and acuity dashboards. The segment's dominance is reinforced by regulatory focus on door-to-doctor benchmarks and by AI tools that flag sepsis and stroke earlier than manual checks. E-Prescribing is the fastest riser at a 14.73% CAGR, fueled by opioid-risk monitoring that mandates electronic scripts across many US states. Clinical Documentation holds significant weight as large providers deploy ambient voice capture to trim physician screen time. CPOE adoption remains steady because medication safety protocols demand closed-loop orders. Emerging analytics that fold predictive acuity scoring into triage modules hint at future convergence where a single workflow covers initial assessment through documentation.
Looking forward, patient-tracking modules will integrate with 5G telemetry to ingest ambulance vitals long before arrival, while triage engines will layer natural-language queries on top of machine-learning recommendations. Hospitals continuing to run siloed tracking boards risk missing capacity triggers that AI can surface minutes sooner. As quality-metric reimbursement deepens, even smaller facilities will adopt advanced triage dashboards that now sit only in academic centers. The Emergency Department Information System market will therefore see rising license penetration for multi-module suites that merge tracking, prescribing, and documentation into a unified record.
SaaS delivery held 64.62% share of the Emergency Department Information System market size in 2025. Providers cite lower up-front capital, faster go-live timelines, and automatic regulatory updates as key reasons. Community hospitals with lean IT teams offload maintenance to vendors, freeing budgets for analytics add-ons. Large health systems still expand cloud footprints but also maintain on-premise clusters for latency-sensitive imaging, which explains the segment's 14.85% CAGR outlook. The post-pandemic workforce crunch accelerates cloud uptake because remote upgrades need fewer in-house engineers.
Hybrid patterns will deepen as edge gateways process high-frequency vitals locally while archiving summary data to a central cloud. Cyber-insurance stipulations now require explicit disaster-recovery run-books, favoring SaaS vendors with audited redundancy. International expansion highlights bandwidth challenges yet multi-zone architectures and offline sync mitigate outages. As regulatory audits increasingly ask for immutable log trails, cloud providers offering real-time compliance dashboards gain mind-share. Growth in the Emergency Department Information System market will therefore pivot on vendor ability to mix cloud economics with hospital-grade resilience.
Complete Report Scope:
- By Application
- Computerized Physician Order Entry (CPOE)
- Clinical Documentation
- Patient Tracking & Triage
- E-Prescribing
- Others
- By Deployment
- On-Premise
- Software-as-a-Service (SaaS)
- By Software Type
- Enterprise Solutions
- Best-of-Breed (BoB) Solutions
- By End User
- Small Hospitals (<=100 beds)
- Medium-Sized Hospitals (101-299 beds)
- Large Hospitals (>=300 beds)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- APAC
- China
- Japan
- India
- Australia
- South Korea
- Rest of APAC
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 44.78% of Emergency Department Information System market revenue in 2025. CMS quality reporting and Joint Commission accreditation oblige hospitals to document admit-decision-to-departure metrics, and over 130 million annual ED visits intensify the need for precise patient tracking. Medicare payment declines recorded between 2018 and 2022 add financial urgency to efficiency drives. TEFCA rollout and FHIR incentives further compel platform upgrades that guarantee real-time interoperability. Large networks such as Providence Health & Services pursue aggressive cost containment, underscoring technology's role in offsetting reimbursement stress.
Asia-Pacific is the fastest-growing region at a 15.53% CAGR to 2031. Governments fund hospital modernization and private chains forecast high profit margins from digital expansion. 5G medical command centers in China extend rescue reach and cut cross-district transfer times, proving the value of advanced connectivity. Yet rising bankruptcies among Chinese hospitals highlight uneven financial health, requiring modular pricing that scales with volume. In Southeast Asia, directors prioritize diagnostic imaging and primary care investments which naturally link to emergency-department digital tools.
Europe posts steady uptake shaped by national health-service structures and interoperability regulations. Germany's Hospital Future Act channels more than EUR 4 billion into digital projects, and audits reveal hospitals excel in infrastructure yet lag in telehealth penetration. The European Health Data Space will standardize record formats, aiding cross-border patient flows. Projects such as eCREAM aim to harmonize emergency documentation, while Italian studies show that larger, teaching hospitals digitize fastest, especially where emergency rooms act as transformation anchors. Eastern European systems seek coordinated funding to bridge their maturity gaps.
- Oracle Health (Cerner)
- Epic Systems
- MEDHOST Inc.
- Meditech
- Allscripts
- Mckesson
- UnitedHealth Group (Optum Insight)
- EPOWERdoc Inc.
- T-Systems International
- Evident (CPSI)
- Logibec Inc.
- Medsphere Systems
- Picis Clinical Solutions
- Wellsoft Corporation
- Dedalus Group
- Koninklijke Philips
- Ascom
- Cantata Health
- VitalHub Corp.
- Global Health Ltd (MasterCare)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-enabled clinical decision-support integration
- 4.2.2 Increasing patient-centric quality-metric reimbursement models
- 4.2.3 Rapid growth of SaaS-based EDIS in community hospitals
- 4.2.4 Mandatory time-to-treatment key performance indicators
- 4.2.5 Surge in real-time health-data exchange frameworks (FHIR, TEFCA)
- 4.2.6 Edge analytics & 5G deployment in ambulance-to-ED data flow
- 4.3 Market Restraints
- 4.3.1 Cyber-security breach liabilities & insurance premiums
- 4.3.2 Clinician burnout linked to complex EHR user-interfaces
- 4.3.3 Fragmented middleware standards for device integration
- 4.3.4 Budget freezes in public hospitals post-pandemic
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Application
- 5.1.1 Computerized Physician Order Entry (CPOE)
- 5.1.2 Clinical Documentation
- 5.1.3 Patient Tracking & Triage
- 5.1.4 E-Prescribing
- 5.1.5 Others
- 5.2 By Deployment
- 5.2.1 On-Premise
- 5.2.2 Software-as-a-Service (SaaS)
- 5.3 By Software Type
- 5.3.1 Enterprise Solutions
- 5.3.2 Best-of-Breed (BoB) Solutions
- 5.4 By End User
- 5.4.1 Small Hospitals (<=100 beds)
- 5.4.2 Medium-Sized Hospitals (101-299 beds)
- 5.4.3 Large Hospitals (>=300 beds)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 APAC
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of APAC
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Oracle Health (Cerner)
- 6.3.2 Epic Systems Corporation
- 6.3.3 MEDHOST Inc.
- 6.3.4 MEDITECH
- 6.3.5 Allscripts Healthcare Solutions
- 6.3.6 McKesson Corporation
- 6.3.7 UnitedHealth Group (Optum Insight)
- 6.3.8 EPOWERdoc Inc.
- 6.3.9 T-Systems International
- 6.3.10 Evident (CPSI)
- 6.3.11 Logibec Inc.
- 6.3.12 Medsphere Systems
- 6.3.13 Picis Clinical Solutions
- 6.3.14 Wellsoft Corporation
- 6.3.15 Dedalus Group
- 6.3.16 Philips Healthcare
- 6.3.17 Ascom Holding AG
- 6.3.18 Cantata Health
- 6.3.19 VitalHub Corp.
- 6.3.20 Global Health Ltd (MasterCare)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


