|
시장보고서
상품코드
2122738
무세포 단백질 발현 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cell-free Protein Expression - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
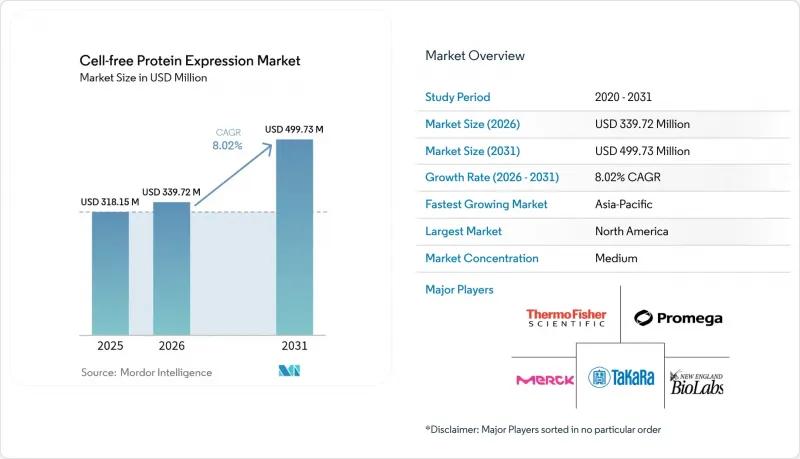
에 의하면, 무세포 단백질 발현 시장 규모는 2025년 3억 1,815만 달러로 평가되었습니다. 2026년에는 3억 3,972만 달러로 확대되어 2031년까지 4억 9,973만 달러에 이를 것으로 예상되고 2026-2031년에 걸쳐 CAGR 8.02%로 성장할 전망입니다.

본 보고서는 제품 유형(키트, 시약 및 소모품, 기타), 발현 시스템(대장균, 기타), 발현 모드(배치 발현, 기타), 반응 형태(액체, 기타), 용도(효소 공학, 기타), 최종 사용자(제약·바이오기술 기업, 기타),지역(북미, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 무세포 단백질 발현 시장 동향 및 인사이트
고속 단백질 공학 및 합성 생물학의 급속한 확산
무세포 워크플로우를 통해 클로닝, 콜로니 피킹, 스케일업이 당일 내에 완료되는 공정으로 통합되어, 연구자들은 96웰 또는 384웰 플레이트에서 수백 개의 변이체를 스크리닝할 수 있게 되었습니다. 반면, 생세포 시스템에서는 수주가 소요됩니다. 2024년 DARPA가 8,700만 달러를 투자한 BioMaDE 보조금은 국방용 효소 및 바이오센서 프로토타입 개발을 수행하는 모듈식 라이세이트 플랫폼에 자금을 지원했습니다. 라이세이트와 에너지 혼합물이 세트로 구성된 시판 키트를 통해 실험실 간 성능이 표준화되고 진입 장벽이 낮아졌습니다. 골든 게이트(Golden Gate)법이나 깁슨 어셈블리(Gibson Assembly)법과의 원활한 통합을 통해 디지털 DNA 설계에서 기능성 단백질로의 전환이 24시간 이내에 가능해졌으며, 학술 기관 및 스타트업의 신약 개발 주기가 근본적으로 단축되었습니다.
바이오의약품 및 맞춤형 의료에 대한 수요 증가
2025년에는 3,800종 이상의 생물학적 제제가 임상 개발 단계에 있었으며, 며칠 이내에 환자 맞춤형 단백질을 대량 생산할 수 있는 유연한 플랫폼에 대한 수요가 시급한 과제로 대두되었습니다. 무세포 시스템은 맞춤형 암 백신의 턴어라운드 목표를 달성하고 있는데, 이는 CHO 세포로는 임상 규모에서 실현할 수 없는 것입니다. 대장균 용해액을 기반으로 한 Sutro Biopharma의 ‘XpressCF’는 2025년에 2상 임상시험 단계로 진입했으며, 공정 관리가 cGMP를 준수한다면 규제 당국이 무세포 방식으로 제조된 치료제를 심사할 수 있음을 입증했습니다. 2024년 FDA 지침에 따라, 분석적 특성 평가가 견고한 한 호스트 프리 제조는 기존 생물학적 제제 규제의 적용 대상이 됨이 명확해졌습니다. 자원이 부족한 지역의 병원들은 현재 콜드체인에 대한 의존을 피하기 위해, 치료용 효소를 현지에서 생산할 수 있는 동결건조 키트 도입을 검토하고 있습니다.
시약의 높은 비용 및 확장성 문제
에너지 칵테일, 뉴클레오티드, 라이세이트의 조제는 제조 비용의 최대 70%를 차지하며, 포유류 유래 추출물의 경우 1밀리그램당 500달러를 초과하는 경우가 많아 발효법의 경제성을 훨씬 능가합니다. 연속 교환형 반응기는 수율을 5배 향상시키지만, 그럼에도 불구하고 피드배치법에 의한 역가에는 두 자릿수의 차이가 있습니다. Merck KGaA는 2024년 자사의 ‘ReadyToProcess CFPS’ 라인을 통해 시약 비용을 30% 절감했으나, 경영진은 10리터 규모에서는 여전히 주류를 이루는 항체의 경우 수익성이 떨어짐을 인정하고 있습니다. 라이세이트 생산에서 규모의 경제를 달성할 수 없기 때문에 그 채택은 고부가가치 또는 시간적 제약이 엄격한 단백질로 제한되어 있습니다.
부문별 분석
동결건조 형태가 콜드체인의 장벽을 제거하고, 프로토콜 번들화로 인해 문제 해결이 불필요해짐에 따라 키트는 시장에서 인지도를 높이고 있습니다. 키트는 2026년부터 2031년까지 연평균 성장률(CAGR) 11.52%로 성장할 전망이며, 2025년에 시약이 매출에서 44.22%의 선두를 유지했음에도 불구하고 시약을 능가하는 성장률을 보이고 있습니다. 이러한 추세는 미리 최적화된 혼합물이 소규모 바이오테크 기업 및 학술 연구소의 학습 곡선을 얼마나 단축시켜 주는지를 보여줍니다. 피펫팅 및 정제를 자동화하는 장비는 키트 도입을 촉진하고 있으며, 2025년 Nuclera의 eProtein 플랫폼이 12개 제약 연구소에 도입된 사례가 이를 뒷받침합니다. 버퍼 구성을 맞춤 설정하는 숙련된 사용자에게는 시약이 여전히 필수적이지만, 키트의 편의성이 신규 사용자층 확대를 주도하고 있습니다. 신규 진출기업들은 복잡한 대상 처리를 외부에 위탁하는 경우가 많기 때문에 부속품 및 위탁 리서트 조제를 포함한 서비스 번들 시장도 동시에 성장하고 있습니다.
곤충 세포 용해물을 이용한 무세포 단백질 발현 시장 규모는 연평균 성장률(CAGR) 10.74%로 확대될 것으로 예상되며, 2025년에는 대장균이 차지하는 51.75%의 점유율을 서서히 잠식해 나갔습니다. 진핵생물의 당화 반응에 대한 수요가 백신 항원 및 항체 단편용 하이브리드 및 곤충 세포 솔루션을 뒷받침하고 있습니다. 밀 배아 추출물은 중간 위치에 있으며, 박테리아 내에서 응집하는 막 단백질에 주로 사용됩니다. LenioBio와 같은 신생 기업들은 대장균의 수율 이점과 외인성 효소를 결합하여 더 낮은 비용으로 포유류와 동등한 품질에 근접하고 있습니다. 토끼의 망상 적혈구나 포유류 시스템은 번역 후 변형의 정확성이 비용보다 우선시되는 틈새 시장에서 계속해서 활용되고 있습니다.
지역별 분석
북미는 2025년 매출의 39.54%를 차지했으며, 이는 신속 대응 플랫폼에 대한 NIH(미국 국립보건원) 및 DoD(미국 국방부)의 지출을 반영한 것입니다. 또한, 이 지역에는 주요 키트 공급업체와 FDA(미국 식품의약국)의 규제 대상인 임상 프로그램의 대부분이 집중되어 있습니다. 그 뒤를 이어 유럽이 뒤를 잇고 있으며, 특히 독일과 영국에서는 맞춤형 의료 시범 사업을 지원하는 ‘Horizon Europe’의 2억 유로 규모의 보조금에 힘입고 있습니다.
아시아태평양은 국내 리서트 생산 및 자동화 도구에 투입된 중국의 12억 위안 규모의 부양책에 힘입어, 연평균 성장률(CAGR) 10.28%로 이 지역에서 가장 빠른 성장률을 기록하고 있습니다. 일본의 오사카와 후쿠오카 거점은 팬데믹 대비를 강화하기 위해 72시간 이내에 백신을 생산하는 것을 목표로 하고 있습니다. 인도는 작물 보호용 효소 및 현장 진단용 저비용 키트를 개발하는 ‘센터 오브 엑설런스(Center of Excellence)’에 자금을 지원하고 있습니다.
남미와 중동 및 아프리카는 현재 규모는 작지만, 브라질에서는 동물용 백신 개발이 진행 중이며, 남아프리카에서는 농촌 지역에서 진단용 항원 생산이 시범적으로 이루어지고 있습니다. 도입의 성패는 키트 가격 인하와 현지 생물제제에 관한 규제 명확화에 달려 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the cell-free protein expression market size is expected to increase from USD 318.15 million in 2025 to USD 339.72 million in 2026 and reach USD 499.73 million by 2031, growing at a CAGR of 8.02% over 2026-2031.
This report is Segmented by Product Type (Kits, Reagents & Consumables, and More), Expression System (E. Coli, and More), Expression Mode (Batch, and More), Reaction Format (Liquid, and More), Application (Enzyme Engineering, and More), End User (Pharmaceutical & Biotechnology Companies, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cell-free Protein Expression Market Trends and Insights
Rapid Adoption for High-Throughput Protein Engineering & Synthetic Biology
Cell-free workflows collapse cloning, colony picking, and scale-up into a same-day process, letting researchers screen hundreds of variants in 96- or 384-well plates while living-cell systems would require weeks. DARPA's USD 87 million BioMaDE awards in 2024 funded modular lysate platforms that prototype enzymes and biosensors for defense applications. Commercial kits bundling lysate and energy mixes standardize performance across labs and lower entry barriers. Seamless integration with Golden Gate and Gibson assembly now transforms a digital DNA design into functional protein inside 24 hours, fundamentally shortening discovery cycles in academia and start-ups.
Rising Demand for Biologics & Personalized Therapeutics
More than 3,800 biologics were in clinical development in 2025, creating urgency for flexible platforms that crank out patient-specific proteins within days. Cell-free systems meet turn-around targets for personalized cancer vaccines, something CHO cells cannot achieve at clinical scale. Sutro Biopharma's XpressCF, built on E. coli lysates, advanced to Phase II trials in 2025, proving regulators will review cell-free-produced therapeutics when process controls comply with cGMP. FDA guidance in 2024 cemented that host-free manufacturing falls under existing biologic rules so long as analytical characterization is robust. Hospitals in low-resource regions now explore freeze-dried kits to print therapeutic enzymes on site, sidestepping cold-chain dependencies.
High Reagent Costs & Scalability Challenges
Energy cocktails, nucleotides, and lysate prep account for up to 70% of production cost, often topping USD 500 per milligram for mammalian extracts, dwarfing fermentation economics. Continuous-exchange reactors improve yields five-fold but still trail fed-batch titers by two orders of magnitude. Merck KGaA shaved 30% off reagent expense in 2024 with its ReadyToProcess CFPS line, yet management admits 10-liter scale remains uneconomical for mainstream antibodies. Absence of scale economies in lysate production confines adoption to high-value or time-critical proteins.
Other drivers and restraints analyzed in the detailed report include:
- Advantages Over Cell-Based Systems (Speed, Toxic Protein Handling)
- Government On-Demand Biomanufacturing Preparedness Initiatives
- Limited Post-Translational Modification Capability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Kits captured growing mindshare as lyophilized formats removed the cold-chain barrier and bundled protocols eliminated troubleshooting. Kits are on track to expand at an 11.52% CAGR between 2026 and 2031, outpacing reagents despite the latter's 44.22% revenue lead in 2025. This trajectory illustrates how pre-optimized mixes shorten learning curves for small biotechs and academic labs. Instruments that automate pipetting and purification complement kit adoption, as seen with Nuclera's eProtein platform rollout to 12 pharma labs in 2025. Reagents will remain indispensable for experienced users customizing buffer chemistries, yet kit convenience drives the incremental user base. Accessories and service bundles, including contract lysate prep, grow in tandem because newcomers often outsource complex targets.
The cell-free protein expression market size for insect-cell lysates is expected to climb at 10.74% CAGR, nibbling share from E. coli's 51.75% dominance in 2025. Demand for eukaryotic glycosylation propels hybrid and insect solutions for vaccine antigens and antibody fragments. Wheat-germ extracts sit in the middle ground, favored for membrane proteins that aggregate in bacteria. Start-ups such as LenioBio combine E. coli yield advantages with exogenous enzymes to approximate mammalian quality at lower cost. Rabbit reticulocyte and mammalian systems persist in niche roles where post-translational fidelity trumps cost.
Complete Report Scope:
- By Product Type
- Kits
- Reagents & Consumables
- Instruments and Systems
- Accessories & Services
- By Expression System
- E. coli
- Wheat Germ
- Rabbit Reticulocyte
- Insect Cell
- Mammalian
- Hybrid / Others
- By Expression Mode
- Batch Expression
- Continuous-Flow Expression
- Continuous-Exchange Cell-Free (CECF)
- By Reaction Format
- Liquid (Fresh Lysate)
- Lyophilized (Freeze-Dried)
- Microfluidic / Chip-Based
- By Application
- Enzyme Engineering
- Protein-Protein Interaction
- Protein Labelling
- High-Throughput Production
- Therapeutic Protein Production
- Others
- By End User
- Pharmaceutical & Biotechnology Companies
- Academic & Research Institutes
- Contract Research Organisations (CROs)
- Diagnostic Developers
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 39.54% of 2025 revenue, reflecting NIH and DoD spending on rapid-response platforms. The region also hosts leading kit suppliers and most FDA-regulated clinical programs. Europe follows, buoyed by Horizon Europe's EUR 200 million grants that subsidize personalized-medicine pilots, particularly in Germany and the United Kingdom.
Asia-Pacific posts the fastest regional growth at 10.28% CAGR, underwritten by China's RMB 1.2 billion stimulus for domestic lysate production and automation tools. Japan's Osaka and Fukuoka hubs target 72-hour vaccine turnaround to bolster pandemic preparedness. India funds centers of excellence building low-cost kits for crop-protection enzymes and point-of-care diagnostics.
South America and the Middle East & Africa remain small today, though Brazil explores veterinary vaccines and South Africa pilots rural diagnostic antigen production. Adoption hinges on lowering kit prices and clarifying local biologics regulations.
- Arbor Bioscience (Daicel)
- Bioneer
- Bio-Rad Laboratories
- CellFree Sciences Co., Ltd.
- Creative Biolabs
- Cube Biotech
- Danahar
- GeneCopoeia
- Jena Bioscience
- LenioBio
- Merck
- New England Biolabs
- Nuclera Nucleics Ltd.
- Profacgen
- Promega
- Sutro Biopharma Inc.
- Synthelis
- Takara Bio
- Thermo Fisher Scientific
- VectorBuilder Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption for High-Throughput Protein Engineering & Synthetic Biology
- 4.2.2 Rising Demand for Biologics & Personalized Therapeutics
- 4.2.3 Advantages Over Cell-Based Systems (Speed, Toxic Protein Handling)
- 4.2.4 Government "On-Demand Biomanufacturing" Preparedness Initiatives
- 4.2.5 Freeze-Dried Kits Enabling Decentralized Protein Printing
- 4.2.6 AI/ML-Driven Yield Optimization & Automation Integration
- 4.3 Market Restraints
- 4.3.1 High Reagent Costs & Scalability Challenges
- 4.3.2 Limited Post-Translational Modification Capability
- 4.3.3 Fragmented IP Landscape & Patent Thickets
- 4.3.4 Regulatory Pathway Uncertainty for Therapeutic Proteins
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 Kits
- 5.1.2 Reagents & Consumables
- 5.1.3 Instruments and Systems
- 5.1.4 Accessories & Services
- 5.2 By Expression System
- 5.2.1 E. coli
- 5.2.2 Wheat Germ
- 5.2.3 Rabbit Reticulocyte
- 5.2.4 Insect Cell
- 5.2.5 Mammalian
- 5.2.6 Hybrid / Others
- 5.3 By Expression Mode
- 5.3.1 Batch Expression
- 5.3.2 Continuous-Flow Expression
- 5.3.3 Continuous-Exchange Cell-Free (CECF)
- 5.4 By Reaction Format
- 5.4.1 Liquid (Fresh Lysate)
- 5.4.2 Lyophilized (Freeze-Dried)
- 5.4.3 Microfluidic / Chip-Based
- 5.5 By Application
- 5.5.1 Enzyme Engineering
- 5.5.2 Protein-Protein Interaction
- 5.5.3 Protein Labelling
- 5.5.4 High-Throughput Production
- 5.5.5 Therapeutic Protein Production
- 5.5.6 Others
- 5.6 By End User
- 5.6.1 Pharmaceutical & Biotechnology Companies
- 5.6.2 Academic & Research Institutes
- 5.6.3 Contract Research Organisations (CROs)
- 5.6.4 Diagnostic Developers
- 5.6.5 Others
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 France
- 5.7.2.3 United Kingdom
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Australia
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East & Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East & Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Arbor Bioscience (Daicel)
- 6.3.2 Bioneer Corporation
- 6.3.3 Bio-Rad Laboratories Inc.
- 6.3.4 CellFree Sciences Co., Ltd.
- 6.3.5 Creative Biolabs
- 6.3.6 Cube Biotech GmbH
- 6.3.7 Danahar
- 6.3.8 GeneCopoeia Inc.
- 6.3.9 Jena Bioscience GmbH
- 6.3.10 LenioBio GmbH
- 6.3.11 Merck KGaA
- 6.3.12 New England Biolabs Inc.
- 6.3.13 Nuclera Nucleics Ltd.
- 6.3.14 Profacgen
- 6.3.15 Promega Corporation
- 6.3.16 Sutro Biopharma Inc.
- 6.3.17 Synthelis
- 6.3.18 Takara Bio Inc.
- 6.3.19 Thermo Fisher Scientific Inc.
- 6.3.20 VectorBuilder Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment