

|
시장보고서
상품코드
2122741
석유 및 가스 분야 AI : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)AI In Oil And Gas - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
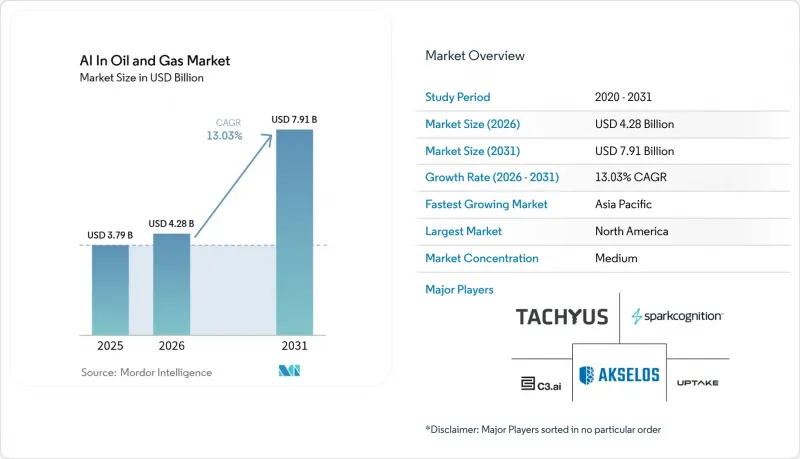
에 의하면, 석유 및 가스 분야 AI 시장 규모는 2025년에 37억 9,000만 달러로 평가되었습니다. 2026년 42억 8,000만 달러에서 2031년까지 79억 1,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 13.03%를 나타낼 전망입니다.
본 보고서는 사업 부문(업스트림, 중류, 하류), 솔루션 유형(플랫폼, 서비스), 자산 소재지(온쇼어, 오프쇼어), 용도(품질 관리, 생산 최적화, 기타),AI 기술(머신러닝, 딥러닝, 기타), 배포 방식(클라우드, On-Premise, 엣지), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 석유 및 가스 분야 AI 시장 동향 및 인사이트
복잡한 지하 빅데이터를 처리하는 능력
주요 사업자가 보유한 1,500페타바이트가 넘는 지진 탐사 아카이브를 처리하기 위해서는 수십 년에 걸친 시추 데이터, 암석 물리 데이터, 생산 데이터를 몇 시간 이내에 분석할 수 있는 AI 가속기가 필요하며, 이를 통해 수동 방식에 비해 시추 위치의 정확도가 70% 향상되었습니다. ADNOC의 ‘ENERGYai’ 에이전트는 자율적인 지진 탐사 분석을 통해 지질 모델 구축 시간을 75% 단축하여, 저류층 엔지니어가 몇 분 만에 여러 개의 프랙처링 클러스터 시나리오를 검증할 수 있게 했습니다. 물리학에 기반한 신경망과 과거 시추 데이터의 융합을 통해 비전통 유전에서 히스토리 매칭 속도가 빨라졌으며, 대규모 패드 개발에서 자본 효율 지표가 직접적으로 향상되고 있습니다.
가격 변동 속에서 커지는 채굴 비용 절감 압박
가격 변동으로 인해 이익률은 계속해서 압박을 받고 있으며, 각 사업자들은 AI 주도 자동화를 통해 시추 비용을 25-50% 절감하기 위해 노력하고 있습니다. 나보즈 인더스트리즈(Naboz Industries)는 자동 시추 제어 시스템을 도입한 결과, 시추 속도가 30% 향상된 것을 기록했습니다. 또한 통합 생산 최적화 소프트웨어를 통해 퍼미안 분지 자산의 의사결정 주기 시간이 며칠에서 몇 시간으로 단축되었습니다. 타키우스(Takius)사는 강화 학습 알고리즘을 활용해 로드 펌프의 매개변수를 동적으로 조정함으로써, 인공 채유 효율에서 현저한 향상을 보고했습니다. 성숙 유전을 운영하는 사업자들 사이에서는 경제적 수명을 연장하기 위해 AI를 활용한 회수가 필수적이라는 인식이 높아지고 있습니다.
AI 플랫폼의 높은 초기 설비 투자(CAPEX)
엔터프라이즈 규모의 도입에서는 컴퓨팅 클러스터, 데이터 레이크, 전용 라이선스에 수백만 달러 규모의 비용이 드는 경우가 많아, 소규모 독립 기업들에게는 풀스택 솔루션 도입을 주저하게 만드는 요인이 되고 있습니다. 데이터 현대화 프로젝트에서는 분석을 진행하기 전에 사일로화된 SCADA 시스템이나 히스토리안 시스템을 통합해야 하기 때문에 비용이 두 배로 늘어나는 경우가 빈번합니다. ‘Azure Data Manager for Energy’와 같은 클라우드 네이티브 서비스는 사업자에게 종량제 요금제 옵션을 제공하지만, 데이터 주권 및 지연 시간에 대한 우려로 인해 많은 중요한 워크로드는 여전히 On-Premise에서 운영되고 있습니다.
부문별 분석
2025년 석유 및 가스 분야 AI 시장 규모 중 61.05%는 업스트림 부문의 활동에서 비롯되었습니다. 이는 고도 분석이 필요한 지진 탐사 데이터 분석, 시추 자동화, 생산 최적화 워크플로우에 기인합니다. 이러한 이용 사례에서는 유정 위치 선정 및 완공 설계를 개선하기 위해 암석 물리학적, 지질 역학적, 시추 매개변수를 통합할 수 있는 패턴 인식 모델이 요구됩니다. 비전통적 저류층이 증가함에 따라, 업스트림 사업자들은 패드 개발 전반에 걸쳐 AI를 활용한 워크플로우를 지속적으로 확대하고 있으며, 이를 통해 석유 및 가스 시장의 AI 부문에서 주도적인 입지를 공고히 하고 있습니다.
대조적으로, 다운스트림 부문에서는 정유시설가 연료 혼합에 모델 예측 제어를, 실시간 품질 보증에 가상 센서를 도입함에 따라 2031년까지 해당 부문에서 가장 높은 연평균 성장률(CAGR) 14.12%를 나타낼 것으로 예측됩니다. 생성형 AI를 활용한 문서 처리로 규제 보고서 작성 주기가 단축되었으며, 컴퓨터 비전 알고리즘을 통해 증류탑 내부의 부식 핫스팟을 추적할 수 있게 되었습니다. 이러한 동향은 탐사 및 생산의 범위를 넘어선 AI의 추가적인 확산을 보여주며, 석유 및 가스 산업의 전체 AI 밸류체인에 걸친 통합적 최적화로의 전환을 반영하고 있습니다.
2025년에는 석유 및 가스 분야 AI 시장 관련 수익의 65.80%를 서비스 부문이 차지했으며, 사업자들이 자산 고유의 제약 조건에 맞추어 모델을 최적화하기 위해 해당 부문의 전문가를 선호하는 경향이 나타났습니다. 기업들이 지속적인 개선 주기를 통해 사업을 추진하는 가운데, 자문, 데이터 엔지니어링, 모델 유지보수 계약이 서비스 수익의 기반을 형성하고 있습니다.
한편, 각 사업자가 데이터 수집, 모델 관리, 용도 오케스트레이션의 표준화를 추진함에 따라 통합 플랫폼은 연평균 성장률(CAGR) 13.74%로 확대되고 있습니다. SLB의 ‘Lumi’와 베이커 휴즈(Baker Hughes)의 ‘Cordant(TM)’ 제품군은 대규모 언어 모델, 컴퓨터 비전 파이프라인, 물리학 기반 시뮬레이터를 통합한 다중 도메인 환경의 대표적인 사례입니다. 이러한 동향은 향후 노동 집약적인 도입 방식에서 기업 전체로 확장 가능한 구성 가능한 플랫폼으로의 전환을 시사하며, 이는 석유 및 가스 분야 AI 시장에 있어 중요한 전환점이 될 것입니다.
지역별 분석
북미는 2025년 매출의 35.95%를 차지했으며, 그 배경에는 활발한 셰일 개발과 자동화 시추 장비, 예측 유지보수 제품군, 메탄 누출 분석의 광범위한 도입이 있습니다. ExxonMobil, Chevron, Pioneer Natural Resources 등의 기업들은 성숙한 광섬유 및 5G 백본의 지원을 받아 페타바이트 규모의 클라우드 네이티브 지하 워크플로우를 운영하고 있습니다. 인프라 현대화를 위한 정부의 경제 부양책이 디지털화 확산을 더욱 촉진하는 한편, 활기찬 스타트업 생태계가 석유 및 가스 분야 AI 시장용 도구 개발을 가속화하고 있습니다.
유럽은 기술적으로 선진적이지만 시장 점유율은 비교적 작으며, 북해의 사업자들은 해양 로봇 공학 및 CCS(이산화탄소 포집 및 저장) 모니터링에 주력하고 있습니다. 탄소 집약도 및 메탄 배출에 관한 규제가, 특히 노르웨이와 네덜란드에서 AI를 활용한 환경 규정 준수를 촉진하고 있습니다. OSDU와 같은 개방형 데이터 표준에 관한 산업 간 협력은 상호 운용성을 촉진하고, 각 시설 간의 통합 과정에서 발생하는 마찰을 줄이고 있습니다.
아시아태평양은 인도, 인도네시아, 중국의 업스트림 부문에 대한 투자에 힘입어 연평균 성장률(CAGR) 14.41%로 가장 빠르게 성장하고 있는 지역입니다. PTTEP의 65가지 디지털 기능으로 구성된 포트폴리오와 인도 정유업체의 예측 유지보수 시범 사업은 기업 전반의 디지털화를 위한 지역적 전환을 여실히 보여주고 있습니다. LNG 수요 증가, 에너지 안보 목표, 소프트웨어 엔지니어 공급 증가는 석유 및 가스 분야 AI 시장 도입에 구조적인 호재를 가져오고 있습니다.
중동 및 아프리카에서는 국가 주도의 AI 프로그램과 메가 프로젝트 예산을 활용하여 데이터센터 및 슈퍼컴퓨팅 클러스터의 규모 확대를 추진하고 있습니다. ADNOC이 2024년에 AI를 통해 5억 달러의 가치를 창출한 것과 아람코(Aramco)의 METABRAIN LLM 이니셔티브는 역량이 급속히 향상되고 있음을 보여줍니다. 경제 다각화 및 탄소 중립 달성을 위한 정부의 이니셔티브는 누출 감지, 시추 자동화, 플레어 감축을 위한 분석에 대한 자금 확대로 이어지고 있으며, 석유 및 가스 분야 AI 시장이 지역적으로 더욱 탄력을 받고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the AI in the oil and gas market size was valued at USD 3.79 billion in 2025 and estimated to grow from USD 4.28 billion in 2026 to reach USD 7.91 billion by 2031, at a CAGR of 13.03% during the forecast period (2026-2031).
This report is Segmented by Operation (Upstream, Midstream, and Downstream), Solution Type (Platform and Services), Asset Location (Onshore and Offshore), Application (Quality Control, Production Optimisation, and More), AI Technique (Machine Learning, Deep Learning, and More), Deployment Mode (Cloud, On-Premises, and Edge), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global AI In Oil And Gas Market Trends and Insights
Ability to Process Complex Subsurface Big Data
Seismic archives exceeding 1,500 petabytes at leading operators now require AI accelerators capable of parsing decades of drilling, petrophysical, and production data within hours, lifting drilling-location accuracy by 70% compared with manual methods. ADNOC's ENERGYai agents trimmed geological-model build times by 75% through autonomous seismic analysis, allowing reservoir engineers to test multiple frac-cluster scenarios in minutes. The fusion of physics-informed neural networks with historical well data is enabling faster history matches across unconventional plays, directly improving capital-efficiency metrics for large pad developments.
Pressure to Cut Lifting-Costs Amid Price Volatility
Price swings continue to squeeze margins, prompting operators to pursue 25-50% drilling-cost reductions through AI-guided automation. Nabors Industries recorded 30% faster penetration rates after deploying automated drilling controls, while integrated production-optimization software slashed decision-cycle times from days to hours for Permian assets. Tachyus reported notable gains in artificial-lift efficiency by dynamically adjusting rod-pump parameters using reinforcement-learning algorithms. Mature-field operators increasingly view AI-assisted recovery as essential for extending economic lifespans.
High Up-Front CAPEX for AI Platforms
Enterprise-scale deployments often carry multimillion-dollar price tags for compute clusters, data lakes, and specialized licensing, deterring small independents from adopting full-stack solutions. Data-modernization projects frequently double costs, as siloed SCADA and historian systems must be harmonized before analytics can proceed. Cloud-native offerings such as Azure Data Manager for Energy give operators a consumption-based alternative, yet data sovereignty and latency concerns keep many critical workloads on-premises.
Other drivers and restraints analyzed in the detailed report include:
- Predictive-Maintenance Driven Downtime Reduction
- Fiber-Optic Sensor + AI for Real-Time Frac Optimization
- Scarcity of Oil-and-Gas Domain Data Scientists
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Upstream activities contributed 61.05% to the AI in the oil and gas market size in 2025, due to seismic interpretation, drilling automation, and production optimization workflows that require sophisticated analytics. These use cases demand pattern-recognition models capable of integrating petrophysical, geomechanical, and drilling parameters to improve well-placement and completion design. As unconventional reservoirs proliferate, upstream operators continue scaling AI-enabled workflows across pad developments, thereby cementing their share leadership within the AI in oil and gas market.
Downstream operations, in contrast, are forecast to post the segment's fastest 14.12% CAGR through 2031 as refineries adopt model-predictive control for fuel blending and virtual sensors for real-time quality assurance. Generative-AI-powered document processing is shortening regulatory-report cycles, and computer-vision algorithms now track corrosion hotspots inside distillation columns. The trajectory signals greater AI democratization beyond exploration and production, reflecting a shift toward integrated optimization across the entire value chain of AI in the oil and gas industry.
Services captured 65.80% of AI in the oil and gas market revenue in 2025, showcasing operators' preference for domain experts to tailor models to asset-specific constraints. Advisory, data engineering, and model-maintenance contracts form the backbone of service revenues as companies iterate toward continuous-improvement loops.
Integrated platforms, however, are expanding at a 13.74% CAGR as operators look to standardize data ingestion, model management, and application orchestration. SLB's Lumi and Baker Hughes' Cordant(TM) suites typify multi-domain environments that embed large language models, computer-vision pipelines, and physics-informed simulators. The trend suggests a future transition from labor-intensive deployments to configurable platforms that scale enterprise-wide, a key inflection for the AI in oil and gas market.
Complete Report Scope:
- By Operation
- Upstream
- Midstream
- Downstream
- By Solution Type
- Platform
- Services
- By Asset Location
- Onshore
- Offshore
- By Application
- Quality Control
- Production Optimisation
- Predictive Maintenance
- HS&E Compliance
- Exploration and Drilling
- Other Applications
- By AI Technique
- Machine Learning
- Deep Learning
- Computer Vision
- Natural Language Processing
- Other AI Techniques
- By Deployment Mode
- Cloud
- On-Premises
- Edge
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Singapore
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 35.95% of 2025 revenue, anchored by prolific shale developments and wide adoption of automated rigs, predictive-maintenance suites, and methane-leak analytics. Companies such as ExxonMobil, Chevron, and Pioneer Natural Resources run cloud-native subsurface workflows at petabyte scale, supported by mature fiber and 5G backbones. Government stimulation packages for infrastructure modernization further underpin digital uptake, while a thriving startup ecosystem accelerates tool creation for AI in the oil and gas market.
Europe maintains a technologically advanced yet smaller share, with North Sea operators focusing on offshore robotics and CCS monitoring. Regulations on carbon intensity and methane emissions propel AI-enabled environmental compliance, particularly in Norway and the Netherlands. Cross-sector collaboration on open data standards like OSDU fosters interoperability, reducing integration friction across installations.
Asia-Pacific is the fastest-growing region at a 14.41% CAGR, fueled by upstream investments in India, Indonesia, and China. PTTEP's portfolio of 65 digital features and Indian refiners' predictive-maintenance pilots illustrate a regional shift toward enterprise-wide digitization. Rising LNG demand, energy-security objectives, and a swelling pool of software engineers provide structural tailwinds for AI rollout across the AI in oil and gas market.
The Middle East and Africa region leverages sovereign AI programs and megaproject budgets to scale data centers and supercomputing clusters. ADNOC's generation of USD 500 million in AI value during 2024, along with Aramco's METABRAIN LLM initiative, signals rapid capability uplift. Government mandates for economic diversification and net-zero commitments are translating into expanded funding for leak-detection, drilling automatio,n and flare-reduction analytics, strengthening regional momentum within the AI in oil and gas market.
- C3.ai Inc.
- SparkCognition Inc.
- Uptake Technologies Inc.
- Tachyus Corporation
- Akselos SA
- IBM Corporation
- Microsoft Corporation
- Amazon Web Services Inc.
- Google Cloud LLC
- ABB Ltd.
- Honeywell International Inc.
- Schlumberger NV
- Halliburton Company
- Baker Hughes Company
- Siemens Energy AG
- Huawei Technologies Co. Ltd.
- Infosys Limited
- NVIDIA Corporation
- Cognite AS
- Wipro Limited
- Aspen Technology Inc.
- PETROSHELF LLC
- Arundo Analytics Inc.
- Kongsberg Digital AS
- Expert Petroleum SRL
- OPRO.ai Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ability to process complex subsurface big data
- 4.2.2 Pressure to cut lifting-costs amid price volatility
- 4.2.3 Predictive-maintenance driven downtime reduction
- 4.2.4 Fiber-optic sensor + AI for real-time frac optimization
- 4.2.5 Methane-leak AI monitoring to meet new ESG mandates
- 4.2.6 Autonomous AI-driven deep-water drilling systems
- 4.3 Market Restraints
- 4.3.1 High up-front CAPEX for AI platforms
- 4.3.2 Scarcity of oil-and-gas domain data-scientists
- 4.3.3 Cyber-risk at the offshore edge layer
- 4.3.4 Legacy SCADA interoperability gaps
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Investment Analysis
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Operation
- 5.1.1 Upstream
- 5.1.2 Midstream
- 5.1.3 Downstream
- 5.2 By Solution Type
- 5.2.1 Platform
- 5.2.2 Services
- 5.3 By Asset Location
- 5.3.1 Onshore
- 5.3.2 Offshore
- 5.4 By Application
- 5.4.1 Quality Control
- 5.4.2 Production Optimisation
- 5.4.3 Predictive Maintenance
- 5.4.4 HS&E Compliance
- 5.4.5 Exploration and Drilling
- 5.4.6 Other Applications
- 5.5 By AI Technique
- 5.5.1 Machine Learning
- 5.5.2 Deep Learning
- 5.5.3 Computer Vision
- 5.5.4 Natural Language Processing
- 5.5.5 Other AI Techniques
- 5.6 By Deployment Mode
- 5.6.1 Cloud
- 5.6.2 On-Premises
- 5.6.3 Edge
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Chile
- 5.7.2.4 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 India
- 5.7.4.3 Japan
- 5.7.4.4 South Korea
- 5.7.4.5 Malaysia
- 5.7.4.6 Singapore
- 5.7.4.7 Australia
- 5.7.4.8 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 United Arab Emirates
- 5.7.5.1.2 Saudi Arabia
- 5.7.5.1.3 Turkey
- 5.7.5.1.4 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Nigeria
- 5.7.5.2.3 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 C3.ai Inc.
- 6.4.2 SparkCognition Inc.
- 6.4.3 Uptake Technologies Inc.
- 6.4.4 Tachyus Corporation
- 6.4.5 Akselos SA
- 6.4.6 IBM Corporation
- 6.4.7 Microsoft Corporation
- 6.4.8 Amazon Web Services Inc.
- 6.4.9 Google Cloud LLC
- 6.4.10 ABB Ltd.
- 6.4.11 Honeywell International Inc.
- 6.4.12 Schlumberger NV
- 6.4.13 Halliburton Company
- 6.4.14 Baker Hughes Company
- 6.4.15 Siemens Energy AG
- 6.4.16 Huawei Technologies Co. Ltd.
- 6.4.17 Infosys Limited
- 6.4.18 NVIDIA Corporation
- 6.4.19 Cognite AS
- 6.4.20 Wipro Limited
- 6.4.21 Aspen Technology Inc.
- 6.4.22 PETROSHELF LLC
- 6.4.23 Arundo Analytics Inc.
- 6.4.24 Kongsberg Digital AS
- 6.4.25 Expert Petroleum SRL
- 6.4.26 OPRO.ai Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


