

|
시장보고서
상품코드
2122766
약국 자동화 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Pharmacy Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
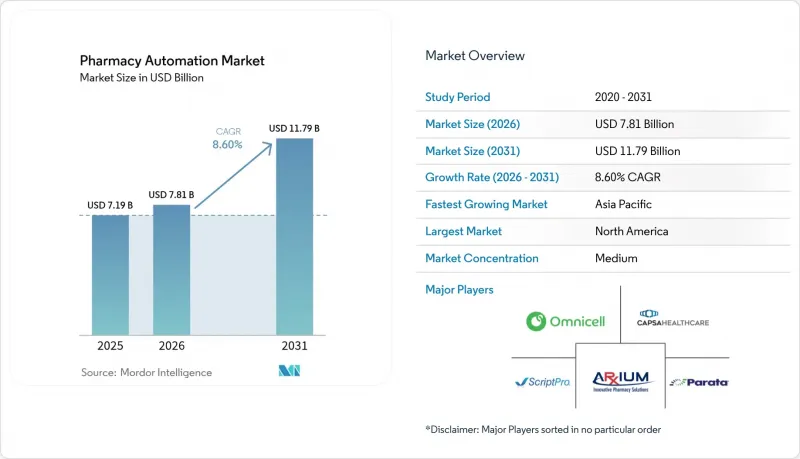
에 의하면, 약국 자동화 시장 규모는 2025년 71억 9,000만 달러로 평가되었습니다. 2026년 78억 1,000만 달러에서 2031년까지 117억 9,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 8.60%를 나타낼 것으로 예측됩니다.

본 보고서는 제품별(자동 조제 시스템, 기타), 최종 사용자별(병원 약국, 기타), 구축 모델별(집중형 자동화 허브, 분산형 포인트 오브 케어 장치), 약국 규모별(500개 점포 이상·250개 점포 이상, 기타),지역별(북미, 유럽, 아시아태평양, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 제시되어 있습니다.
세계의 약국 자동화 시장 동향 및 인사이트
의료비 증가와 디지털 전환(DX) 노력
국가 의료 예산 증가에 따라 의료 제공업체에게는 업무 비용 절감이 요구되고 있으며, 약국 자동화 시스템은 인건비 절감, 오류 감소, 정보 공유 의무 요건 준수를 동시에 실현할 수 있는 몇 안 되는 수단 중 하나임이 입증되었습니다. 병상 수 400개 규모의 대학병원에서는 집중형 로봇 시스템 도입을 통해 풀타임 환산 기준 12-18명 분량의 업무가 감소하여, 연간 120만-180만 미달러의 비용 절감으로 이어진 것이 입증되었습니다. ‘21세기 치료법(21st Century Cures Act)’에 따라 병원은 FHIR 인터페이스를 통해 의약품 데이터를 공개해야 할 의무가 있습니다. FHIR을 기본적으로 통합한 플랫폼이라면 미들웨어 비용을 절감하고 가치 창출까지 걸리는 시간을 단축할 수 있습니다. 클라우드 호스팅을 통해 병원 전체 약품 창고에 대한 가시성이 더욱 향상되어, 미배송 주문 발생 빈도를 30-40% 줄이고, 유효기간 만료로 인한 손실을 경감합니다. 현재 품질 보고 프로그램에서는 시스템에 의해 기록된 대조 지표를 제출한 기관에 보상이 지급되도록 되어 있어, 자동화는 재무 부문의 범위를 넘어 규제 대응 전략의 영역으로 확대되고 있습니다.
의약품 안전성과 규제 준수에 대한 관심 고조
미국에서는 투약 실수로 인한 사망자가 연간 7,000명을 넘으며, 조제 실수가 사고의 약 5분의 1을 차지하고 있습니다. 바코드 인증 기능이 탑재된 캐비닛이나 중량 측정식 조제기를 도입함으로써 오투약 사고의 85% 이상을 방지할 수 있으며, 이러한 성과는 현재 조인트 커미션(Joint Commission)의 조사에도 반영되고 있습니다. 2024년, FDA의 지침에 따라 인증된 전자 유통 시스템을 채택한 병원은 수동 스캔을 수행하지 않아도 ‘의약품 공급망 보안법(DSSA)’의 추적성 규정을 충족할 수 있음이 명확해졌습니다. 유럽의 ‘위조 의약품 지침’에서는 모든 포장에 고유 식별자를 부여할 것을 의무화하고 있으며, 이러한 작업 부하는 고속 자동화 라인에서만 처리할 수 있습니다. 미국 4개 주의 의료 과실 보험사는 로봇 도입 시 보험료를 5-10% 인하하는 혜택을 제공하고 있으며, 규정 준수 대응 능력이 수익을 지키는 자산이 되고 있습니다.
고액의 초기 투자 및 유지 관리 부담
300병상 규모 병원을 위한 통합 로봇 플랫폼 도입 비용은 150만-250만 달러이며, 연간 설비 투자액의 12-15%에 해당하는 서비스 계약이 필요하기 때문에 투자 회수 기간은 최장 6년에 달할 전망입니다. 하루 150건 이하의 처방전을 처리하는 독립 약국은 인건비 절감액이 정규직 직원 1명의 급여에도 미치지 못하는 경우가 많아 어려움을 겪고 있습니다. Parata 등의 벤더가 제공하는 구독 번들에서는 초기 투자를 월 3,500-5,000달러의 운영비로 전환할 수 있지만, 그럼에도 최소 이용량 조항이 마련되어 있어 비수기에는 사업자가 위약금을 물어야 할 위험에 노출됩니다. 부품 마모로 인해 연간 약 3만 달러의 유지비가 추가로 발생합니다. 서비스 제공 범위 150마일 밖의 지방 병원에서는 프리미엄 지원을 구매하지 않는 한, 엔지니어가 도착하기까지 48시간의 대기 시간이 발생합니다.
부문별 분석
로봇식 무균 조제 시스템은 서브마이크로그램 단위의 정밀도가 필요한 종양학 치료 요법에 대한 수요에 힘입어 2031년까지 연평균 성장률(CAGR) 10.43%로 성장할 전망이며, 약국 자동화 시장의 다른 어떤 제품 카테고리보다 빠른 속도로 확대될 것으로 예측됩니다. 자동 조제 시스템은 2025년에 매출 점유율의 47.43%를 차지하여 시장 침투가 진행되고 있음을 나타내는 한편, 도입 기반이 성숙해지고 있음을 시사합니다. ICU Medical의 FDA 승인 제품인 ‘IntelliMix’는 신생아의 정맥 내 영양 공급을 지원하며, 자동화가 급속히 필수화되고 있는 중대한 책임이 따르는 이용 사례를 개척하고 있습니다. 약국 자동화 시장에서 자동 정제 계수기에 할당되는 시장 규모는 여전히 소규모이지만, 1만 5,000-2만 5,000달러라는 도입 가격 덕분에 독립 약국의 관심을 계속 끌고 있습니다.
분석 중심의 소프트웨어 계층을 통해 하드웨어는 데이터 플랫폼으로 변모하고 있으며, 재고 발주 급증을 예측하고 재고를 사전에 준비함으로써 긴급 보충을 위한 이동을 40% 줄이고 있습니다. 자동 창고 시스템(ARS) 덕분에 피킹 시간이 8분에서 60초 이하로 단축되어, 인력을 비례적으로 늘리지 않고도 처리 능력이 향상되고 있습니다. 암 치료나 유전자 치료 프로토콜의 경우 1회 투여당 6자리 수의 비용이 소요된다는 점을 감안할 때, 폐쇄형 조제 시스템은 현재 지불 주체의 리스크 관리 전략에 통합되어 있으며, 약국 자동화 시장의 프리미엄 부문 성장을 뒷받침하고 있습니다.
병원 약국은 2025년 지출의 62.54%를 차지하며 약국 자동화 시장에서 중심적인 입지를 공고히 했지만, 약품 선반의 교체 주기가 느려짐에 따라 그 성장세는 둔화되고 있습니다. 대조적으로, 통신 판매 약국과 e-약국은 중앙 조제 메가 허브가 아마존식 처리 능력을 실현함에 따라 2031년까지 연평균 성장률(CAGR) 11.43%를 기록할 전망입니다. 소매 체인은 업무 통합을 추진하고 있으며, 월그린은 2024년에 미국 내 150개 매장을 폐쇄하고 그 취급량을 자동화된 지역 센터로 집약했습니다.
장기 요양 시설에서는 투약 시간을 30-40% 단축하는 투약 포장 로봇이 높은 평가를 받고 있습니다. 이는 인건비 절감으로 이어져, 낮은 환급률에도 불구하고 비용 회수가 가능해집니다. 또한, 생물학적 제제를 취급하는 전문 약국의 약국 자동화 시장 점유율이 상승하고 있습니다. 이는 로봇 기반 콜드체인 시스템이 수동 냉장고로는 보장하기 어려운 ±0.5℃의 온도 관리를 확실하게 실현하고 있기 때문입니다.
지역별 분석
북미는 2025년 전 세계 매출의 41.56%를 차지했으며, 그 원동력은 자동화된 대조 로그를 안전한 업무의 증거로 인정하는 메디케어의 품질 보고 보너스입니다. 병원 그룹은 응급실에 분산형 조제 캐비닛 도입을 추진하고 있으며, 긴급 처방전 처리 시간을 45분에서 8분 이하로 단축하고 있습니다. 캐나다의 각 주에서는 원격 모니터링 하에 지역 조제 센터의 검사 운영이 이루어지고 있으며, 이 모델은 로봇 기술을 활용하여 부족한 약사 인력을 집중시키고 있습니다. 멕시코의 사립 병원에서는 수익성이 높은 의료 관광 계약의 전제조건인 JCI(Joint Commission International) 기준을 충족하기 위해 조제 캐비닛을 도입하고 있습니다. 최신 FDA 지침에 따라 기계에 의한 조제 분량에 대한 책임 범위가 명확해짐에 따라, 미국의 외래수술센터(ASC)에서 조제 캐비닛 도입이 본격화되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 9.54%를 기록하며 가장 빠른 성장이 예상됩니다. 중국은 2027년까지 모든 3차 의료기관에 전자 처방전 라우팅을 의무화하고 있으며, 이 지침은 사실상 중앙 허브 및 AI 지원형 라우팅 엔진에 대한 수요를 선제적으로 이끌어낼 것입니다. 일본에서는 고령화 사회에 대응하기 위한 로봇 조제 장치에 대해 최대 50%의 보조금이 지급되고 있어, 지역 병원에서의 자동화가 정착되고 있습니다. 인도의 대형 민간 체인은 로봇식 무균 조제 장치를 활용해 암 치료 서비스를 차별화하고 있는 반면, 한국에서는 로봇이 반복적인 조제 업무를 처리한다는 전제 하에, 약사 주도의 치료 관리에 대한 보험 급여 심사 도입이 추진되고 있습니다. 호주의 보험 환급 산정 방식에서는 조만간 조제 오차율을 1% 이하로 억제한 사업자에게 포상이 주어질 예정이지만, 이 기준은 로봇 기술 없이는 달성하기가 거의 불가능합니다.
유럽의 진전은 ‘위조 의약품 지침’에 따른 추적성 규제에 좌우되고 있습니다. 해당 지침에서는 1회 투여 단위별 바코드 부착이 의무화되어 있으나, 이는 수작업 라인에서는 경제적으로 실행 불가능합니다. 독일에서는 400개가 넘는 약국 IT 시스템이 난립하여 통합 비용을 부풀리고 도입을 지연시키고 있습니다. 영국은 약사 부족 문제에 대처하기 위해 지역 허브에 주력하고 있는 반면, 프랑스는 2028년까지 의무화될 전국적인 추적·추적 가능성 데이터베이스 검사 운영을 진행하고 있습니다. 남유럽은 예산 부족과 조직의 분열로 인해 뒤처지고 있지만, 스페인과 이탈리아의 민간 기업 그룹은 해외 환자들을 통한 수익을 확보하기 위해 로봇 포장 시스템 도입을 서두르고 있습니다. 걸프협력회의(GCC) 회원국의 대형 병원에서의 조기 도입은 중동에서의 향후 가속화를 예고하지만, 한편 높은 수입 관세와 낮은 보험 환급액이 라틴아메리카에서의 확장을 여전히 제한하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the pharmacy automation market size is projected to expand from USD 7.19 billion in 2025 and USD 7.81 billion in 2026 to USD 11.79 billion by 2031, registering a CAGR of 8.60% between 2026 to 2031.
This report is Segmented by Product (Automated Medication Dispensing Systems, and More), End User (Hospital Pharmacies, and More), Deployment Model (Centralised Automation Hubs and Decentralised Point-Of-Care Units), Pharmacy Size (>500 Beds/>250 Stores, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Pharmacy Automation Market Trends and Insights
Rising Healthcare Expenditure and Digital Transformation Initiatives
Escalating national health budgets are putting pressure on providers to unlock operational savings, and automated pharmacy systems are proving to be one of the few levers that simultaneously cut labor costs, reduce errors, and satisfy information-sharing mandates. A 400-bed academic hospital demonstrated that centralized robotics eliminated 12-18 full-time equivalent roles, resulting in annual savings of USD 1.2-1.8 million. The 21st Century Cures Act obliges hospitals to expose medication data via FHIR interfaces; platforms with native FHIR integration avoid middleware fees and accelerate time-to-value. Cloud hosting further improves visibility across enterprise drug stores, reducing back-order frequency by 30-40% and mitigating expiry losses. Quality-reporting programs now reimburse facilities that submit machine-logged reconciliation metrics, pushing automation beyond the finance department into regulatory strategy.
Growing Focus on Medication Safety and Regulatory Compliance
Medication-error deaths exceed 7,000 annually in the United States, and dispensing mistakes cause roughly one-fifth of incidents. Barcode-verified cabinets and gravimetric compounders eliminate more than 85% of wrong-drug events, a performance now embedded in Joint Commission surveys. In 2024, FDA guidance clarified that hospitals using recognized electronic distribution systems can satisfy the Drug Supply Chain Security Act traceability rules without manual scanning. Europe's Falsified Medicines Directive enforces unique identifiers on every pack, a workload only high-speed automated lines can shoulder. Medical-malpractice insurers in four U.S. states are rewarding robotic installations with 5-10% premium cuts, turning compliance capability into a revenue-protecting asset.
High Upfront Capital and Maintenance Burden
A centralized robotic platform for a 300-bed hospital costs USD 1.5-2.5 million and requires service contracts priced at 12-15% of capital each year, extending the payback to as long as 6 years. Independent pharmacies running under 150 daily scripts struggle because their labor savings seldom equal even one full-time salary. Subscription bundles from vendors such as Parata convert capital into monthly operating fees of USD 3,500-5,000 but still require minimum-volume clauses that expose operators to penalties in low-season months. Component wear adds roughly USD 30,000 in annual upkeep. Rural hospitals outside 150-mile service radii face 48-hour wait times for engineers unless they purchase premium support.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Labor Shortages in the Pharmacy Workforce
- Expansion of Telehealth and E-Pharmacy Channels
- Interoperability Challenges with Legacy IT Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Robotic sterile compounding systems will grow at a 10.43% CAGR through 2031, faster than any other product category in the pharmacy automation market, driven by oncology regimens that require sub-microgram accuracy. Automated medication dispensing commanded 47.43% revenue share in 2025, illustrating scale penetration but also signaling a maturing installed base. ICU Medical's FDA-cleared IntelliMix supports neonatal parenteral nutrition, opening high-liability use cases where automation is rapidly becoming non-negotiable. The pharmacy automation market size allocated to automated tablet counters remains modest, yet their entry price of USD 15,000-25,000 keeps independents engaged.
Analytics-driven software layers are turning hardware into data platforms that predict stock-order spikes and pre-stage inventory, cutting emergency restock trips by 40%. Automated storage and retrieval systems reduce pick times from eight minutes to under 60 seconds, increasing throughput without proportional staffing. Given that oncology and gene-therapy protocols incur six-figure per-dose costs, closed-system compounders are now bundled into payer risk-management strategies, reinforcing premium-tier growth inside the pharmacy automation market.
Hospital pharmacies absorbed 62.54% of 2025 expenditure, cementing their centrality in the pharmacy automation market, yet their growth is slowing as cabinet refresh cycles taper. In contrast, mail-order and ePharmacies will post an 11.43% CAGR to 2031 as central-fill megahubs replicate Amazon-style throughput. Retail chains are consolidating operations; Walgreens closed 150 U.S. locations in 2024 and channeled volume to automated regional centers.
Long-term-care facilities value dose-packaging robots that cut medication-pass time 30-40%, a labor offset that enables cost recapture despite low reimbursement. The pharmacy automation market share accruing to specialty pharmacies handling biologics is climbing because robotic cold-chain systems assure +-0.5 °C compliance that manual fridges struggle to guarantee.
Complete Report Scope:
- By Product
- Automated Medication Dispensing Systems
- Automated Packaging & Labeling Systems
- Automated Table-top Tablet Counters
- Automated Storage & Retrieval Systems
- Robotic Sterile Compounding Systems
- Pharmacist Workflow & Analytics Software
- By End User
- Hospital Pharmacies (In-patient, Out-patient)
- Retail & Chain Pharmacies
- Mail-order / ePharmacies
- Long-term-care & Specialty Pharmacies
- By Deployment Model
- Centralised Automation Hubs
- Decentralised Point-of-Care Units
- By Pharmacy Size
- >500 beds / >250 stores
- 100-499 beds / 50-249 stores
- <100 beds / Independent stores
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 41.56% of 2025 global revenue, anchored by Medicare quality-reporting bonuses that acknowledge automated reconciliation logs as evidence of safe practice. Hospital groups are pushing decentralized cabinets into emergency departments, cutting stat-order cycle times from 45 minutes to under 8. Canada's provinces pilot regional compounding centers supervised remotely, a model that leverages robotics to pool scarce pharmacist labor. Mexico's private hospitals deploy dispensing cabinets to meet Joint Commission International standards, a prerequisite for lucrative medical-tourism contracts. The latest FDA guidance clarified liability boundaries for machine-dispensed doses, unfreezing procurement across U.S. ambulatory surgery centers.
Asia-Pacific will record the fastest growth, with a 9.54% CAGR through 2031. China mandates e-prescription routing for all tertiary hospitals by 2027, an edict that effectively pre-installs demand for central hubs and AI-assisted routing engines. Japan subsidizes up to 50% of robotic compounders serving aging populations, normalizing automation in community hospitals. India's major private chains are differentiating oncology services with robotic sterile compounders, while South Korea pilots reimbursements for pharmacist-led therapy management that presuppose robots handle repetitive dispensing. Australia's reimbursement formula will soon reward operators who keep dispensing error rates below 1%, a threshold nearly impossible to achieve without robotics.
Europe's progress pivots on traceability rules under the Falsified Medicines Directive, which require unit-dose barcoding that manual lines cannot execute economically. Germany's patchwork of more than 400 pharmacy IT systems inflates integration costs and slows uptake. The United Kingdom focuses on regional hubs to address pharmacist shortages, while France is piloting a national track-and-trace database that will be mandatory by 2028. Southern Europe lags due to budget and organizational fragmentation, yet private groups in Spain and Italy are racing to adopt robotic packaging to secure international patient revenue. Early deployments in Gulf Cooperation Council megahospitals hint at future acceleration in the Middle East, whereas high import tariffs and thin reimbursement continue to cap Latin American expansion.
- Accu-Chart Plus Healthcare Systems
- Arxium
- Baxter
- BD (Becton, Dickinson & Co.)
- Capsa Healthcare
- Grifols (LogiFill)
- ICU Medical (IntelliMix)
- Innotech Espana (Rowa)
- Mckesson
- NewIcon Oy
- Omnicell
- Oracle Health (Cerner Rx)
- Parata Systems
- Pearson Medical Technologies
- RxSafe
- ScriptPro
- Swisslog Healthcare
- Talyst Systems (Swisslog)
- TouchPoint Medical
- Yuyama Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Healthcare Expenditure and Digital Transformation Initiatives
- 4.2.2 Growing Focus on Medication Safety and Regulatory Compliance
- 4.2.3 Increasing Labor Shortages in Pharmacy Workforce
- 4.2.4 Expansion of Telehealth and E-Pharmacy Channels
- 4.2.5 Accelerating Adoption of Artificial Intelligence and Robotics
- 4.2.6 Integration of Cloud-Based Platforms and Software-as-a-Service Models
- 4.3 Market Restraints
- 4.3.1 High Upfront Capital and Maintenance Burden
- 4.3.2 Interoperability Challenges with Legacy IT Systems
- 4.3.3 Data Privacy, Cybersecurity, and Compliance Risks
- 4.3.4 Uncertain Return on Investment for Small and Rural Pharmacies
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Automated Medication Dispensing Systems
- 5.1.2 Automated Packaging & Labeling Systems
- 5.1.3 Automated Table-top Tablet Counters
- 5.1.4 Automated Storage & Retrieval Systems
- 5.1.5 Robotic Sterile Compounding Systems
- 5.1.6 Pharmacist Workflow & Analytics Software
- 5.2 By End User
- 5.2.1 Hospital Pharmacies (In-patient, Out-patient)
- 5.2.2 Retail & Chain Pharmacies
- 5.2.3 Mail-order / ePharmacies
- 5.2.4 Long-term-care & Specialty Pharmacies
- 5.3 By Deployment Model
- 5.3.1 Centralised Automation Hubs
- 5.3.2 Decentralised Point-of-Care Units
- 5.4 By Pharmacy Size
- 5.4.1 >500 beds / >250 stores
- 5.4.2 100-499 beds / 50-249 stores
- 5.4.3 <100 beds / Independent stores
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)}
- 6.3.1 Accu-Chart Plus Healthcare Systems
- 6.3.2 Arxium
- 6.3.3 Baxter International Inc.
- 6.3.4 BD (Becton, Dickinson & Co.)
- 6.3.5 Capsa Healthcare
- 6.3.6 Grifols (LogiFill)
- 6.3.7 ICU Medical (IntelliMix)
- 6.3.8 Innotech Espana (Rowa)
- 6.3.9 McKesson Corporation
- 6.3.10 NewIcon Oy
- 6.3.11 Omnicell Inc.
- 6.3.12 Oracle Health (Cerner Rx)
- 6.3.13 Parata Systems LLC
- 6.3.14 Pearson Medical Technologies
- 6.3.15 RxSafe LLC
- 6.3.16 ScriptPro LLC
- 6.3.17 Swisslog Healthcare
- 6.3.18 Talyst Systems (Swisslog)
- 6.3.19 TouchPoint Medical
- 6.3.20 Yuyama Co. Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


