|
시장보고서
상품코드
2122802
수의용 초음파 기기 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Veterinary Ultrasound Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
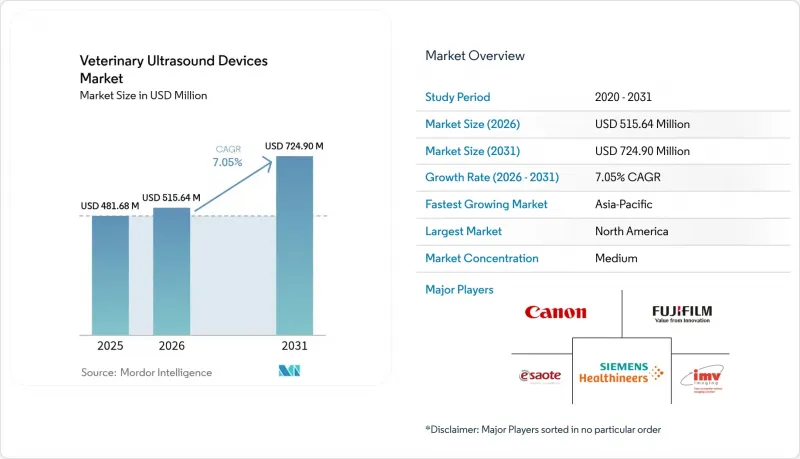
에 의하면, 수의용 초음파 기기 시장 규모는 2025년 4억 8,168만 달러로 평가되었습니다. 2026년에는 5억 1,564만 달러로 확대되어 2031년까지 7억 2,490만 달러에 이를 것으로 예상되고 2026-2031년에 걸쳐 CAGR 7.05%로 성장할 전망입니다.

본 보고서는 휴대성(휴대용 초음파 기기, 탁상형 초음파 기기, 카트·트롤리형 초음파 기기), 기술(2D 초음파, 도플러 초음파, 3D/4D 초음파, 조영 초음파), 용도(산부인과, 기타),동물 유형(반려동물, 기타), 최종 사용자(동물병원, 기타), 지역(북미, 유럽, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 수의용 초음파 기기 시장 동향 및 인사이트
증가하는 반려동물의 의료비
2023년, 미국의 반려동물 주인들은 수의학 치료에 383억 달러를 지출했으며, 보험에 가입된 반려동물은 미가입 반려동물에 비해 2.4배 더 많은 영상 검사를 받고 있습니다. 현재 기업 그룹이 미국 동물 병원의 4분의 1 이상을 소유하고 있어, 이를 통해 일괄 조달 및 초음파 검사 프로토콜의 표준화가 가능해졌습니다. 고령 반려동물을 대상으로 한 선택적 복부 및 심장 초음파 검사는 점점 더 일상화되고 있지만, 2024년 동물병원 내원자 수의 감소는 선택적 영상 검사가 여전히 거시경제적 압력에 민감함을 보여줍니다. 표준화된 공급업체와의 서비스 계약은 병원이 유지보수 비용을 절감하는 데 도움이 되며, 경기 침체기에도 수익을 안정적으로 유지하는 데 기여하고 있습니다. 전반적으로, 내원 환자 수가 변동하더라도 진단 마진을 유지할 수 있는 가격 부담이 적고 사용하기 쉬운 스캐너에 대한 수요가 지속되고 있습니다.
휴대용 초음파 기기의 보급 확대
칩 기반 트랜스듀서로 인해 제조 비용이 절감되고 장비의 설치 면적이 축소됨에 따라, 핸드헬드형 프로브 시장은 연평균 성장률(CAGR) 9.43%로 시장을 확대되고 있습니다. 2024년 1월에 승인된 Butterfly의 iQ3는 방사선과 전문의가 아니더라도 해부학적 구조를 신속하게 식별할 수 있는 자동 3D 모델을 도입했습니다. 한편, Sound Technologies가 판매하는 GE의 Vscan Air는 말 마구간에서의 진찰에 무선 영상 기술을 도입하고 있습니다.월800달러 이하의 리스 플랜을 통해 초기 비용이 80% 절감되어, 의사 1명이 운영하는 클리닉에서의 도입이 촉진되고 있습니다. 휴대성은 카트형 시스템이 실용적이지 않은 대형 동물 진료나 응급 처치 케이지에서 특히 가치가 있지만, 비만 환자나 복부 심부 스캔에서는 여전히 영상 투과성이 제한적입니다. Wi-Fi를 통해 제공되는 지속적인 소프트웨어 업그레이드를 통해 클리닉은 수년에 걸친 상환 기간 동안에도 기술의 노후화를 피할 수 있습니다.
고성능 초음파 장치의 높은 도입 비용
도플러 및 조영 모듈을 갖춘 고급 카트형 시스템의 가격은 1만 5,000-5만 달러로, 주당 평균 10회 이하의 검사를 수행하는 클리닉에게는 큰 장벽이 됩니다. 휴대용 기기의 소매 가격은 3,999-8,000달러이지만, 대형 동물의 복부 검사에 필요한 심부 침투력이 부족하기 때문에 클리닉은 가격과 성능의 균형을 타협할 수밖에 없습니다. 하드웨어, 소프트웨어, 서비스를 단일 월정액 요금에 묶은 구독형 번들은 위험을 줄여주지만, 진료 건수가 적은 지방 클리닉의 경우 일반적인 5년 계약 기간 내에 손익분기점에 도달하는 데 여전히 어려움을 겪고 있습니다. 기업형 통합 사업자는 장비 대량 구매를 통해 할인을 협상할 수 있는 반면, 독립 개업의는 상대적으로 비용 면에서 불리한 입장에 놓여 있습니다.
부문별 분석
카트형 시스템은 발표 병원에서 높이 평가받는 뛰어난 화질, 프로브의 다양성, 인체공학에 기반한 콘솔 덕분에 2025년 시점에서 수의학용 초음파 기기 시장의 48.53% 점유율을 유지했습니다. 이러한 시스템은 특히 비만견이나 대형견의 경우, 심부 복부, 심장, 유도 하 중재 검사용으로 최적의 플랫폼으로 자리매김하고 있습니다. 각 벤더사는 다중 주파수 프로브와 통합형 PACS 링크를 번들로 제공하여 기존 워크플로우와의 호환성을 확보하고 있습니다.
핸드헬드형 장치는 8,000달러 이하의 가격대와 단일 프로브를 통한 범용성이 1차 진료 클리닉의 관심을 끌고 있어 연평균 성장률(CAGR) 9.43%로 성장하고 있습니다. 구독 모델을 통해 계약 기간 중 새로운 버전으로의 업그레이드가 가능하기 때문에 이 부문의 수의학용 초음파 기기 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 반도체 트랜스듀서의 채택으로 이미지 해상도는 지속적으로 향상되고 있으며, 군사 규격에 부합하는 낙하 내구성 덕분에 이러한 기기는 농장 방문 진료에도 활용될 수 있습니다. 다만, 침투 깊이와 배터리 구동 시간의 제한이 있어 복잡한 심장 검사나 대형 동물의 복부 스캔에는 여전히 카트형 장비가 선호되고 있습니다.
2차원 시스템은 비교적 저렴한 비용으로 일상적인 복부 및 산과적 요구를 충족시키기 때문에 2025년에는 매출의 56.92%를 차지했습니다. 부팅 시간이 짧고 익숙한 인터페이스 덕분에 진료 건수가 많은 시설에서도 효율적인 워크플로우가 유지되고 있습니다. 2차원 수의학용 초음파 장치 시장은 계속해서 성장할 전망이지만, 그 점유율은 점차 도플러 플랫폼으로 이동할 것으로 보입니다.
클리닉에서 심초음파 검사를 도입하고, 축산 농업 종사자들이 황체(코르푸스 루테움)의 혈류 평가를 채택함에 따라, 도플러 장치는 연평균 성장률(CAGR) 9.32%로 발전하고 있습니다. 각 벤더들이 중급급 카트형 장비나 휴대형 장비에도 이 기능을 탑재하고 있기 때문에 수의용 초음파 기기 시장에서 도플러의 점유율은 더욱 상승할 전망입니다. 현재 연수 프로그램에서는 초기 단계부터 도플러의 기초를 가르치고 있어 사용자층이 확대되고 있습니다. 3차원 및 4차원 이미징은 장비 비용과 스캔 시간이 길다는 점 때문에 여전히 교육 병원에 한정된 틈새 시장으로 남아 있지만, 그 체적 데이터는 복잡한 심장 외과 수술 계획 수립에 도움이 되고 있습니다.
지역별 분석
2025년에는 환자 1인당 높은 의료비와 POCUS의 조기 도입에 힘입어 북미가 42.54%의 점유율로 1위를 차지했습니다. 미국의 기업 그룹은 전국 규모의 장비 계약을 협상 중이며, 이는 통합 아카이브 기능을 갖춘 벤더의 판매 대수를 끌어올리고 있습니다. 캐나다와 멕시코에서는 젖소와 육우 생산자들이 생식 초음파 검사 프로토콜을 공식적으로 도입함에 따라 꾸준히 성장하고 있습니다. 2024년에는 인플레이션으로 인해 선택적 검진이 위축되었으나, 리스 계획이 예산에 미치는 타격을 완화하여 장비 교체 주기를 유지하고 있습니다.
아시아태평양은 가축 질병 모니터링에 대한 정부의 의무화 조치와 대도시권 내 반려동물 사육 마릿수 증가를 배경으로 연평균 성장률(CAGR) 8.54%를 기록하며 가장 빠르게 성장하고 있는 지역입니다. 중국의 거대한 양돈·낙농 부문이 카트형 장비 도입을 주도하고 있는 반면, 일본과 한국에서는 소동물 심장학 용도로 소형 도플러 장비가 선호되고 있습니다. 인도의 협동조합 계열 낙농장에서는 휴대용 스캐너가 도입되고 있지만, 훈련을 받은 사업자의 부족으로 인해 농촌 지역으로의 보급은 더딘 상황입니다. 호주의 클리닉은 얼리 어답터로서의 역할을 수행하고 있으며, 지역 확대에 앞서 AI 모듈 검사를 도입하고 있습니다.
유럽에서는 엄격한 동물 복지 규제와 높은 반려동물 보유율에 힘입어 견조한 수요가 유지되고 있습니다. 독일, 프랑스, 영국이 매출의 대부분을 차지하고 있으며, EU 사이버 복원력법에 따라 2027년 12월부터 5년간의 패치 지원이 의무화됨에 따라, 사이버 보안 대책을 마련하고 있는 벤더 간 시장 지배력이 더욱 강화될 가능성이 있습니다. 동유럽에서는 수의학 인프라의 현대화에 따라 시장이 확대되고 있습니다. 중동에서는 말의 스포츠 의학에 초점이 맞추어져 있으며, 라틴아메리카에서는 육우의 번식 관리에 초음파가 활용되고 있지만, 비용상의 제약으로 인해 휴대용 초음파 장치의 광범위한 보급은 저해되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the veterinary ultrasound devices market size is expected to increase from USD 481.68 million in 2025 to USD 515.64 million in 2026 and reach USD 724.90 million by 2031, growing at a CAGR of 7.05% over 2026-2031.
This report is Segmented by Portability (Handheld, Table-Top, and Cart/Trolley-Based), Technology (2-D, Doppler, 3-D/4-D, and Contrast-Enhanced), Application (Obstetrics & Gynecology, and More), Animal Type (Companion Animals, Nd More), End User (Veterinary Clinics, and More), and Geography (North America, Europe, and More). Market Forecasts are Provided in Terms of Value (USD).
Global Veterinary Ultrasound Devices Market Trends and Insights
Rising Companion Animal Healthcare Expenditure
Pet owners in the United States spent USD 38.3 billion on veterinary care in 2023, and insured pets undergo 2.4 times more imaging than uninsured cohorts. Corporate groups now own more than one-quarter of U.S. clinics, enabling fleet procurement and standardized ultrasound protocols. Elective abdominal and cardiac scans for geriatric pets are increasingly routine, yet the 2024 decline in clinic visits shows that discretionary imaging remains sensitive to macroeconomic pressures. Standardized vendor service contracts are helping clinics contain maintenance costs, smoothing revenue during slowdowns. The overall effect is sustained demand for affordable, easy-to-use scanners that preserve diagnostic margins even when visit volumes fluctuate.
Increasing Adoption of Handheld Ultrasound Devices
Handheld probes are expanding at a 9.43% CAGR as chip-based transducers cut manufacturing costs and shrink device footprints. Butterfly's iQ3, cleared in January 2024, introduced automated 3D models that expedite anatomy identification for non-radiologists, while GE's Vscan Air, distributed by Sound Technologies, brings wireless imaging to stall-side equine exams. Monthly leasing plans under USD 800 reduce upfront outlays by 80%, encouraging adoption in single-doctor clinics. Portability is most valuable in large-animal practice and in emergency cages, where cart systems are impractical, though image penetration remains limited in obese patients and in deep-abdomen scans. Continuous software upgrades delivered over Wi-Fi help practices avoid technology obsolescence during multi-year repayment schedules.
High Capital Cost of Advanced Ultrasound Systems
Premium cart systems with Doppler and contrast modules range from USD 15,000 to USD 50,000, a hurdle for clinics averaging fewer than 10 scans per week. Handheld units retail for USD 3,999-8,000 but lack depth penetration for large-animal abdomen work, forcing practices to compromise between price and capability. Subscription bundles that wrap hardware, software, and service into a single monthly fee lower risk, yet rural clinics with low case volume still struggle to meet breakeven within a typical five-year term. Corporate consolidators negotiate fleet discounts, putting independent practitioners at a relative cost disadvantage.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Artificial Intelligence and Tele-Ultrasound Workflows
- Growing Demand for Reproductive Monitoring in Intensive Livestock Farming
- Shortage of Ultrasound-Trained Veterinary Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cart systems retained 48.53% veterinary ultrasound devices market share in 2025 due to superior image quality, probe diversity, and ergonomic consoles prized by referral hospitals. They remain the platform of choice for deep abdominal, cardiac, and guided interventional studies, especially in obese or large-breed dogs. Vendors bundle multi-frequency probes and integrated PACS links, ensuring compatibility with existing workflows.
Handheld devices are growing at a 9.43% CAGR as sub-USD 8,000 pricing and single-probe versatility attract primary-care clinics. The veterinary ultrasound devices market size for this segment is projected to expand steadily as subscription models allow users to upgrade to newer revisions mid-contract. Image resolution continues to improve through semiconductor transducers, and military-drop specifications make these units viable for barn calls. Limitations in penetration depth and battery life still favor carts for complex cardiology or large-animal abdomen scans.
Two-dimensional systems accounted for 56.92% of revenue in 2025 because they meet routine abdominal and obstetric needs at comparatively low cost. Rapid boot times and familiar interfaces keep workflow efficient for high-volume practices. The veterinary ultrasound devices market for 2-D will continue to grow, though the share will shift incrementally to Doppler platforms.
Doppler units are advancing at a 9.32% CAGR as clinics embrace echocardiography and livestock breeders adopt blood-flow assessment of the corpus luteum. The veterinary ultrasound devices market share for Doppler is set to rise further, with vendors embedding the feature in mid-tier carts and even handheld devices. Training programs now teach Doppler basics early, broadening the user base. Three- and four-dimensional imaging remains niche, limited to teaching hospitals due to equipment cost and longer scan times, yet its volumetric data aids complex cardiac surgical planning.
Complete Report Scope:
- By Portability
- Handheld Ultrasound
- Table-Top Ultrasound
- Cart/Trolley-Based Ultrasound
- By Technology
- 2-Dimensional Ultrasound
- Doppler Ultrasound
- 3-D/4-D Ultrasound
- Contrast-Enhanced Ultrasound
- By Application
- Obstetrics & Gynecology
- Cardiology
- Musculoskeletal
- Abdominal & Internal Medicine
- Emergency & Critical Care
- By Animal Type
- Companion Animals
- Dogs
- Cats
- Other Small Companion Animals
- Livestock Animals
- Horse
- Cattle
- Other Livestock Animals
- Other Animals
- Companion Animals
- By End User
- Veterinary Clinics
- Veterinary Hospitals
- Other End Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with a 42.54% share in 2025, driven by high per-patient spending and early POCUS adoption. U.S. corporate groups negotiate nationwide equipment deals, boosting vendor volume for integrated archiving. Canada and Mexico are growing steadily as dairy and beef producers formalize reproductive ultrasound protocols. Inflation curtailed elective visits in 2024, but leasing plans soften budget shocks, sustaining replacement cycles.
Asia-Pacific is the fastest-growing region, with a 8.54% CAGR, underpinned by government mandates for livestock disease surveillance and expanding pet ownership in megacities. China's vast swine and dairy sectors drive cart deployments, while Japan and South Korea favor compact Doppler units for small-animal cardiology. India's cooperative dairies adopt portable scanners, though a shortage of trained users slows rural penetration. Australian clinics act as early adopters, trialing AI modules before regional rollout.
Europe maintains solid demand, spurred by stringent animal welfare rules and high pet ownership. Germany, France, and the United Kingdom dominate revenue, and the EU Cyber Resilience Act will obligate five-year patch support from December 2027, likely consolidating market power among cybersecurity-prepared vendors. Eastern Europe expands as veterinary infrastructure modernizes. The Middle East focuses on equine sports medicine, and Latin America leverages ultrasound for beef herd fertility, though cost constraints hinder mass adoption of handheld ultrasound.
- Butterfly Network Inc.
- Canon
- Chison Medical Technologies Co. Ltd
- Clarius Mobile Health Corp.
- DRAMI?SKI SA
- E.I. Medical Imaging
- Edan Instruments Inc.
- Esaote
- FUJIFILM Sonosite Inc.
- GE Healthcare
- Healcerion Co. Ltd
- Heska
- IMV Imaging
- Kaixin Electronic Instrument Co. Ltd
- Mindray Bio-Medical Electronics Co. Ltd
- Samsung Group
- Siemens Healthineers
- Sonostar Technologies Co. Ltd
- SonoScape Medical Corp.
- Telemed Medical Systems
- Xuzhou Palmary Electronics Co. Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Companion Animal Healthcare Expenditure
- 4.2.2 Increasing Adoption of Handheld Ultrasound Devices
- 4.2.3 Technological Advancements in Veterinary Ultrasound Imaging
- 4.2.4 Growing Demand for Reproductive Monitoring In Intensive Livestock Farming
- 4.2.5 Emergence of Subscription-Based Ultrasound Equipment Models
- 4.2.6 Integration of Artificial Intelligence and Tele-Ultrasound Workflows
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of Advanced Ultrasound Systems
- 4.3.2 Shortage of Ultrasound-Trained Veterinary Professionals
- 4.3.3 Limited Reimbursement for Large-Animal Diagnostic Imaging
- 4.3.4 Cybersecurity Concerns Over Cloud-Connected Ultrasound Devices
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Sustainability & ESG Considerations
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat Of New Entrants
- 4.8.2 Bargaining Power Of Buyers
- 4.8.3 Bargaining Power Of Suppliers
- 4.8.4 Threat Of Substitute Products
- 4.8.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Portability
- 5.1.1 Handheld Ultrasound
- 5.1.2 Table-Top Ultrasound
- 5.1.3 Cart/Trolley-Based Ultrasound
- 5.2 By Technology
- 5.2.1 2-Dimensional Ultrasound
- 5.2.2 Doppler Ultrasound
- 5.2.3 3-D/4-D Ultrasound
- 5.2.4 Contrast-Enhanced Ultrasound
- 5.3 By Application
- 5.3.1 Obstetrics & Gynecology
- 5.3.2 Cardiology
- 5.3.3 Musculoskeletal
- 5.3.4 Abdominal & Internal Medicine
- 5.3.5 Emergency & Critical Care
- 5.4 By Animal Type
- 5.4.1 Companion Animals
- 5.4.1.1 Dogs
- 5.4.1.2 Cats
- 5.4.1.3 Other Small Companion Animals
- 5.4.2 Livestock Animals
- 5.4.2.1 Horse
- 5.4.2.2 Cattle
- 5.4.2.3 Other Livestock Animals
- 5.4.3 Other Animals
- 5.4.1 Companion Animals
- 5.5 By End User
- 5.5.1 Veterinary Clinics
- 5.5.2 Veterinary Hospitals
- 5.5.3 Other End Users
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global-Level Overview, Market-Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)
- 6.3.1 Butterfly Network Inc.
- 6.3.2 Canon Inc.
- 6.3.3 Chison Medical Technologies Co. Ltd
- 6.3.4 Clarius Mobile Health Corp.
- 6.3.5 DRAMI?SKI SA
- 6.3.6 E.I. Medical Imaging
- 6.3.7 Edan Instruments Inc.
- 6.3.8 Esaote SpA
- 6.3.9 FUJIFILM Sonosite Inc.
- 6.3.10 GE HealthCare
- 6.3.11 Healcerion Co. Ltd
- 6.3.12 Heska Corporation
- 6.3.13 IMV Imaging
- 6.3.14 Kaixin Electronic Instrument Co. Ltd
- 6.3.15 Mindray Bio-Medical Electronics Co. Ltd
- 6.3.16 Samsung Medison Co. Ltd
- 6.3.17 Siemens Healthineers GmbH
- 6.3.18 Sonostar Technologies Co. Ltd
- 6.3.19 SonoScape Medical Corp.
- 6.3.20 Telemed Medical Systems
- 6.3.21 Xuzhou Palmary Electronics Co. Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment