

|
시장보고서
상품코드
2122809
바이오버든 시험 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Bioburden Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
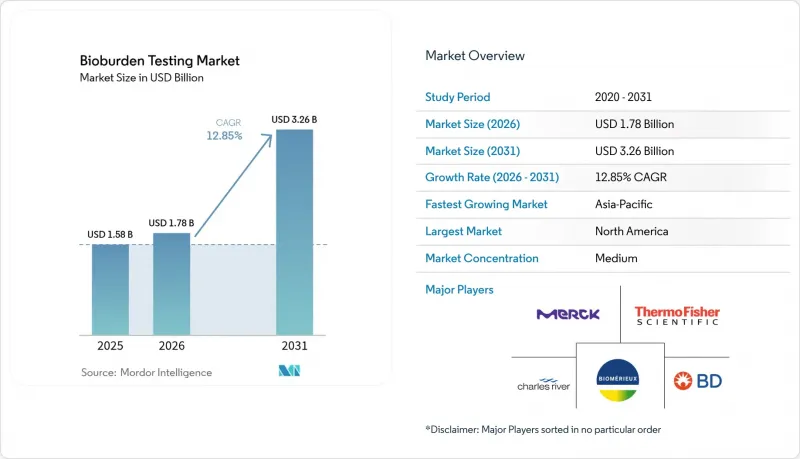
바이오버든 시험 시장 규모는 2025년에 15억 8,000만 달러로 평가되었습니다. 2026년 17억 8,000만 달러에서 2031년까지 32억 6,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 12.85%를 나타낼 전망입니다.

본 보고서는 제품별(장비(PCR 시스템 등) 및 소모품(배양 배지·시약 등)), 검출 방법별(막 여과법, 플레이트 계수법 등), 용도별(원자재 검사, 공정 내 검사 등), 최종 사용자별(의료기기 제조업체 등), 지역별(북미 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 바이오버든 시험 시장 동향 및 인사이트
신속한 출하를 중시하는 공급망이 초래하는 잦은 제품 리콜
잇따른 리콜은 속도를 중시하는 물류 체제 하에서는 일상적인 검사에서도 오염 물질이 간과될 가능성이 있음을 여실히 보여주고 있습니다. 2024년 FDA가 발표한 설파메톡사졸/트리메토프림 정제 및 아토바콴 현탁액에 관한 공지는 미생물 관리의 부실로 인한 막대한 손실을 여실히 보여주었습니다. 현재 각 제약사는 수개월에 걸친 가동 중단이나 브랜드 이미지 훼손에 비해 예방적 검사가 비용 면에서 더 유리하다는 점을 인식하고 있습니다. 이익률이 낮은 제네릭 의약품 제조업체들은 이러한 압박을 가장 크게 느끼고 있으며, 그 결과 정기적인 샘플링량이 증가하고, 바이오버든 시험 시장은 필수적인 품질 관리의 관문으로 자리매김하고 있습니다.
무균성 규정 준수를 위한 엄격한 cGMP 및 ISO 13485 감사
2024년 미국 품질 관리 시스템 규정에 따라 국내 규정이 ISO 13485에 부합하게 되었으며, 문서화 및 실시간 모니터링 기준이 강화되었습니다. PIC/S 부속서 1의 개정에 따라, 정기적인 점검이 아닌 지속적인 모니터링이 요구되고 있습니다. 사노피의 매사추세츠 주 공장에서 검사 결과의 20%가 불합격 판정을 받았을 때, 규제 당국은 과거의 오염률을 지적하며 동종 업계 다른 기업들에게 자동 경보 및 감사에 대응 가능한 데이터 트레일 도입을 촉구했습니다. 이러한 요건으로 인해 바이오버든 검사 시장 전반에서 장비 판매 및 소프트웨어 구독이 확대되고 있습니다.
자동 계수 플랫폼의 높은 초기 비용
Rapid Micro Biosystems사의 ‘Growth Direct’와 같은 시스템은 검증 비용을 제외하더라도 50만 달러를 초과합니다. 소규모 제네릭 의약품 공장에서는 그 비용을 상각하는 데 어려움을 겪고 있어, 뚜렷한 효율성이 기대됨에도 불구하고 장비 도입이 주춤하고 있습니다. 자금 조달의 장벽은 자본 예산이 여전히 빠듯한 인도, 인도네시아 및 아프리카 일부 지역에서 가장 심각합니다.
부문별 분석
2025년에도 바이오버든 검사 시장의 62.95%를 여전히 장비가 차지하고 있었지만, 소모품 매출은 가장 빠르게 확대되어 연평균 성장률(CAGR) 15.61%를 기록했습니다. 일회용 제조의 확대로 인해 새로운 배지, 필터, 신속 검사 키트가 모든 생산 주기에 도입되면서 수요가 증가하고 있습니다. 자동 식별 장치는 신속하고 정확한 측정 결과가 필요한 고처리량 세포 및 유전자 치료 파이프라인의 혜택을 받고 있습니다.
일회용 제품은 로트 간 잔류물을 제거하기 위해 현재 오염 방지 전략의 핵심이 되고 있습니다. 각 제조업체는 시약 공급 병목 현상을 보완하고 소모품의 안정적인 공급을 확보하기 위해 공급업체 감사를 강화하고 있습니다. 한편, 바이오버든 검사 시장 전체에서 분석 담당자의 작업 시간을 단축하고 데이터의 무결성을 높이는 것을 목표로 하는 대규모 플랜트에서는 AI가 탑재된 이미징 현미경과 PCR 모듈이 계속해서 설비 투자의 우선순위로 자리 잡고 있습니다.
2025년, 플레이트 계수법은 바이오버든 검사 시장의 39.22% 점유율을 유지했으나, 실시간 제조 수요를 배경으로 신속 검사 기법은 연평균 성장률(CAGR) 13.89%로 점유율을 확대되고 있습니다. 유세포 분석법 및 ATP 생물발광법은 며칠이 아닌 몇 시간 내에 결과를 도출하여 연속 생산 라인을 도입한 시설을 지원하고 있습니다.
현재 하이브리드 검사 체계에서는 규제 관행에 부합하는 기존의 배양 플레이트 검사와 신속성을 중시하는 형광법에 기반한 계수 검사가 융합되어 있습니다. AI 콜로니 카운터는 95%의 정확도를 유지하면서 판독 시간을 30초로 단축합니다. 이러한 효율화를 통해 분석 담당자의 병목 현상이 해소됨에 따라, 2031년까지의 바이오버든 검사 시장 규모 전망이 더욱 견고해지고 있습니다.
지역별 분석
2025년에는 FDA의 규제 조화와 고부가가치 생물제제 공장의 밀집된 네트워크가 첨단 검출 기술에 대한 투자를 촉진한 결과, 북미가 전 세계 매출의 38.18%를 차지하며 1위를 차지했습니다. 캐나다와 멕시코는 시설을 미국의 규정 준수 수준으로 업그레이드함으로써 지역 총 매출을 끌어올리고, 신속한 미생물 수 측정 솔루션을 제공하는 공급업체의 고객 기반을 확대되고 있습니다.
아시아태평양은 중국, 인도, 한국, 싱가포르의 주도 하에 연평균 성장률(CAGR) 14.2%로 성장할 것으로 전망됩니다. GMP 준수 강화와 바이오의약품 생산 능력 확대로 인해 자동 인큐베이터, PCR 키트, 일회용 배지 팩에 대한 대량 주문이 활발해지고 있습니다. 민관 협력에 의한 교육 이니셔티브는 미생물학자 인력 부족 해소를 목표로 하고 있지만, 동남아시아의 많은 지역에서는 여전히 수요가 인력 공급을 상회하고 있어 바이오버든 검사 시장에서 AI 지원형 검사 모듈의 전망을 더욱 높이고 있습니다.
유럽에서는 시설의 지속적인 모니터링을 의무화하는 엄격한 ‘Annex 1’의 시행으로 인해 시장 확대가 지속되고 있습니다. 독일, 영국, 프랑스에서는 인라인 센서 및 클라우드 데이터 관리 제품군에 대한 막대한 설비 투자 예산이 승인되었습니다. 한편, 중동 및 아프리카 및 남미에서는 제네릭 의약품 중심의 제조 거점들이 기본적인 배양판 계수 능력에 투자하고, 보다 신속한 분자 검사로 단계적으로 전환하고 있어 점진적인 성장이 예상됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the bioburden testing market size was valued at USD 1.58 billion in 2025 and estimated to grow from USD 1.78 billion in 2026 to reach USD 3.26 billion by 2031, at a CAGR of 12.85% during the forecast period (2026-2031).
This report is Segmented by Product (Instruments [PCR Systems and More] and Consumables [Culture Media & Reagents and More]), Enumeration Method (Membrane Filtration, Plate Count Method, and More), Application (Raw Material Testing, In-Process Testing, and More), End User (Medical Device Manufacturers and More) and Geography (North America and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Bioburden Testing Market Trends and Insights
High Frequency of Product Recalls Driven by Rapid-Release Supply Chains
Recurring recalls underscore how speed-focused logistics can let contaminants slip through routine checks. FDA notices in 2024 for sulfamethoxazole/trimethoprim tablets and atovaquone suspensions illustrated the costly fallout of microbial lapses.Manufacturers now view preventive testing as cheaper than multi-month shutdowns and brand damage. Generic drug makers with tight margins feel this pressure most, which lifts routine sampling volumes and positions the bioburden testing market as an essential quality gate.
Stringent cGMP & ISO 13485 Audits for Sterility Compliance
The 2024 US Quality Management System Regulation aligned domestic rules with ISO 13485, raising the bar for documentation and real-time monitoring. PIC/S Annex 1 revisions require continuous oversight rather than periodic checks. When Sanofi's Massachusetts plant logged 20% rejected runs, regulators highlighted historic contamination rates, prompting peers to adopt automated alerts and audit-ready data trails. Such mandates expand instrument sales and software subscriptions across the bioburden testing market.
High Upfront Cost of Automated Enumeration Platforms
Systems such as Rapid Micro Biosystems' Growth Direct exceed USD 500,000, excluding validation outlays. Small generics plants struggle to amortize that spend, slowing instrument uptake despite clear efficiency gains. Financing hurdles are most acute in India, Indonesia, and parts of Africa where capital budgets remain tight.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Single-Use Bioprocessing Equipment Boosting Test Volumes
- Rising Bioreactor Contamination Events in Cell & Gene Therapy Facilities
- Supply Bottlenecks for High-Purity Agar & Reagents
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consumables posted the quickest revenue expansion, advancing at a 15.61% CAGR even though instruments still captured 62.95% of the bioburden testing market in 2025. Growth in single-use manufacturing pushes fresh culture media, filters, and rapid test kits into every production cycle, lifting volume demand. Automated identification instruments benefit from high-throughput cell and gene therapy pipelines that require swift, accurate readouts.
Disposable items now anchor contamination-prevention strategies because they eliminate cross-batch residue. Manufacturers intensify supplier audits to secure uninterrupted consumables flow, offsetting reagent bottlenecks. Meanwhile, AI-enabled imaging microscopes and PCR modules remain capital priorities for large plants aiming to reduce analyst touch time and boost data integrity across the bioburden testing market.
Plate count assays retained 39.22% of bioburden testing market share in 2025, yet rapid techniques are climbing at 13.89% CAGR on the back of real-time manufacturing needs. Flow cytometry and ATP bioluminescence deliver answers in hours, not days, aiding facilities that have adopted continuous lines.
Hybrid testing regimes now merge legacy culture plates for regulatory familiarity with fluorescence-based counts for speed. AI colony counters cut read time to 30 seconds while holding 95% accuracy. These efficiencies slash analyst bottlenecks and reinforce the bioburden testing market size outlook through 2031.
Complete Report Scope:
- By Product
- Instruments
- Automated Microbial Identification Systems
- Polymerase Chain Reaction (PCR) Systems
- Microscopes
- Other Instruments
- Consumables
- Culture Media & Reagents
- Other Consumables
- Instruments
- By Enumeration Method
- Membrane Filtration
- Plate Count Method
- Most Probable Number (MPN)
- Rapid/Alternative Methods (flow-cytometry, ATP)
- By Application
- Raw-Material Testing
- In-process (Bioprocess) Testing
- Finished Medical-Device Testing
- Equipment-Cleaning Validation
- Environmental Monitoring Swabs & RODAC plates
- By End-User
- Pharmaceutical & Biopharmaceutical Manufacturers
- Medical-Device Manufacturers
- Contract Research & Manufacturing Organizations (CROs/CMOs)
- Academic & Research Laboratories
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with 38.18% of global revenues in 2025 as FDA rule harmonization and a dense network of high-value biologics plants favored advanced detection investments. Canada and Mexico strengthen regional totals by upgrading facilities to US compliance levels, broadening customer bases for rapid enumeration suppliers.
Asia-Pacific is forecast to grow at 14.2% CAGR, propelled by China, India, South Korea, and Singapore. Rising GMP adherence and greater biologics capacity spark bulk orders for automated incubators, PCR kits, and disposable media packs. Public-private training initiatives aim to close microbiologist gaps, yet demand still outpaces talent supply across much of Southeast Asia, magnifying prospects for AI-assisted testing modules within the bioburden testing market.
Europe sustains expansion through strict Annex 1 enforcement that compels continuous facility monitoring. Germany, the United Kingdom, and France approve sizeable capital budgets for inline sensors and cloud data-management suites. Meanwhile, Middle East, Africa, and South America register incremental gains as generic-driven manufacturing hubs invest in basic plate-count capacity and gradually transition toward quicker molecular assays.
- Beckton Dickinson
- Sartorius
- Merck KGaA (MilliporeSigma)
- Thermo Fisher Scientific
- bioMerieux
- Rapid Micro Biosystems
- Danahar
- Solventum
- Hardy Diagnostics
- Mesa Laboratories
- Synbiosis (SDI)
- Microbiologics
- Don Whitley Scientific
- Lonza Group
- Advanced Instruments
- Cherwell Laboratories
- STERIS
- Hygiena
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High Frequency Of Product Recalls Driven By Advent Of Rapid-Release Global Supply Chains
- 4.2.2 Stringent Cgmp & ISO 13485 Audits For Sterility Compliance
- 4.2.3 Shift Toward Single-Use Bioprocessing Equipment Boosting Test Volumes
- 4.2.4 Rising Bioreactor Contamination Events In Cell & Gene Therapy Facilities
- 4.2.5 Microbiome-Based Therapeutics Requiring Ultra-Low Detection Thresholds
- 4.2.6 Adoption Of Continuous Manufacturing Challenging Conventional Sampling Windows
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost Of Automated Enumeration Platforms
- 4.3.2 Shortage Of Trained Microbiologists In Emerging Markets
- 4.3.3 False-Negative Risk In Rapid Sterility Assays Delaying Regulatory Acceptance
- 4.3.4 Supply Bottlenecks For High-Purity Agar & Reagents
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Product
- 5.1.1 Instruments
- 5.1.1.1 Automated Microbial Identification Systems
- 5.1.1.2 Polymerase Chain Reaction (PCR) Systems
- 5.1.1.3 Microscopes
- 5.1.1.4 Other Instruments
- 5.1.2 Consumables
- 5.1.2.1 Culture Media & Reagents
- 5.1.2.2 Other Consumables
- 5.1.1 Instruments
- 5.2 By Enumeration Method
- 5.2.1 Membrane Filtration
- 5.2.2 Plate Count Method
- 5.2.3 Most Probable Number (MPN)
- 5.2.4 Rapid/Alternative Methods (flow-cytometry, ATP)
- 5.3 By Application
- 5.3.1 Raw-Material Testing
- 5.3.2 In-process (Bioprocess) Testing
- 5.3.3 Finished Medical-Device Testing
- 5.3.4 Equipment-Cleaning Validation
- 5.3.5 Environmental Monitoring Swabs & RODAC plates
- 5.4 By End-User
- 5.4.1 Pharmaceutical & Biopharmaceutical Manufacturers
- 5.4.2 Medical-Device Manufacturers
- 5.4.3 Contract Research & Manufacturing Organizations (CROs/CMOs)
- 5.4.4 Academic & Research Laboratories
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Becton, Dickinson and Company (BD)
- 6.3.2 Sartorious AG
- 6.3.3 Merck KGaA (MilliporeSigma)
- 6.3.4 Thermo Fisher Scientific
- 6.3.5 bioMerieux SA
- 6.3.6 Rapid Micro Biosystems
- 6.3.7 Danahar
- 6.3.8 Solventum
- 6.3.9 Hardy Diagnostics
- 6.3.10 Mesa Laboratories
- 6.3.11 Synbiosis (SDI)
- 6.3.12 Microbiologics
- 6.3.13 Don Whitley Scientific
- 6.3.14 Lonza Group
- 6.3.15 Advanced Instruments
- 6.3.16 Cherwell Laboratories
- 6.3.17 STERIS
- 6.3.18 Hygiena
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


