|
시장보고서
상품코드
2122897
자동차 및 운송용 커넥터 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive And Transportation Connector - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 자동차 및 운송용 커넥터 시장 규모는 150억 2,000만 달러로 추정되고 2025년 143억 5,000만 달러에서 확대해, 2031년에는 189억 1,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안 연평균 성장률(CAGR) 4.69%로 성장할 것으로 전망됩니다.

본 보고서는 제품 유형(와이어-투-보드 커넥터, 보드-투-보드 커넥터, 기타), 용도(안전 및 보안, 차체 배선·전력 분배, 기타), 차종(승용차, 소형 상용차, 기타), 추진력, 유통 채널, 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 자동차 및 운송용 커넥터 시장 동향과 인사이트
급속한 전동화 확대가 고전압 커넥터 수요를 견인
전기자동차는 동급 내연기관 차량에 비해 약 3배의 구리를 필요로 하며, 이에 따라 커넥터의 전류 용량 및 표면 거리 설계 요건도 비약적으로 높아지고 있습니다. TE Connectivity의 AMP+ 시리즈는 350A를 초과하는 충전 전류를 견딜 수 있는 터치 세이프 하우징과 최적화된 절연 채널을 채택하여, 이미 800V 아키텍처를 지원하고 있습니다. 전류 증가에 따라 초고속 충전 시 열적 한계를 확보하는 침지 냉각식 커넥터 어셈블리가 등장하고 있습니다. 절연 내력, 내진동성, 자동화 생산성을 균형 있게 갖춘 공급업체는 전 세계 EV 프로그램에서 우선 조달처로서의 입지를 확고히 하고 있습니다.
ADAS·인포테인먼트 통합이 고속 데이터 커넥터 수요를 견인
자율주행 프로토타입은 하루에 4TB 이상의 데이터를 생성하고 있으며, 1dB 이하의 삽입 손실로 20GHz 신호를 전송하면서도 높은 진동에 견딜 수 있는 커넥터 시스템이 요구되고 있습니다. Aptiv의 H-MTD 소형 동축 커넥터 제품군은 밀폐형 자동차 하우징 내에서 56Gbps 요구 사항을 충족하며, 기존 FAKRA 설계에 비해 설치 면적을 줄였습니다. 1000BASE-T1 등의 이더넷 표준 전환에 따라 와이어 하네스는 단일 트위스트 페어로 단순화되어, 고급차의 경량화 목표 달성을 뒷받침하고 있습니다. 커넥터의 신뢰할 수 있는 EMI 성능은 레벨 3 자율 주행을 뒷받침하는 카메라 기반 센서 융합의 정확도에 직접적인 영향을 미칩니다.
구리 가격 변동이 BOM 비용을 상승시키고
세계 구리 공급은 전동화에 따른 수요를 따라가지 못하고 있으며, 미국 지질조사국(USGS)은 광석 등급 저하가 채굴 비용을 상승시켜 2024년에는 톤당 평균 8,490달러라는 가격 변동의 원인이 되고 있다고 지적했습니다. 그 결과, 커넥터의 부품표(BOM) 재검토가 더욱 빈번하게 이루어지고 있으며, 전도성은 여전히 낮지만 엔지니어링 팀은 중요도가 낮은 전원 핀에 알루미늄 합금 채택을 검토하고 있습니다. 현재 재활용은 전 세계 구리 소비량의 32%를 차지하고 있지만, 자동차 등급의 청정도에 대한 제한으로 인해 그 보급은 여전히 제한적입니다.
부문별 분석
와이어-투-보드(WTB) 설계는 2025년 매출의 39.12%를 차지하며 계측 패널에서 변함없는 위상을 입증했지만, 자동차 및 운송용 커넥터 시장에서는 현재 2031년까지 연평균 성장률(CAGR) 9.17%를 나타낼 것으로 예측되는 고전압 어셈블리에 주요 연구 개발이 집중되고 있습니다. 대전류 부문은 800V에서 작동하는 실리콘 카바이드(SiC) 인버터의 보급으로 혜택을 보고 있으며, 여기에는 강화된 표면 간격과 액체 냉각 핀이 요구됩니다. 또한, 레이더와 카메라의 탑재 대수가 증가함에 따라 RF·동축 커넥터의 중요성도 다시 높아지고 있습니다. JAE 등공급업체는 전 세계 안전 기준을 충족하기 위해 200A CHAdeMO 플러그에 전자기 잠금 및 긴급 분리 기능을 통합하고 있습니다.
표준 ECU 패키징에서는 여전히 기판 간 메자닌 데크가 주류를 이루고 있지만, 구역별 하드웨어의 채택으로 핀 밀도는 1인치당 120핀을 넘는 수준으로 향상되었습니다. 하나의 헤더 내에 신호용과 50A용 블레이드를 결합한 하이브리드 하우징은 SKU 수를 줄이고 자동 픽 앤 플레이스 공정을 간소화합니다. 그 결과, 모듈 통합 업체들은 현재 커넥터를 단순한 범용 연결 지점이 아닌 기능적인 하위 시스템으로 취급하고 있으며, 자동차 및 운송용 커넥터 시장에서 프리미엄 가격을 유지하고 있습니다.
2025년 지출 중 차체 배선과 전력 분배가 37.74%를 차지했으나, 카메라, 레이더, LiDAR 센서의 보급이 가속화됨에 따라 ADAS 및 자율주행용 전자 기기는 연평균 성장률(CAGR) 11.74%를 기록할 전망입니다. 이러한 상승 추세로 인해 전문 공급업체에게 ADAS 연결성은 이익률 확대를 위한 가장 빠른 길이 되고 있습니다. 몰입형 디스플레이나 무선 업데이트에는 멀티 기가비트 백본이 필요하기 때문에 콕핏 엔터테인먼트 플랫폼도 그 뒤를 잇고 있습니다.
파워트레인 및 배터리 시스템용 자동차 및 운송용 커넥터 시장 규모는 전기차(EV) 판매 대수 증가에 따라 확대될 것으로 예측되며, 차폐형 고전압 인터페이스 분야에서 규모의 경제가 기대됩니다. 한편, 안전 보안 모듈은 단일 하우징 내에 중복 전원 핀을 통합함으로써 공간 낭비를 최소화하면서도 ISO 26262의 진단 요건을 충족하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 45.05%를 차지하며, 세계 최대의 자동차 조립 거점인 동시에 가장 빠르게 성장하는 전동 모빌리티 클러스터로서의 위상을 반영했습니다. 중국의 OEM 기업들은 고전압 및 배터리 관리용 커넥터에 대한 집중적인 수요를 창출하고 있는 반면, 일본과 한국은 전 세계 프리미엄 브랜드를 위해 정밀한 기판 간 연결용 및 동축 형태의 커넥터를 공급하고 있습니다. 2024년 인도네시아의 승용차 생산 대수 140만 대는 미국의 조달 규정에 따라 중국산 부품의 인증 요건이 엄격해지는 상황 속에서도 현지 커넥터 금형 개발을 촉진하는 2차 생산 거점으로서 동남아시아의 부상을 부각시켰습니다.
북미에서는 IP68을 초과하는 보호 등급을 갖춘 밀폐형 원형 전원 커넥터를 선호하는 고급 트럭에 대한 수요가 유지되고 있습니다. ‘인플레이션 억제법’에 따라 국내 배터리 공장에 인센티브가 제공되면서 현지에서의 고전압 단자 공급이 촉진되고 있습니다. 2024년 캐나다의 구리 생산량은 50만 8,250톤에 달하고, 가격 변동 위험을 헤지하는 지역 내 프레스 가공 사업의 원료 안정 공급을 뒷받침했습니다. 또한, 각 커넥터 제조업체들은 2027년 시행 예정인 미국산 부품 사용 규제(중국산 텔레매틱스 모듈 사용 금지)에 직면해 있으며, 이로 인해 듀얼 소스 인증 취득이 가속화되고 있습니다.
유럽에서는 첨단 전기차 생산과 수입 급증에 따른 비용 압박이 공존하고 있습니다. 독일은 2024년에 135만 대의 전기차를 생산했으나, 같은 해 EU 제조업체에서는 5만 3,669명의 일자리가 사라졌습니다. 유럽연합 집행위원회의 ‘전략적 대화’에서는 하네스 중량 감소를 목적으로 Horizon 기금을 상호 운용 가능한 10BASE-T1S 네트워크에 투입하고 있습니다. 한편, 중동 및 아프리카 프로젝트에서는 걸프 국가들의 스마트 시티 투자와 남아프리카공화국의 수출 계약을 활용하고 있습니다. 영국이 2027년부터 산업용 전기 요금을 25% 인하하겠다고 약속한 것은 커넥터 프레스 가공 분야의 경쟁력을 회복하기 위한 것입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the automotive and transportation connector market size in 2026 is estimated at USD 15.02 billion, growing from 2025 value of USD 14.35 billion with 2031 projections showing USD 18.91 billion, growing at 4.69% CAGR over 2026-2031.
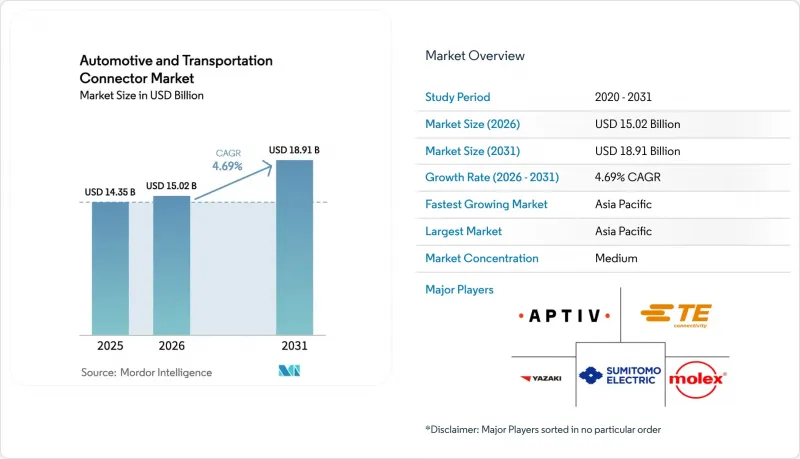
This report is Segmented by Product Type (Wire-To-Board Connectors, Board-To-Board Connectors, and More), Application (Safety and Security, Body Wiring and Power Distribution, and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Propulsion, Sales Channel, and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive And Transportation Connector Market Trends and Insights
Electrification Surge Spurring High-Voltage Connector Demand
Electric vehicles require nearly three times more copper than comparable combustion models, driving a parallel jump in connector amperage and creepage design discipline. TE Connectivity's AMP+ range already supports 800 V architectures, using touch-safe housings and optimized insulation paths that withstand charging currents above 350 A . Immersion-cooled connector assemblies are emerging as currents climb, ensuring thermal limits during ultra-fast charging sessions. Suppliers capable of balancing dielectric strength, vibration resistance, and automated manufacturability gain preferred-source status among global EV programs.
ADAS and Infotainment Integration Driving High-Speed Data Connectors
Autonomous prototypes generate over 4 TB of data per day, dictating connector systems that endure high vibration while transmitting 20 GHz signals at under-1 dB insertion loss. Aptiv's H-MTD miniature coax family meets 56 Gbps requirements within a sealed automotive housing, shrinking footprint versus legacy FAKRA designs. Ethernet shifts such as 1000BASE-T1 simplify wiring harnesses to a single twisted pair, supporting weight reduction targets on premium vehicles. Reliable connector EMI performance directly shapes camera-based sensor fusion accuracy that underpins level-3 autonomy.
Copper-Price Volatility Inflating BOM Costs
Global copper supply lags electrification demand, and the US Geological Survey notes declining ore grades lift extraction costs, contributing to price swings that averaged USD 8,490 per tonne in 2024. Connector bills of material are therefore indexed more frequently, and engineering teams test aluminum alloys for non-critical power pins even though conductivity remains lower. Recycling now covers 32% of worldwide copper consumption, but automotive-grade cleanliness limits still confine the practice .
Other drivers and restraints analyzed in the detailed report include:
- Shift to Zonal Architectures Boosting High-Density Board-Edge Connectors
- Safety-Critical Compliance Heightening Reliability Needs
- Local-Sourcing Mandates Limiting Procurement Flexibility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wire-to-board designs kept 39.12% of 2025 revenue, confirming their evergreen role in instrumentation panels, yet the automotive and transportation connector market now directs major R&D toward high-voltage assemblies that will grow 9.17% CAGR to 2031. The high-current category benefits from silicon-carbide inverters operating at 800 V, which demand reinforced creepage gaps and liquid-cooled pins. RF & coax connectors also gain renewed relevance as radar and camera counts increase. Suppliers such as JAE incorporate electromagnetic locks and emergency unmating in 200 A CHAdeMO plugs to satisfy global safety codes.
Standard ECU packaging still leans on board-to-board mezzanine decks, but zonal hardware elevates density beyond 120 pins per inch. Hybrid housings that mix signal and 50 A blades inside one header reduce SKU count and simplify automated pick-and-place. As a result, module integrators now treat the connector as a functional sub-system rather than a commodity fastening point, sustaining premium pricing inside the automotive and transportation connector market.
Body wiring and power distribution commanded 37.74% of 2025 spend, yet ADAS and autonomous electronics will log a 11.74% CAGR as camera, radar, and lidar sensor proliferation intensifies. That uptrend positions ADAS connectivity as the fastest pathway to margin expansion for specialized suppliers. Cockpit entertainment platforms follow closely because immersive displays and over-the-air upgrades need multi-gigabit backbones.
The automotive and transportation connector market size for powertrain and battery systems is projected to climb in tandem with EV unit growth, opening space for scale economies on shielded high-voltage interfaces. Meanwhile, safety-security modules integrate redundant power pins within a single housing, limiting space overhead while meeting ISO 26262 diagnostics requirements.
Complete Report Scope:
- By Product Type
- Wire-to-Board Connectors
- Board-to-Board Connectors
- Wire-to-Wire Connectors
- High-Voltage/EV Connectors
- RF & Coax Connectors
- Modular/Hybrid Connectors
- By Application
- Safety and Security
- Body Wiring and Power Distribution
- Cockpit, Connectivity and Entertainment (CCE)
- Powertrain and Battery Systems
- Advanced Driver-Assistance/Autonomous
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Two-Wheelers
- By Propulsion
- Internal-Combustion Engine Vehicles
- Hybrid Electric Vehicles
- Plug-in Hybrid Electric Vehicles
- Battery Electric Vehicles
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific contributed 45.05% of 2025 revenue, reflecting its position as both the world's largest vehicle assembly hub and the fastest-growing electric-mobility cluster. Chinese OEMs generate concentrated demand for high-voltage and battery-management connectors, while Japan and Korea supply precision board-to-board and coaxial formats for global premium nameplates. Indonesia's passenger-car output of 1.4 million units in 2024 underscored Southeast Asia's rise as a secondary production base that stimulates local connector tooling even as US sourcing rules tighten qualification paths for Chinese-made parts.
North America maintains premium-truck demand that favors sealed circular power connectors rated beyond IP68. The Inflation Reduction Act channels incentives into domestic battery plants, spurring localized high-voltage terminal supply. Canadian copper output of 508,250 tonnes in 2024 shores up raw-material availability for regional stamping operations that hedge price shocks. Connector makers also confront upcoming U.S. content rules slated for 2027 that bar Chinese telematics modules, accelerating dual-source qualifications.
Europe combines advanced EV production with cost pressure from surging imports. Germany built 1.35 million electric cars in 2024, yet EU manufacturers lost 53,669 jobs in the same year. The European Commission's Strategic Dialogue is funneling Horizon funds into interoperable 10BASE-T1S networking to cut harness weight, while Middle East and African projects tap Gulf smart-city investments and South-African export contracts. The UK's pledge to lower industrial power tariffs by 25% from 2027 aims to restore connector stamping competitiveness.
- TE Connectivity
- Yazaki Corporation
- Aptiv PLC
- Amphenol Corporation
- Molex (Koch Industries)
- Sumitomo Electric Industries
- Lear Corporation
- Leoni AG
- Korea Electric Terminal (KET)
- Rosenberger Hochfrequenztechnik
- Luxshare Precision Industry
- JST Mfg.
- HARTING Technology Group
- Furukawa Electric
- ITT Cannon
- Hirose Electric
- Japan Aviation Electronics (JAE)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Electrification Surge Spurring High-Voltage Connector Demand
- 4.2.2 ADAS and Infotainment Integration Driving High-Speed Data Connectors
- 4.2.3 Shift to Zonal E/E Architectures Boosting High-Density Board-Edge Connectors
- 4.2.4 Safety-Critical Compliance (ISO 26262, UN R155) Heightening Reliability Needs
- 4.2.5 Migration to Gigabit Ethernet and FAKRA-Mini Coax Interfaces
- 4.2.6 Emerging 48 V Sub-Systems in ICE Vehicles
- 4.3 Market Restraints
- 4.3.1 Copper-Price Volatility Inflating BOM Costs
- 4.3.2 Local-Sourcing Mandates Limiting Low-Cost Procurement
- 4.3.3 Recalls from Connector Seal or Crimp Failures
- 4.3.4 Rising In-Vehicle Wireless Sensor Nodes Reducing Hard-Wired Ports
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Wire-to-Board Connectors
- 5.1.2 Board-to-Board Connectors
- 5.1.3 Wire-to-Wire Connectors
- 5.1.4 High-Voltage/EV Connectors
- 5.1.5 RF & Coax Connectors
- 5.1.6 Modular/Hybrid Connectors
- 5.2 By Application
- 5.2.1 Safety and Security
- 5.2.2 Body Wiring and Power Distribution
- 5.2.3 Cockpit, Connectivity and Entertainment (CCE)
- 5.2.4 Powertrain and Battery Systems
- 5.2.5 Advanced Driver-Assistance/Autonomous
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Medium and Heavy Commercial Vehicles
- 5.3.4 Two-Wheelers
- 5.4 By Propulsion
- 5.4.1 Internal-Combustion Engine Vehicles
- 5.4.2 Hybrid Electric Vehicles
- 5.4.3 Plug-in Hybrid Electric Vehicles
- 5.4.4 Battery Electric Vehicles
- 5.5 By Sales Channel
- 5.5.1 OEM
- 5.5.2 Aftermarket
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Egypt
- 5.6.5.4 Turkey
- 5.6.5.5 South Africa
- 5.6.5.6 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 TE Connectivity
- 6.4.2 Yazaki Corporation
- 6.4.3 Aptiv PLC
- 6.4.4 Amphenol Corporation
- 6.4.5 Molex (Koch Industries)
- 6.4.6 Sumitomo Electric Industries
- 6.4.7 Lear Corporation
- 6.4.8 Leoni AG
- 6.4.9 Korea Electric Terminal (KET)
- 6.4.10 Rosenberger Hochfrequenztechnik
- 6.4.11 Luxshare Precision Industry
- 6.4.12 JST Mfg.
- 6.4.13 HARTING Technology Group
- 6.4.14 Furukawa Electric
- 6.4.15 ITT Cannon
- 6.4.16 Hirose Electric
- 6.4.17 Japan Aviation Electronics (JAE)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment