

|
시장보고서
상품코드
2122927
플렉서블 파이프 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Flexible Pipe - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
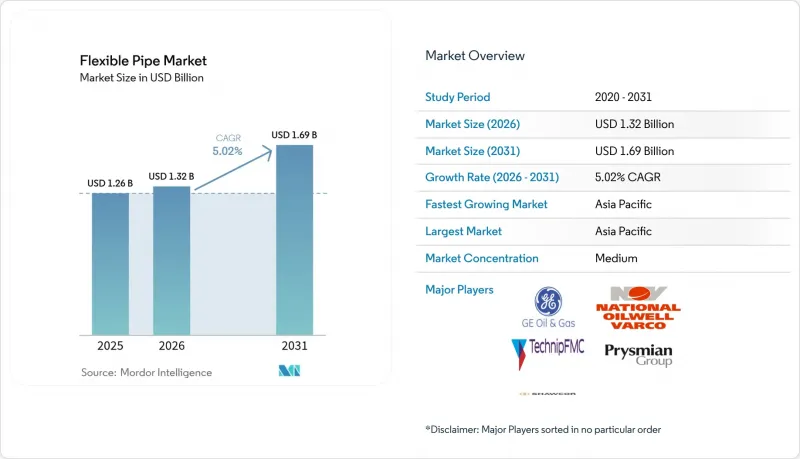
에 의하면, 플렉서블 파이프 시장 규모는 2025년에 12억 6,000만 달러로 평가되었습니다. 2026년 13억 2,000만 달러에서 2031년까지 16억 9,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.02%를 나타낼 전망입니다.

본 보고서는 재료 유형별(고밀도 폴리에틸렌(HDPE), 폴리아미드(PA), 기타), 파이프 구조 유형별(비접착식 플렉서블 파이프, 접착식 플렉서블 파이프, 보강 열가소성 수지 파이프(RTP)), 기능적 용도별(플로우 라인, 라이저,점퍼·타이인, 수출·적재용 호스), 설치 환경별(해상, 육상), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 플렉서블 파이프 시장 동향 및 인사이트
심해·초심해 개발 확대
복잡한 해저 지형에서 강성 강철 시스템의 경제성이 저하되는 가운데, 각 사업자들은 수심 1,500m를 초과하는 프로젝트를 승인하고 있습니다. 셰브론(Chevron)사의 앵커(Anchor) 유전에서는 20ksi의 해저용 하드웨어가 도입되어 플렉서블 파이프 시장에서 새로운 성능 기준을 수립했습니다. 브라질의 프레스솔트층에서는 수심 2,900m 깊이에서 CO2에 의한 부식 응력이 발생하기 때문에 검증된 복합재료 기술을 보유한 공급업체가 유리한 입지를 점하고 있습니다. TechnipFMC의 iEPCI와 같은 시스템 수준의 계약 모델은 일정을 최대 20% 단축하여 통합형 연성 솔루션에 대한 수요를 촉진하고 있습니다.
부식된 강철 파이프라인을 복합재료 파이프라인으로 교체
해상 부식 방지 대책에 드는 연간 비용은 25억 달러에 달하며, 음극 방식을 피할 수 있는 복합재 개조의 경제성이 높아지고 있습니다. 사이펨(Saipem)의 플라스틱 내장 파이프라인 기술은 1,000바의 내압 성능을 유지하면서 비용을 40% 절감합니다. 북해의 사업자들은 1990년 이전으로 거슬러 올라가는 총 길이 1만 km에 달하는 구형 파이프라인 네트워크에 직면해 있습니다. 유연성이 높은 파이프 시스템은 중량물 운반 설비 없이도 기존 경로에 통합될 수 있어, 개보수에 따른 가동 중단 시간을 단축합니다. 베이커 휴즈의 비금속 제품에 내장된 센서는 통합 분석 데이터를 제공하여, 많은 노력이 필요한 정기 점검을 대체합니다.
원유 가격 변동에 따른 설비 투자 억제
배럴당 70-90달러 범위의 가격 변동으로 인해 최종 투자 결정이 지연되고 있습니다. 이는 이사회가 해양 프로젝트 승인에 앞서 18-24개월간의 가격 안정성을 요구하게 되었기 때문입니다. 금리 상승은 승인 장벽을 더욱 높여, 승인 지연을 초래하고 있습니다. 성숙기에 접어든 북해와 멕시코만 유전은 특히 영향을 받기 쉬운데, 이는 연성 파이프가 프로젝트 총 CAPEX의 최대 20%를 차지하며, 경제성이 가격 변동에 민감하기 때문입니다.
부문별 분석
HDPE(고밀도 폴리에틸렌) 플렉서블 파이프 시장 규모는 2025년에 4억 4,000만 달러에 달하여 매출의 35.12%를 차지했습니다. 사업자들은 비용 효율이 높은 압출 성형, 화학적 불활성, 용접이 필요 없는 접합부 등의 측면에서 HDPE를 높이 평가했습니다. 그럼에도 불구하고, ‘기타 소재’-주로 탄소섬유 및 첨단 폴리머-는 연평균 성장률(CAGR) 8.03%를 기록하며, 부유식 생산 시스템이 탑사이드의 적재량을 줄이기 위해 질량 감소를 추구하는 가운데 기존 소재를 능가하고 있습니다. 시드니 대학의 예측에 따르면, 2030년까지 CFRP 폐기물량은 50만 톤에 달할 것으로 예상되며, 이로 인해 순환 경제에 대한 압박이 커지면서 연구 개발이 재활용 가능한 수지로 방향을 전환할 가능성이 있습니다.
소재 혁신 기업들은 피로 수명과 내열 범위를 향상시킴으로써 플렉서블 파이프 시장 점유율 확대를 추진하고 있습니다. 고성능 PA 및 PVDF 층은 130°C에서의 사용을 가능하게 하여, 고온 고압(HTHP) 유정에 플렉서블 파이프의 도입을 확대되고 있습니다. 열가소성 복합 파이프(TCP)는 탄소섬유로 만든 인장 케이스와 PA12 라이너를 결합하여 부식이 전혀 없고 마찰이 적은 유동 특성을 실현하고 있습니다. 심해 활동이 확대됨에 따라 복합재료의 채택으로 인해 2031년까지 ‘기타 재료’가 유연 파이프 시장에서 차지하는 비중이 3분의 1에 달할 것으로 예측됩니다.
2025년에는 비접착 구조가 전 세계 매출의 45.08%를 차지하며, 홉 하중과 축방향 하중을 분리하는 다층 아머의 이점을 활용했습니다. 뛰어난 복구성이 다이내믹 라이저 용도에서의 채택을 뒷받침하고 있습니다. 한편, 금속 카카스를 일절 사용하지 않는 ‘보강 열가소성 파이프(RTP)’는 사업자들이 부식 없는 성능과 데크 하중 경량화를 중시함에 따라 연평균 성장률(CAGR) 7.12%로 확대되고 있습니다. FlexSteel의 스풀링이 가능한 RTP 솔루션은 양극 처리나 코팅 작업을 불필요하게 하여, 기존 설비와의 연결 공사 시 운영 비용(OPEX)을 절감합니다.
플렉서블 파이프 시장에서 구조 선택은 피로, 압력, 화학 물질 노출 상황에 따라 결정됩니다. 본디드 파이프는 틈새 시장인 초고압 유동 라인에 사용되지만, 현장 수리 옵션이 제한적이고 비용이 높다는 단점이 있습니다. 아라미드 섬유 및 유리 섬유 권취 기술의 혁신과 피로 축적을 추적하는 디지털 트윈을 결합함으로써, RTP는 과거 강도 제한으로 인해 진입이 막혔던 라이저 용도로도 진출할 수 있게 될 것으로 보입니다.
지역별 분석
아시아태평양은 남중국해 심해 광구와 호주의 LNG 보충 프로그램을 배경으로 2025년 매출의 37.78%를 차지했습니다. 이 지역의 플렉서블 파이프 시장 규모는 연평균 성장률(CAGR) 8.01%로 확대될 것으로 예측되며, 다른 모든 지역을 능가하는 속도로 성장할 전망입니다. 로컬 콘텐츠를 장려하는 정부의 정책은 지역적 제조 허브 구축을 뒷받침하고 있습니다. 예를 들어, 테크닙 FMC의 동남아시아 공장은 중국 및 인도의 사업자들에게 릴 설치 리드타임을 단축시켜 주고 있습니다. 일본과 한국에서의 해상 풍력 발전 도입 확대는 해저 전력 케이블 및 다이내믹 앰빌리컬에 대한 파급 수요를 창출하며, 복합재료 기술의 상호 교류를 더욱 촉진하고 있습니다.
북미는 두 번째로 큰 지역으로 그 뒤를 잇고 있으며, 20ksi의 연질 점퍼가 필요한 멕시코만 초심해 개발 프로젝트가 이를 뒷받침하고 있습니다. 아나달코 분지의 가스 집합 파이프라인과 퍼미안 분지의 수소 실증 프로젝트가 육상 스풀형 파이프의 채택을 주도하고 있습니다. 그러나 멕시코만에서의 설비 갱신 물결은 발견률의 정체로 인해 상쇄되고 있어, 해당 지역의 연평균 성장률(CAGR)은 아시아태평양에 뒤처지고 있습니다.
유럽에서는 북해의 수명 연장 프로젝트와 노르웨이 및 영국 전역에서 막 시작된 수소 기반 시범 사업을 바탕으로 균형 잡힌 성장이 나타나고 있습니다. 엄격한 폐기 조치에 관한 법규로 인해 노후화된 강재의 철거가 가속화되고 있으며, 타이백 방식에서 연질 라인으로의 교체에 활용되는 개조 기회가 생겨나고 있습니다. 그러나 재활용 의무로 인해 공급업체는 폴리머 회수를 위한 폐쇄형 루프 모델을 제안해야 하며, 이로 인해 총 설치 비용이 상승할 가능성이 있습니다.
중동 및 아프리카에서는 카타르 에너지의 ‘노스 필드 압축 프로그램’과 서아프리카의 FPSO 프로젝트가 내식성 복합 소재를 요구함에 따라, 이 소재의 도입이 급속히 진행되고 있습니다. 카타르에서 사이펨(Saipem)사가 40억 달러 규모의 EPC 계약을 수주한 것은 이 지역에서 고사양 플로우라인 및 광섬유 내장 앰빌리컬에 대한 수요가 높음을 뒷받침합니다. 튀르키예의 사카리아 2단계 프로젝트에서는 정격 수심 2,200m의 파이프 158km가 요구되고 있어, 흑해 분지의 성숙화를 시사하고 있습니다. 브라질의 프레스솔트층과 가이아나의 스타브로크 블록을 핵심으로 하는 남미는 여전히 중심적인 축이며, 전 세계 SURF 수주 잔고의 대부분을 차지하고 있어, 각 제조업체들이 리우 근교에 스풀 베이스를 공동으로 설치하기로 한 결정을 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the flexible pipe market size was valued at USD 1.26 billion in 2025 and estimated to grow from USD 1.32 billion in 2026 to reach USD 1.69 billion by 2031, at a CAGR of 5.02% during the forecast period (2026-2031).
This report is Segmented by Material Type (High-Density Polyethylene, Polyamide, and More), Pipe Structure Type (Unbonded Flexible Pipe, Bonded Flexible Pipe, Reinforced Thermoplastic Pipe), Functional Application (Flowlines, Risers, Jumpers and Tie-Ins, Export/Loading Hoses), Installation Environment (Offshore, Onshore), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Flexible Pipe Market Trends and Insights
Growing Deep- and Ultra-Deepwater Developments
Operators are sanctioning projects beyond 1,500 m as rigid steel systems become uneconomic in complex seabed topography. Chevron's Anchor field inaugurated 20 ksi subsea hardware that sets a new performance bar for the flexible pipe market. Brazil's pre-salt reservoirs impose CO2-driven corrosion stresses at 2,900 m depth, favoring suppliers with proven composite technology. System-level contracting models such as TechnipFMC's iEPCI compress schedules by up to 20%, reinforcing demand for integrated flexible solutions.
Replacement of Corroded Steel Lines with Composites
Annual offshore corrosion expenses reach USD 2.5 billion, elevating the economics of composite retrofits that sidestep cathodic protection. Saipem's plastic-lined pipeline technology trims costs by 40% while sustaining 1,000 bar ratings. North Sea operators confront a 10,000 km legacy grid dating back pre-1990; flexible pipe systems slot into existing corridors without heavy-lift spreads, cutting retrofit downtime. Embedded sensors inside Baker Hughes' non-metallic products feed integrity analytics that replace labor-intensive inspection rounds.
Crude-Oil Price Volatility Curbs CAPEX
Price swings in the USD 70-90 per-barrel band delay final investment decisions as boards now demand 18-24 months' price stability before greenlighting offshore projects. Higher interest rates lift hurdle thresholds, further deferring sanctioning. Mature North Sea and Gulf of Mexico fields are particularly vulnerable because flexible pipes constitute up to 20% of total project CAPEX, rendering economics price sensitive.
Other drivers and restraints analyzed in the detailed report include:
- SURF Megaproject Pipeline in Brazil and Guyana
- Embedded Fibre-Optic Health Monitoring
- Higher Upfront Cost Versus Rigid Steel
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Flexible pipe market size for HDPE reached USD 0.44 billion in 2025, translating into 35.12% revenue dominance. Operators value HDPE for cost-efficient extrusion, chemical inertia, and weld-free joints. Still, Other Materials-chiefly carbon-fiber and advanced polymers-record an 8.03% CAGR, outstripping incumbents as floating production systems chase mass savings to ease topside loading. University of Sydney forecasts CFRP waste streams hitting 500,000 t by 2030, intensifying circular-economy pressures that could redirect R&D toward recyclable resins.
Material innovators push flexible pipe market share gains by enhancing fatigue life and temperature windows. Advanced PA and PVDF layers deliver 130 °C service, expanding flexible deployment into high-HTHP wells. Thermoplastic composite pipes (TCP) marry carbon-fiber tensile casing with a PA12 liner to achieve zero corrosion and low-friction flow profiles. As deepwater activity scales, composite uptake is expected to raise Other Materials' contribution to one-third of the flexible pipe market by 2031.
Unbonded architectures accounted for 45.08% of global revenue in 2025, capitalizing on multilayered armor that decouples hoop and axial loads. Their repairability underpins preference in dynamic riser applications. Yet Reinforced Thermoplastic Pipes, devoid of metallic carcasses, expand 7.12% CAGR as operators target corrosion-free performance and lighter deck loads. FlexSteel's spoolable RTP solutions eliminate anodes and coating campaigns, lowering OPEX in brownfield tie-ins.
Structural choice in the flexible pipe market hinges on fatigue, pressure, and chemical exposure profiles. Bonded pipes serve niche ultra-high-pressure flowlines but are handicapped by limited field repair options and higher cost. Innovations in aramid and glass-fiber winding, coupled with digital twins tracking fatigue accumulation, will allow RTP to penetrate riser duty where strength limits once blocked entry.
Complete Report Scope:
- By Material Type
- High-Density Polyethylene (HDPE)
- Polyamide (PA)
- Polyvinylidene Fluoride (PVDF)
- Others Material Type
- By Pipe Structure Type
- Unbonded Flexible Pipe
- Bonded Flexible Pipe
- Reinforced Thermoplastic Pipe (RTP)
- By Functional Application
- Flowlines
- Risers
- Jumpers and Tie-ins
- Export / Loading Hoses
- By Installation Environment
- Offshore
- Shallow Water (Less than 500 m)
- Deepwater (500-1500 m)
- Ultra-deepwater (More than 1500 m)
- Onshore
- Offshore
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific retained 37.78% of 2025 revenue on the back of South China Sea deepwater blocks and Australian LNG backfill programs. The region's flexible pipe market size is forecast to rise at an 8.01% CAGR, outpacing all others. Government policy favoring local content spurs construction of regional manufacturing hubs, such as TechnipFMC's plant in Southeast Asia that shortens reel-lay lead times for Chinese and Indian operators. Growing offshore wind deployment in Japan and Korea creates spill-over demand for subsea power cables and dynamic umbilicals, further nurturing composite capability cross-fertilization.
North America follows as the second-largest region, underpinned by Gulf of Mexico ultra-deepwater sanctions that require 20 ksi flexible jumpers. Anadarko basin gathering lines and Permian hydrogen demonstration projects drive onshore spoolable adoption. Yet regional CAGR lags Asia-Pacific because the replacement wave in the Gulf is offset by plateauing discovery rates.
Europe shows balanced growth built on North Sea life-extension projects and nascent hydrogen backbone pilots across Norway and the United Kingdom. Strict decommissioning legislation accelerates removal of ageing steel, offering retrofit openings for flexible line substitution in tie-back schemes. Recycling mandates, however, require suppliers to propose closed-loop models for polymer recovery, potentially elevating total installed cost.
Middle East and Africa register rapid adoption as QatarEnergy's North Field Compression Program and West Africa's FPSO campaigns solicit corrosion-immune composites. Saipem's USD 4 billion EPC award in Qatar confirms regional appetite for high-specification flowlines and optic-fiber-infused umbilicals. Turkey's Sakarya Phase 2 calls for 158 km of 2,200 m-rated pipe, signalling Black Sea basin maturation. South America, anchored by Brazil's pre-salt and Guyana's Stabroek block, remains a central pillar, accounting for the bulk of global SURF backlogs and reinforcing manufacturers' decision to co-locate spool-bases near Rio.
- TechnipFMC plc
- National Oilwell Varco (NOV)
- Saipem S.p.A.
- Prysmian Group
- Shawcor Ltd
- Strohm (formerly Airborne Oil & Gas)
- Magma Global Ltd
- SoluForce BV
- ContiTech AG
- Chevron Phillips Chemical Co.
- FlexSteel Pipeline Technologies Inc.
- GE Oil & Gas (Baker Hughes)
- Aker Solutions ASA
- Wellstream Processing (NOV)
- Subsea 7 S.A.
- Oceaneering International
- Hunan Great Steel Pipe Co.
- JDR Cable Systems Ltd
- Polyflow LLC
- Cosmoplast Industrial Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing deep- and ultra-deepwater developments
- 4.2.2 Replacement of corroded steel lines with composites
- 4.2.3 SURF megaproject pipeline in Brazil and Guyana
- 4.2.4 Carbon-fibre armoured pipes lighten FPSOs
- 4.2.5 Embedded fibre-optic health monitoring
- 4.2.6 Hydrogen and CO2 transport demand for flexibles
- 4.3 Market Restraints
- 4.3.1 Crude-oil price volatility curbs CAPEX
- 4.3.2 Higher upfront cost versus rigid steel
- 4.3.3 Polymer-pipe end-of-life recycling gaps
- 4.3.4 Tight capacity for 20 k-psi rated pipes
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 High-Density Polyethylene (HDPE)
- 5.1.2 Polyamide (PA)
- 5.1.3 Polyvinylidene Fluoride (PVDF)
- 5.1.4 Others Material Type
- 5.2 By Pipe Structure Type
- 5.2.1 Unbonded Flexible Pipe
- 5.2.2 Bonded Flexible Pipe
- 5.2.3 Reinforced Thermoplastic Pipe (RTP)
- 5.3 By Functional Application
- 5.3.1 Flowlines
- 5.3.2 Risers
- 5.3.3 Jumpers and Tie-ins
- 5.3.4 Export / Loading Hoses
- 5.4 By Installation Environment
- 5.4.1 Offshore
- 5.4.1.1 Shallow Water (Less than 500 m)
- 5.4.1.2 Deepwater (500-1500 m)
- 5.4.1.3 Ultra-deepwater (More than 1500 m)
- 5.4.2 Onshore
- 5.4.1 Offshore
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia and New Zealand
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 United Arab Emirates
- 5.5.4.1.2 Saudi Arabia
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Nigeria
- 5.5.4.2.3 Egypt
- 5.5.4.2.4 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 TechnipFMC plc
- 6.4.2 National Oilwell Varco (NOV)
- 6.4.3 Saipem S.p.A.
- 6.4.4 Prysmian Group
- 6.4.5 Shawcor Ltd
- 6.4.6 Strohm (formerly Airborne Oil & Gas)
- 6.4.7 Magma Global Ltd
- 6.4.8 SoluForce BV
- 6.4.9 ContiTech AG
- 6.4.10 Chevron Phillips Chemical Co.
- 6.4.11 FlexSteel Pipeline Technologies Inc.
- 6.4.12 GE Oil & Gas (Baker Hughes)
- 6.4.13 Aker Solutions ASA
- 6.4.14 Wellstream Processing (NOV)
- 6.4.15 Subsea 7 S.A.
- 6.4.16 Oceaneering International
- 6.4.17 Hunan Great Steel Pipe Co.
- 6.4.18 JDR Cable Systems Ltd
- 6.4.19 Polyflow LLC
- 6.4.20 Cosmoplast Industrial Co.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


