|
시장보고서
상품코드
2122932
수소 가스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Hydrogen Gas - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 수소 가스 시장 규모는 2025년에 1억 1,391만 톤으로 평가되었습니다. 2026년 1억 1,807만 톤에서 2031년까지 1억 4,125만 톤에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 3.65%를 나타낼 전망입니다.

본 보고서는 유통(파이프라인, 고압 튜브 트레일러, 실린더), 용도(암모니아, 메탄올, 정제, 직접환원철(DRI), 연료전지차(FCV), 기타), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 규모와 전망은 수량(톤) 단위로 표시되어 있습니다.
세계의 수소 가스 시장 동향 및 인사이트
정유시설의 탈황 규제
국제해사기구(IMO)의 연료 규제와 미국 Tier 3 휘발유 기준에 따라, 황 함량이 1단계 감소할 때마다 수소 처리 설비용 수소 수요가 5-8% 증가하고 있습니다. 그 결과, 걸프 코스트, 로테르담, 싱가포르의 정유시설에서는 전용 파이프라인에 연결된 부지 내 증기 메탄 개질 설비를 확대하고, 수년에 걸친 상업 거래 계약을 체결하고 있습니다. 여전히 튜브 트레일러로 수소를 운송받아 구매하는 신흥 시장의 정유시설들은 납품 기준 1kg당 0.50-0.80달러 더 높은 가격을 지불하고 있습니다. ISO 14001 보고 요건에 따라 수소의 탄소 강도 공개가 의무화됨에 따라, 현물 구매는 배출량이 적은 공급원으로 이동하고 있습니다. 탄소 가격 책정이 이루어지고 있는 지역에서는 전해조 개조가 카보네이트 패리티에 가까워지고 있음에도 불구하고, 2026년까지의 규정 준수 기한으로 인해 기준선 수요는 유지되고 있습니다.
그린 수소에 대한 정부의 장려책
미국의 ‘인플레이션 억제법’ 제45V조에서는 CO2 환산 기준 0.45kg 이하의 수소에 대해 kg당 최대 3달러의 보조금이 제공되며, 재생에너지와 연계된 전해조 도입이 촉진되고 있습니다. 유럽의 수소 은행(Hydrogen Bank)은 그레이 수소와의 비용 격차를 줄이기 위해 2024년에 7억 2,000만 유로 규모의 차액결제계약(CFD)을 체결했으나, 경매를 통해 거래된 양은 2030년 연간 수입 목표인 1,000만 톤의 극히 일부에 그치고 있습니다. 일본, 중국, 한국은 구매 보조금이나 고정가격 임베디드 제도를 연장하고 있으며, 이 조치들이 수 메가와트 규모의 스택 발주를 뒷받침하고 있습니다. 제조업체의 공개 정보에 따르면, 이로 인해 중국의 알칼리성 전해조 가격은 1kW당 200달러 미만으로 떨어졌습니다. 이러한 다층적인 인센티브 덕분에 수소 가스 시장은 모빌리티, 철강, 비료 각 부문에서 비용 경쟁력 확보에 한 걸음 더 가까워지고 있습니다.
높은 비용의 저장·수송 물류
350bar에서 압축 저장할 경우, 에너지 밀도는 디젤의 10분의 1에 불과하기 때문에 300km를 초과하는 노선에서는 튜브 트레일러를 이용한 운송 비용으로 1kg당 2달러 이상의 할증료가 발생합니다. 액화 과정에서는 수소의 발열량의 25-35%가 소모되며, 1kg당 일일 처리량에 약 1,000달러가 드는 극저온 탱크가 필요합니다. 액체 유기 운반체는 보일오프 손실을 줄여주지만, 왕복 효율이 40% 저하되고 고가의 탈수소 촉매가 필요합니다. 신규 수소 파이프라인은 부지 임베디드비를 제외하더라도 1km당 300만-500만 달러의 비용이 소요되기 때문에 남미와 사하라 이남 아프리카에서의 도입이 제한되고 있습니다. 이러한 지역에서는 그린필드 프로젝트에서 생산 및 유통에 대한 설비 투자를 통합해야 합니다. 이러한 비용이 수소 가스 산업의 단기적인 경제성에 큰 부담이 되고 있습니다.
부문별 분석
파이프라인 네트워크는 2025년 수소 가스 시장 규모의 58.42%를 공급했으며, 정유시설 및 암모니아 플랜트가 중단 없는 공급을 필요로 하고 있기 때문에 예측 기간(2026-2031년) 동안 연평균 성장률(CAGR) 4.12%로 확대될 것으로 전망됩니다. 지선이 없는 하루 50-500kg을 소비하는 산업용 사용자에게는 튜브 트레일러가 여전히 필수적이지만, 실험실이나 통신용 백업 시스템에서는 카트리지 형태로의 전환에 따라 실린더 팩의 사용이 감소하고 있습니다. 신흥 수출 파이프라인이 향후 성장을 뒷받침할 것입니다. 사우디아라비아 아카바로 이어지는 총 길이 1,500km의 NEOM 파이프라인은 그린 암모니아 수출을 담당할 예정이며, 유럽에서는 1만 1,600km의 가스 수송 파이프라인을 전용할 계획이 있어, 이를 통해 신규 건설에 비해 건설 비용을 60% 절감할 수 있습니다. 중동 및 아프리카에서는 파이프라인 증설이 주도되고 있으며, 이는 2030년까지 1kg당 1.50-2달러의 납품 비용을 목표로 하는 기가와트급 전해 설비를 뒷받침하고 있습니다.
수요가 분산된 지역에서는 튜브 트레일러의 경제성이 향상됩니다. 1,000kg을 적재하는 300바(bar) 설비라면 200km 반경 내의 6개 고객에게 서비스를 제공할 수 있으며, 정교한 경로 최적화를 통해 공회전 거리를 20-30% 절감할 수 있습니다. 실린더 팩은 계절적 요인이 있는 플로트 유리 공장이나 특수 용접 공장에 여전히 매력적이지만, ISO 11114에 따른 5년마다 실시되는 정수압 검사 때문에 수명 주기 비용이 증가하고 있습니다. 따라서 수소 가스 시장의 유통 포트폴리오는 지역적 수요가 집중되어 새로운 강관 파이프라인 건설이 정당화될 때까지 대용량 파이프라인과 유연한 육상 물류의 균형을 맞추고 있습니다.
지역별 분석
아시아태평양은 중국의 1,104개 수소 충전소, 일본의 암모니아 수입 계획, 한국의 2040년까지 6.2Mt 소비 목표에 힘입어 2025년 수소 가스 시장의 34.23%를 차지했습니다. 중국에서는 10MW 이상의 전해조에 대한 성(省) 차원의 보조금 덕분에 알칼리형 스택의 비용이 1kW당 200달러 이하로 억제되어 유럽 평균의 절반 수준에 이르렀으며, 중국 공급업체들은 수출을 위한 체제를 갖추고 있습니다. 인도의 ‘국가 수소 미션’은 2030년까지 5Mt을 생산하기 위해 1,970억 루피(24억 달러)를 투자하며, 1kWh당 2루피 이하의 태양광 발전 요금이 적용되는 구자라트주와 오디샤주의 회랑 지역에 중점을 두고 있습니다. 아세안(ASEAN)에서는 태국, 싱가포르, 말레이시아에서 탄소 가격의 명확화를 기다리는 동안, 송전망에 수소를 혼합하거나 석탄 화력 발전소에서 암모니아 혼소를 시범적으로 실시했습니다.
중동 및 아프리카는 예측 기간(2026-2031년) 동안 4.12%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 사우디아라비아, 아랍에미리트, 오만, 이집트의 프로젝트에서는 가동률 30-40%의 태양광 발전과 해수 담수화를 결합하여, 2030년까지 1kg당 1.50-2달러의 원가 달성이 예상됩니다. NEOM 프로젝트에서는 2026년 하반기부터 하루 650톤의 수소를 암모니아 형태로 출하할 예정이며, 한편,남아프리카공화국의 Boegoebaai 프로젝트는 1kg당 0.30-0.50달러의 해수 담수화 비용이 추가됨에도 불구하고, 2028년부터 40만 톤의 그린 암모니아 생산을 목표로 하고 있습니다.
북미에서는 미국 에너지부가 7개 지역 허브에 자금을 지원하고 있으며, 각 허브는 정제, 비료, 운송용으로 연간 5만-10만 톤을 생산합니다. 캐나다는 앨버타주에서 탄소 포집이 수반되는 블루 수소를, 퀘벡주에서는 수력발전을 이용한 그린 수소 개발을 추진하고 있으며, EU의 탄소국경조정세가 확정되는 대로 EU로의 수출을 기대하고 있습니다. 유럽에서는 기존의 가스 송배전망을 전용하고 있습니다. 독일은 특정 부문에서 20%의 혼합 사용을 허용하고 있으며, 영국은 수소 100% 마을을 계획하고 있고, 프랑스는 아르셀로미탈의 DRI 시범 사업에 공급할 200MW 규모의 덩케르크 전해 설비를 지원하고 있습니다. 남미에서의 노력은 칠레의 풍력 자원이 풍부한 마가야네스 지역과 브라질의 페셈 항구에 집중되어 있지만, 송전망 연결 지연으로 인해 일부 최종 결정은 2026년까지 미뤄졌습니다. 전반적으로, 다각화된 지역 파이프라인, 허브 계획, 수출 프로젝트가 전 세계 수소 가스 시장의 확장을 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the hydrogen gas market size was valued at 113.91 Million tons in 2025 and is estimated to grow from 118.07 Million tons in 2026 to reach 141.25 Million tons by 2031, at a CAGR of 3.65% during the forecast period (2026-2031).
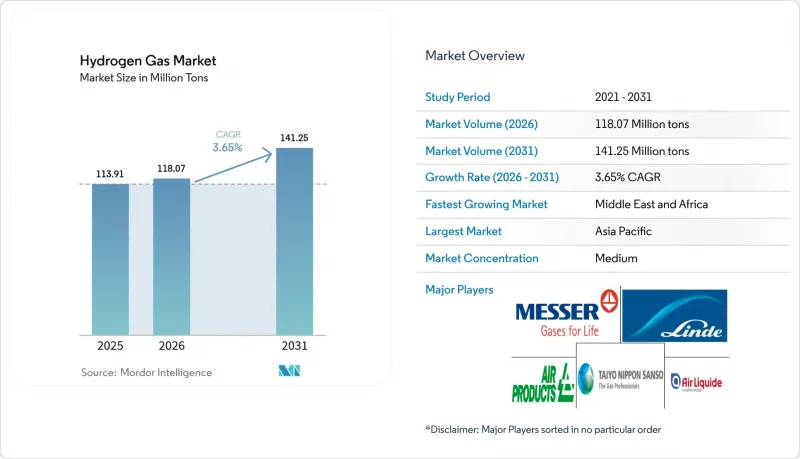
This report is Segmented by Distribution (Pipeline, High-Pressure Tube Trailer, and Cylinder), Application (Ammonia, Methanol, Refining, Direct Reduced Iron (DRI), Fuel-Cell Vehicles (FCVs), and Other Applications), and Geography (Asia Pacific, North America, Europe, South America, and the Middle East and Africa). The Market Sizing and Forecasts are Provided in Terms of Volume (tons).
Global Hydrogen Gas Market Trends and Insights
Refinery Desulfurization Regulations
International Maritime Organization fuel rules and US Tier 3 gasoline standards increase hydrotreater hydrogen demand by 5-8% for each incremental sulfur cut. Gulf Coast, Rotterdam, and Singapore refineries therefore expand on-site steam-methane reformers tied into dedicated pipelines, locking in multi-year merchant contracts. Emerging-market refineries still purchasing tube-trailer gas pay USD 0.50-0.80 more per kg on a delivered basis. ISO 14001 reporting now requires disclosure of hydrogen carbon intensity, which is steering spot purchases toward lower-emission supply. Compliance deadlines through 2026 sustain baseline demand even as electrolyzer retrofits near parity in carbon-priced regions.
Government Incentives for Green H2
Section 45V of the US Inflation Reduction Act offers up to USD 3 per kg for hydrogen below 0.45 kg CO2-eq, stimulating co-located renewable-power electrolyzers. Europe's Hydrogen Bank awarded EUR 720 million of contracts-for-difference in 2024 to narrow the cost gap with grey hydrogen, but auctioned volumes remain a fraction of the 10 Mt annual import target for 2030. Japan, China, and South Korea extend purchase subsidies and feed-in tariffs that underpin multi-megawatt stack orders, driving Chinese alkaline electrolyzer prices under USD 200 per kW according to manufacturer disclosures. These layered incentives bring the hydrogen gas market closer to cost competitiveness in mobility, steel, and fertilizer.
Expensive Storage and Transport Logistics
Compressed storage at 350 bar packs one-tenth the energy density of diesel, so tube-trailer fleets incur delivery premiums above USD 2 per kg on routes exceeding 300 km. Liquefaction consumes 25-35% of hydrogen's lower heating value and needs cryogenic tanks costing about USD 1,000 per kg daily throughput. Liquid-organic carriers cut boil-off losses yet suffer 40% round-trip efficiency losses and costly dehydrogenation catalysts. New hydrogen-grade pipelines run USD 3-5 million per km before right-of-way, limiting deployments in South America and Sub-Saharan Africa, where greenfield projects must bundle production and distribution capex. These costs weigh on near-term economics for the hydrogen gas industry.
Other drivers and restraints analyzed in the detailed report include:
- Rising Fuel-Cell Vehicle Roll-out
- Hydrogen-Gas-Grid Blending Mandates
- Community Opposition to New H2 Pipelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pipeline networks supplied 58.42% of the hydrogen gas market size in 2025 and are projected to expand at a 4.12% CAGR during the forecast period (2026-2031) as refineries and ammonia plants demand uninterrupted flows. Tube trailers remain essential for 50-500 kg-per-day industrial users lacking spur lines, while cylinder packs shrink in laboratories and telecom backup systems that transition to cartridge formats. Emerging export pipelines reinforce future growth: Saudi Arabia's 1,500-km NEOM line to Aqaba will feed green-ammonia export, and Europe plans to repurpose 11,600 km of gas transmission lines, trimming build costs 60% versus new construction. The Middle East and Africa lead pipeline additions, supporting gigawatt electrolyzers that target delivered costs of USD 1.50-2.00 per kg by 2030.
Tube-trailer economics improve where demand is fragmented; a 300-bar rig carrying 1,000 kg can serve six customers within 200 km, lowering deadhead mileage 20-30% using advanced route optimization. Cylinder packs still appeal to seasonal float-glass and specialty-welding shops, yet five-year hydrostatic tests under ISO 11114 inflate lifetime costs. In the hydrogen gas market, distribution portfolios therefore balance high-volume pipelines with flexible road logistics until regional demand clusters justify new steel.
Complete Report Scope:
- By Distribution
- Pipeline
- High-pressure tube trailer
- Cylinder
- By Application
- Ammonia
- Methanol
- Refining
- Direct Reduced Iron (DRI)
- Fuel-cell Vehicles (FCVs)
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 34.23% of the 2025 hydrogen gas market, propelled by China's 1,104 refueling stations, Japan's ammonia-import plans, and South Korea's 6.2 Mt 2040 consumption target. China's provincial grants for 10 MW-plus electrolyzers slashed alkaline stack costs below USD 200 per kW, half the European average, positioning Chinese suppliers for export. India's National Hydrogen Mission commits INR 197 billion (USD 2.4 billion) to produce 5 Mt by 2030, focusing on Gujarat and Odisha corridors with sub-INR 2 kWh solar tariffs. ASEAN pilots in Thailand, Singapore, and Malaysia test grid blending and coal-plant ammonia co-firing while awaiting carbon-pricing clarity.
The Middle East and Africa are expected to record the fastest 4.12% CAGR during the forecast period (2026-2031). Projects in Saudi Arabia, UAE, Oman, and Egypt couple 30-40% capacity-factor solar with desalination, reaching projected costs of USD 1.50-2.00 per kg by 2030. The NEOM venture will ship 650 t-per-day hydrogen as ammonia from late 2026, while South Africa's Boegoebaai targets 400,000 t green-ammonia from 2028 despite desalination add-ons of USD 0.30-0.50 per kg.
In North America, the US Department of Energy funded seven regional hubs, each producing 50,000-100,000 t annually for refining, fertilizer, and transport. Canada pursues blue hydrogen with carbon capture in Alberta and green hydrogen via hydropower in Quebec, eyeing EU exports once carbon-border levies finalize. Europe repurposes legacy gas grids; Germany allows 20% blends in select segments, the UK plans a 100% hydrogen village, and France backs a 200 MW Dunkirk electrolyzer supplying ArcelorMittal's DRI pilot. South American ambitions concentrate in Chile's high-wind Magallanes and Brazil's Pecem port, although grid-tie delays push several final decisions into 2026. Collectively, diversified regional pipelines, hub programs, and export projects underpin the hydrogen gas market's global expansion.
- Aditya Birla Chemicals
- Air Liquide
- Air Products and Chemicals, Inc.
- BASF SE
- Equinor ASA
- Gulf Cryo
- Iwatani Corp.
- Kawasaki Heavy Industries, Ltd.
- Linde plc
- MATHESON Tri-Gas, Inc.
- Messer SE & Co. KGaA
- TAIYO NIPPON SANSO CORPORATION
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Refinery Desulfurization Regulations
- 4.2.2 Government Incentives for Green H2
- 4.2.3 Rising Fuel-Cell Vehicle Roll-out
- 4.2.4 Hydrogen-Gas-Grid Blending Mandates
- 4.2.5 Surplus-Renewables-Driven Power-to-Gas Economics
- 4.3 Market Restraints
- 4.3.1 Expensive Storage and Transport Logistics
- 4.3.2 Community Opposition to New H2 Pipelines
- 4.3.3 Water-Scarcity Constraints in Arid Regions
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Distribution
- 5.1.1 Pipeline
- 5.1.2 High-pressure tube trailer
- 5.1.3 Cylinder
- 5.2 By Application
- 5.2.1 Ammonia
- 5.2.2 Methanol
- 5.2.3 Refining
- 5.2.4 Direct Reduced Iron (DRI)
- 5.2.5 Fuel-cell Vehicles (FCVs)
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Russia
- 5.3.3.6 NORDIC Countries
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Aditya Birla Chemicals
- 6.4.2 Air Liquide
- 6.4.3 Air Products and Chemicals, Inc.
- 6.4.4 BASF SE
- 6.4.5 Equinor ASA
- 6.4.6 Gulf Cryo
- 6.4.7 Iwatani Corp.
- 6.4.8 Kawasaki Heavy Industries, Ltd.
- 6.4.9 Linde plc
- 6.4.10 MATHESON Tri-Gas, Inc.
- 6.4.11 Messer SE & Co. KGaA
- 6.4.12 TAIYO NIPPON SANSO CORPORATION
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment