|
시장보고서
상품코드
2122952
급성 허혈성 뇌졸중 진단 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Acute Ischemic Stroke Diagnosis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
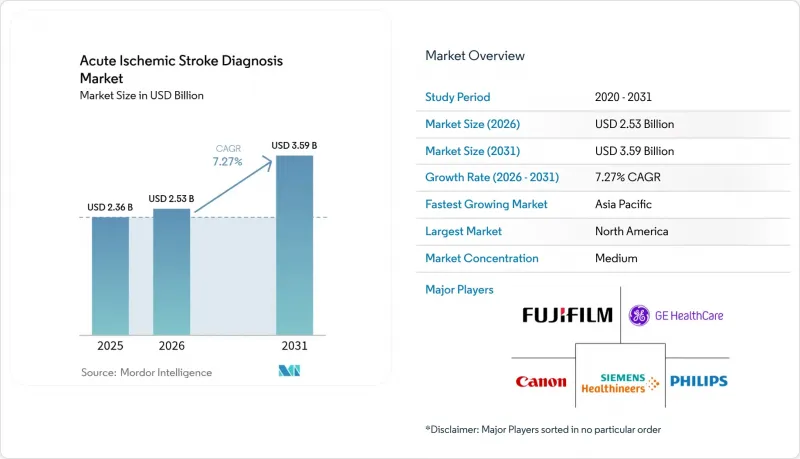
에 의하면, 급성 허혈성 뇌졸중 진단 시장 규모는 2025년 23억 6,000만 달러로 평가되었습니다. 2026년에는 25억 3,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 7.27%로 성장을 지속하여, 2031년에는 35억 9,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 진단 기술(컴퓨터 단층촬영, 자기공명영상, 기타), AI 소프트웨어 기능(조기 사건 분류 및 경보, 기타), 진료 환경(병원 내 응급실, 기타), 최종 사용자(병원, 영상진단센터, 기타), 지역(북미, 기타)별로 세분화되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 급성 허혈성 뇌졸중 진단 시장 동향 및 인사이트
65세 이상 인구에서 급성 허혈성 뇌졸중(AIS) 발생률 증가
세계 인구에서 65세 이상이 차지하는 비율은 2030년까지 16%를 나타낼 것으로 예측되며, 65세 이후 10년마다 뇌졸중 발생률이 2배로 증가하기 때문에 연령 조정 발생률이 정체 상태에 있는 지역에서도 진단 수요는 지속될 것으로 예측됩니다. 일본에서는 뇌졸중이 의심되는 사례의 75%가 고령자에게서 발생한다는 사실에 대응하여, 내원 후 60분 이내에 CT 또는 MRI 검사를 실시하는 것이 이미 의무화되어 있습니다. 미국 메디케어 데이터에 따르면, 응급 현장에서의 조기 인식과 영상 검사의 신속화로 인해 경증 뇌졸중으로 인한 입원이 증가하고 있으며, 급성기 치료 흐름으로 이송되는 환자층이 더욱 확대되고 있습니다. 이러한 인구 통계학적 현실은 급성 허혈성 뇌졸중 진단 시장의 모든 부문에 지속적인 호재로 작용하고 있습니다.
다중 모드 CT·MR 영상 촬영 프로토콜의 보급 확대
현재 지침에 따르면, 마지막으로 건강했던 시점으로부터 24시간 이내의 모든 환자에 대해 CT 혈관조영술과 CT 관류 검사가 권장되며, 발병 후 6시간이 지나도 조직 기반 분류가 표준화되어 있습니다. 미국의 종합 뇌졸중 센터에서는 관류 불일치가 혈전 제거술의 양호한 예후를 예측한다는 증거에 힘입어, 2025년에는 다중 모드 CT 프로토콜의 채택률이 18% 증가했습니다. 듀얼 에너지 CT 플랫폼은 스캔 시간을 3분 이하로 단축하여 혼잡한 응급실에서 ‘이송부터 영상 촬영까지’의 목표 시간을 달성하는 데 기여하고 있습니다. 후순환 영역의 경색에 대해서는 MRI가 여전히 뛰어난 감도를 유지하고 있지만, 촬영 시간이 길기 때문에 CT가 일선에서 계속해서 중요한 역할을 담당하고 있습니다.
고성능 스캐너의 높은 도입 비용 및 유지 관리 비용
광자 계수형 CT의 가격은 320만 달러인 반면, 128슬라이스 CT는 180만 달러이며, 여기에 연간 유지보수 계약비로 25만 달러가 추가됩니다. 이러한 금액은 병상 수 200개 규모의 많은 병원의 총 장비 예산을 상회합니다. 인도의 지역 병원들은 이러한 격차를 여실히 보여주고 있습니다. CT를 보유한 곳은 고작 14%, MRI를 도입한 곳은 2% 미만에 불과하며, 정부의 보조금이 있음에도 불구하고 도입이 제한되고 있습니다.
부문별 분석
다중 모드 CT 영상은 2025년 기술 매출의 48.55%를 차지하며, 초급성기 분류 과정에서 급성 허혈성 뇌졸중 진단 시장의 주력으로서의 위상을 뚜렷이 했습니다. AI 소프트웨어에 기인한 급성 허혈성 뇌졸중 진단 시장 규모는 현재로서는 작지만, 구독형 가격 책정이 현금 흐름에 제약이 있는 병원의 상황에 부합하기 때문에 가장 빠르게 확대될 것으로 예측됩니다. MRI는 후두와 뇌졸중이나 미세 출혈의 감지에서 일정한 위치를 유지하고 있지만, 광자 계수 CT가 MRI에 필적하는 해상도와 더 짧은 스캔 시간을 실현함에 따라 그 점유율은 소폭 하락할 것으로 보입니다.
AI 의사결정 지원 소프트웨어는 보험사가 치료 시작까지의 시간 단축을 높이 평가하고 있으며, 방사선과 전문의 부족으로 인해 자동화된 사전 판독에 대한 수요가 증가하고 있어, 2031년까지 연평균 성장률(CAGR) 14.25%로 성장할 전망입니다. 조기 도입 기관의 보고에 따르면, 대혈관 폐색의 검출 감도는 94%를 초과하고, 위양성률은 8% 이하로 유지되고 있으며, 이러한 지표는 1회당 50-80달러의 이용 요금을 정당화해 줍니다. CT 하드웨어 업그레이드와 클라우드 기반 AI 제품군의 융합을 통해 영상 장비 제조업체와 전문 벤더는 화질뿐만 아니라 워크플로우 속도 면에서도 경쟁할 수 있게 될 것입니다.
현재 모든 뇌졸중 센터가 혈전 제거술의 적응증 판단을 위해 신속한 폐색 확인을 우선시하고 있기 때문에 대혈관 폐색 감지는 2025년 AI 매출의 40.53%를 차지했습니다. 후기 창에서 혈전 제거술 프로토콜은 경과 시간뿐만 아니라 조직의 생존 가능성에 의존하기 때문에 관류 불일치 정량화 도구 시장 점유율은 점차 확대될 것으로 보입니다. 폐색 감지, 관류 맵, 출혈 배제를 단일 대시보드에 통합한 공급업체는 IT 통합을 간소화함으로써 계약을 수주하고 있습니다. 모바일 푸시 알림을 통해 팀의 동원 시간이 단축됩니다. 초기 데이터에 따르면, 알고리즘이 신경 중재 치료팀에 자동으로 호출을 보낼 경우, ‘도착부터 서혜부 천자까지’의 시간이 중앙값 기준으로 23분 단축되는 것으로 나타났습니다.
지역별 분석
북미는 2025년에도 세계 시장 점유율 36.23%를 유지했습니다. 이는 종합 뇌졸중 센터가 200곳을 넘고, 진료 보수가 영상 유도 기반의 품질 지표와 밀접하게 연동되어 있기 때문입니다. 미국 식품의약국(FDA)은 2024년 이후 12개의 AI 뇌졸중 알고리즘을 승인했으며, 병원에는 속도, 클라우드 통합, 구독 가격을 놓고 경쟁하는 여러 공급업체 옵션이 제공되고 있습니다. 캐나다의 주립 텔레스트로크 네트워크를 통해 원격 전송 시간이 단축되었습니다. 한편, 멕시코에서는 지방 병원에 18대의 CT 스캐너가 추가되었지만, 신경방사선과 전문의 부족으로 인해 영상 판독에 소요되는 시간이 길어지는 과제에 여전히 직면해 있습니다.
아시아태평양의 급성 허혈성 뇌졸중 진단 시장은 연평균 성장률(CAGR) 11.42%라는 가장 빠른 속도로 확대될 전망입니다. 이는 중국과 인도가 영상 검사 준수를 의무화하는 뇌졸중 등록 시스템을 구축하고 있으며, 민간 병원 체인이 의료 관광객을 유치하기 위해 첨단 스캐너에 막대한 투자를 하고 있기 때문입니다. 중국에서는 현재 1,200곳의 뇌졸중 센터가 운영되고 있으며, 2022년 이후 35% 증가했습니다. 또한, 진료 보수를 영상 검사 프로토콜 준수 여부와 연계하고 있습니다. 인도에서는 2024년에 시작된 심혈관·뇌졸중 프로그램에서 CT 장비 조달과 의사 연수에 1억 4,500만 달러가 배정되었습니다. 일본에서는 이미 뇌졸중이 의심되는 환자의 92%에 대해 60분 이내에 영상 검사를 실시하고 있지만, 급속히 고령화가 진행되는 사회에서 미세혈관 검출 정확도를 높이기 위해 초고자기장 MRI 도입에 주력하고 있습니다.
유럽에서는 2025년, 독일의 340개 인증 뇌졸중 유닛이 다중 모달 CT 관류 검사를 표준화한 것과, 영국이 혈전 제거술에 대한 접근성을 확대하기 위해 4,500만 파운드 상당의 스캐너와 AI 라이선스를 도입함으로써 상당한 수익이 창출되었습니다. 프랑스는 2024년에 8개의 AI 뇌졸중 검출 플랫폼에 CE 마크 승인을 부여하여, 이를 통해 공립 및 사립 병원의 신속한 도입이 진행되었습니다. 중동 및 아프리카는 여전히 발전 단계에 있지만, 목표 지향적인 투자를 유치하고 있습니다. 아랍에미리트에서는 2024년에 14대의 새로운 CT 스캐너가 도입되었으며, 남아프리카공화국의 소수 종합 뇌졸중 센터에서는 제한된 신경방사선학 역량을 보완하기 위해 AI 활용을 검토하고 있습니다. 남미에서는 브라질의 민간 병원 체인이 주도적인 역할을 하고 있지만, 공립 병원은 뒤처져 있어 진료 접수부터 CT 검사까지 소요되는 시간의 중앙값이 여전히 90분을 초과하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the acute ischemic stroke diagnosis market size is expected to grow from USD 2.36 billion in 2025 to USD 2.53 billion in 2026 and is forecast to reach USD 3.59 billion by 2031 at 7.27% CAGR over 2026-2031.
This report is Segmented by Diagnostic Technology (Computed Tomography, Magnetic Resonance Imaging, and More), AI Software Function (Early-Event Triage & Alerting, and More), Care Setting (Emergency Department In-Hospital, and More), End User (Hospitals, Diagnostic Imaging Centers, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Acute Ischemic Stroke Diagnosis Market Trends and Insights
Growing AIS Incidence in 65-Plus Population
The share of the global population aged 65 and older will reach 16% by 2030, and stroke incidence doubles with each successive decade after 65, sustaining diagnostic demand even in regions with plateauing age-adjusted rates. Japan already mandates CT or MRI within 60 minutes of presentation for suspected stroke, a policy response to the fact that 75% of domestic cases occur in seniors. U.S. Medicare data show rising hospitalizations for mild strokes thanks to faster pre-hospital recognition and imaging, further enlarging the pool of patients routed into acute workflows. These demographic realities create a durable tailwind for every segment of the acute ischemic stroke diagnosis market.
Wider Adoption of Multimodal CT & MR Imaging Protocols
Guidelines now recommend CT angiography and CT perfusion for all patients within 24 hours of last-known-well, normalizing tissue-based triage beyond the first 6 hours. U.S. comprehensive stroke centers increased multimodal CT protocol adoption by 18% in 2025, driven by evidence that perfusion mismatch predicts favorable thrombectomy outcomes. Dual-energy CT platforms compress scan time below 3 minutes and help overcrowded emergency departments meet door-to-imaging targets. Although MRI retains superior sensitivity for posterior circulation infarcts, its longer acquisition time keeps CT in the front-line role.
High Capital & Maintenance Cost of Advanced Scanners
Photon-counting CT lists at USD 3.2 million versus USD 1.8 million for a 128-slice CT, and annual service contracts add USD 250,000, numbers that exceed the entire equipment budget of many 200-bed hospitals. District-level hospitals in India illustrate the gap: only 14% possess CT, and fewer than 2% run MRI, constraining adoption despite government subsidies.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Endovascular-Thrombectomy 24-Hour Time-Window
- National Stroke-Care Quality Initiatives & Reimbursement Incentives
- Shortage of Neuroradiologists in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Multimodal CT imaging generated 48.55% of 2025 technology revenue, underscoring its status as the workhorse of the acute ischemic stroke diagnosis market share during hyperacute triage. The acute ischemic stroke diagnosis market size attributed to AI software, though smaller today, is projected to rise fastest because subscription pricing aligns with cash-flow-constrained hospitals. MRI maintains a foothold for posterior fossa strokes and microbleed detection, but its share will erode marginally as photon-counting CT converges on MRI-like resolution with shorter scan times.
AI decision-support software is set to scale at 14.25% CAGR through 2031 because payors reward time-to-treatment performance and radiologist shortages create demand for automated pre-reads. Early adopters report sensitivity exceeding 94% for large-vessel occlusion, while false positives remain under 8%, metrics that justify per-use fees of USD 50-80. The convergence of CT hardware upgrades with cloud-deployed AI suites positions imaging OEMs and pure-play vendors to compete on workflow speed rather than pixel quality alone.
Large-vessel occlusion detection held 40.53% of 2025 AI revenue as every stroke center now prioritizes rapid occlusion identification for thrombectomy routing. Perfusion mismatch quantification tools will capture incremental share because late-window thrombectomy protocols depend on tissue viability rather than elapsed time alone. Vendors packaging occlusion detection, perfusion maps, and hemorrhage exclusion into a single dashboard win contracts by simplifying IT integration. Mobile push notifications reduce team activation times; early data show a 23-minute median reduction in door-to-groin puncture when algorithms auto-page neurointerventional teams.
Complete Report Scope:
- By Diagnostic Technology
- Computed Tomography (NCCT, CTA, CTP)
- Magnetic Resonance Imaging (DWI, SWI, ASL)
- Carotid & Trans-cranial Ultrasound
- Cerebral Angiography (DSA)
- Blood-based Biomarker Tests
- AI-enabled Stroke Decision-Support Software
- By AI Software Function
- Early-Event Triage & Alerting
- Large-Vessel-Occlusion Detection
- Perfusion Mismatch Quantification
- Hemorrhage Exclusion
- By Care Setting
- Emergency Department In-hospital
- Mobile Stroke Unit
- Telestroke Hub & Spoke
- By End User
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgery Centers / Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 36.23% global share in 2025 because comprehensive stroke centers exceed 200 and reimbursement is tightly linked to imaging-guided quality metrics. The United States Food and Drug Administration has cleared 12 AI stroke algorithms since 2024, supplying hospitals with multiple vendor options that compete on speed, cloud integration, and subscription price. Canada's provincial telestroke networks have shortened remote transfer times, while Mexico added 18 CT scanners to regional hospitals but still struggles with a neuroradiologist deficit that slows interpretation turnaround.
The acute ischemic stroke diagnosis market in Asia-Pacific will expand fastest at 11.42% CAGR because China and India are building stroke registries that compel imaging compliance, and private hospital chains are investing heavily in advanced scanners to appeal to medical tourists. China now operates 1,200 stroke centers, a 35% jump since 2022, and ties reimbursement to imaging protocol adherence. India's 2024-launched cardiovascular and stroke program earmarked USD 145 million for CT procurement and physician training. Japan, already imaging 92% of stroke suspects within 60 minutes, focuses on ultra-high-field MRI to improve microvascular detection in its rapidly aging society.
Europe generated a significant revenue in 2025 as Germany's 340 certified stroke units standardized multimodal CT perfusion, and the United Kingdom added GBP 45 million worth of scanners and AI licenses to expand thrombectomy access. France issued CE-Mark approval to eight AI stroke detection platforms in 2024, triggering rapid procurement by public and private hospitals. Middle East and Africa remain nascent but attract targeted investment; the United Arab Emirates installed 14 new CT scanners in 2024, and South Africa's handful of comprehensive stroke centers are exploring AI to amplify limited neuroradiology capacity. South America is led by Brazil's private chains, yet public hospitals lag, with median door-to-CT times still above 90 minutes.
- Canon
- Ceribell
- Esaote
- FUJIFILM
- GE Healthcare
- Hyperfine
- Koninklijke Philips
- Medtronic Neurovascular
- MicroPort
- MicroVention
- Neusoft
- Nihon Kohden
- NovaSignal
- Penumbra
- RapidAI
- Siemens Healthineers
- Stryker Neurovascular
- Viz.ai
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing AIS incidence in 65-plus population
- 4.2.2 Wider adoption of multimodal CT & MR imaging protocols
- 4.2.3 Expanding endovascular-thrombectomy 24-h time-window
- 4.2.4 National stroke-care quality initiatives & reimbursement incentives
- 4.2.5 Photon-counting CT & 7 T MRI enabling microvascular stroke detection
- 4.2.6 Subscription AI-triage bundles tied to teleradiology contracts
- 4.3 Market Restraints
- 4.3.1 High capital & maintenance cost of advanced scanners
- 4.3.2 Shortage of neuroradiologists in emerging markets
- 4.3.3 Algorithmic-bias concerns slowing AI regulatory clearance
- 4.3.4 Xenon-CT consumable supply disruptions raising protocol costs
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Diagnostic Technology
- 5.1.1 Computed Tomography (NCCT, CTA, CTP)
- 5.1.2 Magnetic Resonance Imaging (DWI, SWI, ASL)
- 5.1.3 Carotid & Trans-cranial Ultrasound
- 5.1.4 Cerebral Angiography (DSA)
- 5.1.5 Blood-based Biomarker Tests
- 5.1.6 AI-enabled Stroke Decision-Support Software
- 5.2 By AI Software Function
- 5.2.1 Early-Event Triage & Alerting
- 5.2.2 Large-Vessel-Occlusion Detection
- 5.2.3 Perfusion Mismatch Quantification
- 5.2.4 Hemorrhage Exclusion
- 5.3 By Care Setting
- 5.3.1 Emergency Department In-hospital
- 5.3.2 Mobile Stroke Unit
- 5.3.3 Telestroke Hub & Spoke
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Diagnostic Imaging Centers
- 5.4.3 Ambulatory Surgery Centers / Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Canon Medical Systems
- 6.3.2 Ceribell
- 6.3.3 Esaote SpA
- 6.3.4 Fujifilm Holdings
- 6.3.5 GE HealthCare
- 6.3.6 Hyperfine
- 6.3.7 Koninklijke Philips N.V.
- 6.3.8 Medtronic Neurovascular
- 6.3.9 MicroPort Scientific
- 6.3.10 MicroVention
- 6.3.11 Neusoft Medical
- 6.3.12 Nihon Kohden
- 6.3.13 NovaSignal
- 6.3.14 Penumbra Inc.
- 6.3.15 RapidAI
- 6.3.16 Siemens Healthineers
- 6.3.17 Stryker Neurovascular
- 6.3.18 Viz.ai
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment