

|
시장보고서
상품코드
2122954
성인 악성 신경교종 치료제 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Adult Malignant Glioma Therapeutics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 성인 악성 신경교종 치료제 시장 규모는 2025년에 31억 7,000만 달러로 평가되었고, 2026년 34억 3,000만 달러에서 2031년까지 50억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 8.18%를 기록할 전망입니다.
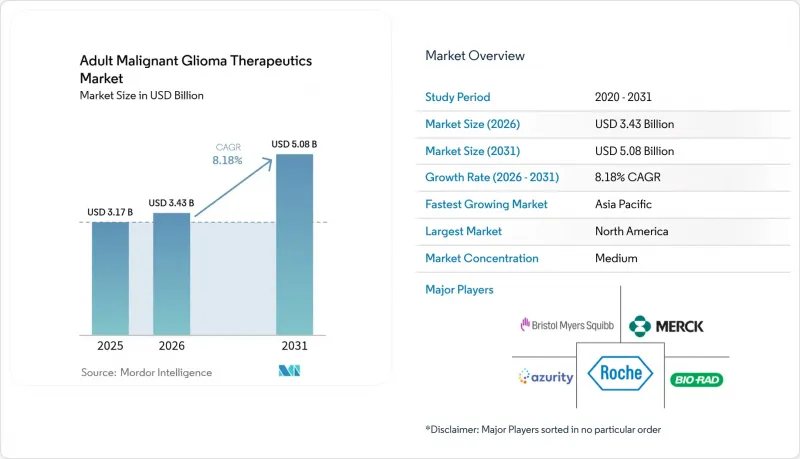
본 보고서는 질환 유형별(다형성 교모세포종, 퇴행성 성상세포종, 퇴행성 저돌기교종, 기타), 치료법별(화학요법, 표적 치료, 면역요법, 의료기기를 이용한 치료, 기타), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 성인 악성 신경교종 치료제 시장 동향 및 인사이트
악성 신경교종의 발생률 증가
역학적 예측에 따르면, 아시아의 신경교종 환자 수는 2040년까지 39.3% 급증할 것으로 예상되며, 이로 인해 성인 악성 신경교종 치료제 시장은 신흥 경제국으로 근본적으로 이동하게 될 것입니다. 영상 진단 인프라가 정비됨에 따라 종양의 조기 발견이 가능해졌으며, 그동안 기록되지 않았던 환자들이 각국의 등록부에 추가되고 있습니다. 또한, 아시아의 젊은 층은 치료 내약성이 높아, 지역 한정 임상시험 및 지역 특유의 프로토콜 조정이 촉진되고 있습니다. 중국 일류 의료 기관의 생존율은 이미 많은 서유럽 국가의 벤치마크를 상회하고 있어, 생물학적 요인이나 진료 경로에 차이가 있을 가능성을 시사하고 있습니다. 이에 따라 제약 기업들은 유전적 다양성을 지닌 집단에서 분자 표적 치료법의 유효성을 검증하기 위해 중국, 인도, 한국에서의 임상시험 규모를 확대되고 있습니다.
공공 부문의 연구 개발(R&D) 자금 지속적 지원
성인 악성 신경교종 치료제 시장은 초기 단계의 위험을 상쇄하는 정부 지출의 혜택을 받고 있습니다. 캘리포니아 재생의학 연구소(CIRM)는 UCSF의 CAR-T 교모세포종 프로그램에 1,100만 달러를 배정했으며, 이는 뇌종양을 대상으로 한 NIH 및 국방부(DoD)의 예산 항목을 보완하는 것입니다. 유럽에서도 유사한 움직임이 나타나고 있으며, ‘Horizon Europe’의 보조금이 LEGATO 임상시험을 지원하고 있습니다. 이 임상시험에는 11개국 43개 기관에서 411명의 환자가 등록되어 있습니다. 공공 공동 자금은 직접적인 보조금에 그치지 않고, 세제 혜택 및 산학 협력 인큐베이터까지 확대되어, 이를 통해 synNotch 세포 치료법이나 나노 입자 전달 시스템과 같은 ‘퍼스트 인 클래스(First-in-Class)’ 개념에 대한 자금 조달 장벽이 낮아지고 있습니다.
후기 임상시험의 낮은 성공률
3상 교모세포종 치료 프로그램의 성공률은 여전히 5% 미만에 머물러 있어 투자자의 신뢰를 떨어뜨리고 필요한 자본 규모를 부풀리고 있습니다. 그 결과, 성인 악성 신경교종 치료제 시장에서는 기업들이 고위험 중추신경계(CNS) 관련 자산과 고형암 부문 사업 간의 균형을 모색하는 가운데, 포트폴리오의 다각화가 진행되고 있습니다. 실패의 원인으로는 오프타겟 독성, 혈액-뇌 장벽 투과성 부족, 또는 대조군의 성과가 더 우수한 경우 등이 꼽힙니다. 이러한 좌절이 발생할 때마다 5억 달러의 매몰 비용이 발생할 가능성이 있어, 그 결과 재무적 위험을 분담하는 제휴가 확대되고 있습니다. 이에 대응하여 벤처 신디케이트는 마일스톤에 따른 엄격한 단계별 자금 조달 조건을 포함시키고 있으며, 이로 인해 소규모 진출기업의 개발 기간이 장기화되고 있습니다.
부문 분석
2025년에는 다형성 교모세포종이 성인 악성 신경교종 치료제 시장 점유율의 57.92%를 차지하며 1위를 기록했습니다. 이러한 수준에 따라 스폰서들의 관심은 혈액-뇌 장벽 투과성을 높이는 화학적 접근법이나 적응형 임상시험 설계로 쏠렸습니다. 퇴형성 빈돌기교종은 보라시데닙 등 IDH를 표적으로 하는 획기적인 진전에 힘입어 2031년까지 연평균 성장률(CAGR) 9.12%로 성장을 지속하고, 있으며, 성인 악성 신경교종 치료제 시장 규모에 대한 절대적인 기여도를 높이는 궤도에 올라 있습니다. 퇴형성 성세포종에서는 병용 요법에 대한 자금 조달이 착실히 진행되고 있는 반면, 퇴형성 올리고아스트로사이트종에서는 WHO의 분류 재검토에 따라 환자들이 돌연변이 특이적 프로토콜로 배정되게 된 점이 호재로 작용하고 있습니다.
위약군의 11.1개월에 비해 27.7개월의 무재발 생존 기간 중앙값을 달성한 보라시데닙의 성공은 유전자형에 기반한 치료 설계가 조직형 중심의 접근법을 얼마나 능가하는지를 보여줍니다. 패널 시퀀싱이 일상화됨에 따라, 개발자들은 저분자 화합물 라이브러리를 명확하게 정의된 하위 집단에 매칭할 수 있게 되어, 임상시험의 통계적 검출력을 향상시키고 조건부 승인을 촉진할 수 있게 됩니다. 따라서 성인 악성 신경교종 치료제 시장은 반응률이 높은 코호트에 자본 효율을 집중시키는 소규모이며 신속한 임상시험으로 전환되고 있습니다.
지역별 분석
북미는 견고한 보험 환급 제도, NCI 지정 임상시험 네트워크, 높은 진단률에 힘입어 2025년 성인 악성 신경교종 치료제 시장 규모의 41.32%를 차지했습니다. 미국은 패스트 트랙(Fast Track) 지정에서 주도적인 입지를 차지하고 있으며, 보라시데닙과 같은 제품이 주요 임상 데이터 확보 후 1년 이내에 승인을 받을 수 있도록 하고 있습니다. 캐나다에서는 각 주의 의료 기술 평가가 통합되어 있어, 캐나다 보건부의 결정이 FDA의 선례와 일치할 경우 보험 환급이 신속하게 이루어집니다.
아시아태평양은 연평균 성장률(CAGR) 11.55%로 가장 빠르게 성장하는 시장이며, 최신 방사선 치료 시설이 갖춰지고, 중국, 일본, 한국의 의료시설이 전 세계 임상시험 프로토콜에 임베디드되는 움직임이 가속화되고 있습니다. 베이징과 상하이의 대규모 3차 의료기관에서 보고된 우수한 생존율 지표를 계기로, 프로토콜의 차이점을 규명하기 위한 비교 유효성에 관한 공동 연구가 시작되고 있습니다. 아세안 상호인정협정에 따른 규정 조화로 의료기기를 이용한 치료법의 진입 장벽이 더욱 낮아지면서, 이 지역은 치료 건수와 혁신의 거점으로서 입지를 확고히 하고 있습니다.
유럽에서는 EMA의 ‘프로젝트 오비스(Project Orbis)’를 통해 시장 진입까지의 시간이 단축되며 안정적인 성장세가 유지되고 있습니다. 임상시험 개시 건수 면에서는 독일, 프랑스, 영국이 주도적인 역할을 수행하는 반면, 남유럽 및 동유럽 국가들은 지역 간 윤리 심사 통합의 혜택을 누리고 있습니다. ‘Horizon Europe’의 보조금은 LEGATO와 같은 다국적 데이터셋에 자금을 지원함으로써, NICE나 G-BA의 결정에 직접 반영되는 연구자 주도적 증거 창출을 강화하고 있습니다. 이처럼 성인 악성 신경교종 치료제 시장은 대륙 전체에 걸친 플랫폼 조화를 누리고 있으며, 주요 임상시험 피험자 등록에 있어 후원사의 투자 수익률(ROI)이 향상되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the adult malignant glioma therapeutics market size was valued at USD 3.17 billion in 2025 and estimated to grow from USD 3.43 billion in 2026 to reach USD 5.08 billion by 2031, at a CAGR of 8.18% during the forecast period (2026-2031).
This report is Segmented by Disease Type (Glioblastoma Multiforme, Anaplastic Astrocytoma, Anaplastic Oligodendroglioma, and More), Therapy (Chemotherapy, Targeted Therapy, Immunotherapy, Device-Based Therapy, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Adult Malignant Glioma Therapeutics Market Trends and Insights
Rising Incidence of Malignant Gliomas
Epidemiological projections indicate that Asian glioma cases will jump 39.3% by 2040, fundamentally shifting the Adult malignant glioma therapeutics market toward emerging economies. Improved imaging infrastructure now detects tumors earlier, adding previously undocumented patients to national registries. Younger Asian cohorts also present higher treatment tolerance, encouraging localized clinical trials and region-specific protocol adjustments. Survival rates from leading Chinese centers already surpass many Western benchmarks, implying potential biological or care-pathway differences. Drug developers therefore increase trial footprints in China, India, and South Korea to validate molecularly targeted regimens in genetically diverse populations.
Sustained Public-Sector R&D Funding
The adult malignant glioma therapeutics market benefits from government spending that offsets early-stage risk. The California Institute for Regenerative Medicine has allocated USD 11 million to UCSF's CAR-T glioblastoma program, complementing NIH and DoD line items aimed at brain cancer. Europe mirrors this trajectory through Horizon Europe grants that underpin the LEGATO study, which enrolls 411 patients at 43 sites across 11 countries. Public co-funding stretches beyond direct grants to include tax incentives and academic-industry incubators, thereby lowering capital barriers for first-in-class concepts such as synNotch cell therapies and nanoparticle delivery vehicles.
Low Late-Stage Trial Success Rates
Success rates in phase 3 glioblastoma programs remain below 5%, eroding investor confidence and inflating capital requirements. The Adult malignant glioma therapeutics market therefore witnesses portfolio diversification as companies balance high-risk CNS assets with solid-tumor franchises. Failures often stem from off-target toxicity, insufficient blood-brain-barrier penetration, or control-arm outperformance. Each setback can wipe USD 500 million in sunk costs, driving partnerships that share financial exposure. Venture syndicates react by inserting stringent milestone-based tranched financing, prolonging timelines for smaller entrants.
Other drivers and restraints analyzed in the detailed report include:
- Fast-Track & Breakthrough Designations for Novel Devices
- AI-Enabled Early Diagnosis & Treatment Planning
- Rapid Emergence of Temozolomide Resistance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Glioblastoma multiforme led with 57.92% of the adult malignant glioma therapeutics market share in 2025, a level that steered sponsor focus toward blood-brain-barrier penetration chemistry and adaptive trial designs. Anaplastic oligodendroglioma, aided by IDH-targeted breakthroughs such as vorasidenib, is registering a 9.12% CAGR to 2031 and is on course to raise its contribution to the Adult malignant glioma therapeutics market size in absolute terms. Anaplastic astrocytoma garners steady funding for combination regimens, while anaplastic oligoastrocytoma benefits from refined WHO re-classification that funnels patients into mutation-specific protocols.
The success of vorasidenib, which delivered 27.7-month median progression-free survival against 11.1 months for placebo, illustrates how genotype-guided design outperforms histology-centric approaches. As panel sequencing becomes routine, developers can match small-molecule libraries to well-defined subpopulations, improving statistical power in trials and facilitating conditional approvals. The Adult malignant glioma therapeutics market therefore shifts toward smaller, faster studies that direct capital efficiency toward high-response cohorts.
Complete Report Scope:
- By Disease Type
- Glioblastoma Multiforme
- Anaplastic Astrocytoma
- Anaplastic Oligodendroglioma
- Anaplastic Oligoastrocytoma
- Other High-Grade Gliomas
- By Therapy
- Chemotherapy
- Temozolomide
- Lomustine
- Carmustine
- Bevacizumab
- Other Alkylating Agents
- Targeted Therapy
- EGFR Inhibitors
- VEGF/VEGFR Inhibitors
- IDH Inhibitors
- Immunotherapy
- Checkpoint Inhibitors
- CAR-T/NK Cell Therapy
- Oncolytic Viruses
- Device-Based Therapy
- Radiation Therapy
- Gene & Cell Therapy
- Chemotherapy
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 41.32% of the Adult malignant glioma therapeutics market size in 2025, supported by robust reimbursement schemes, NCI-designated trial networks, and high diagnosis rates. The United States leads in fast-track designations, enabling products like vorasidenib to move from pivotal data to approval within a year. Canada integrates provincial health technology assessments that expedite reimbursement once Health Canada decisions align with FDA precedents.
Asia Pacific is the fastest-growing theatre at an 11.55% CAGR, adding modern radiotherapy suites and accelerating inclusion of Chinese, Japanese, and South Korean centers in global protocols. Superior survival metrics reported by large tertiary hospitals in Beijing and Shanghai have triggered comparative-effectiveness collaborations to decode protocol differences. Harmonized rules under the ASEAN Mutual Recognition Arrangement further reduce barriers for device-based therapies, positioning the region as a volume and innovation hub.
Europe posts stable momentum as EMA's Project Orbis shortens market entry gaps. Germany, France, and the United Kingdom dominate trial starts, while Southern and Eastern European countries benefit from pan-regional ethical-review alignment. Horizon Europe grants finance multi-national datasets such as LEGATO, reinforcing investigator-initiated evidence generation that feeds directly into NICE and G-BA decisions. The Adult malignant glioma therapeutics market thus enjoys continent-wide platform harmonization, improving sponsor ROI on pivotal enrollment.
- Roche
- Merck
- Pfizer
- Novocure
- Bristol-Myers Squibb
- Amgen
- Abbvie
- AstraZeneca
- Chimerix
- DelMar Pharma
- Sumitomo Heavy Industries
- TAE Life Sciences
- Bluebird Bio
- Immunomic Therapeutics
- Ono Pharma
- GlaxoSmithKline
- Novartis
- Boehringer Ingelheim
- Servier
- Sun Pharmaceuticals Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Incidence of Malignant Gliomas
- 4.2.2 Sustained Public-Sector R&D Funding
- 4.2.3 Fast-Track & Breakthrough Designations for Novel Devices
- 4.2.4 Ai-Enabled Early Diagnosis & Treatment Planning
- 4.2.5 Venture Capital Surge into BNCT Platforms
- 4.2.6 Availability of Bevacizumab Biosimilars
- 4.3 Market Restraints
- 4.3.1 Low Late-Stage Trial Success Rates
- 4.3.2 Rapid Emergence of Temozolomide Resistance
- 4.3.3 Boron-10 Isotope Supply-Chain Bottlenecks
- 4.3.4 Oncology R&D Capital Diverted to Higher-Incidence Tumors
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Disease Type
- 5.1.1 Glioblastoma Multiforme
- 5.1.2 Anaplastic Astrocytoma
- 5.1.3 Anaplastic Oligodendroglioma
- 5.1.4 Anaplastic Oligoastrocytoma
- 5.1.5 Other High-Grade Gliomas
- 5.2 By Therapy
- 5.2.1 Chemotherapy
- 5.2.1.1 Temozolomide
- 5.2.1.2 Lomustine
- 5.2.1.3 Carmustine
- 5.2.1.4 Bevacizumab
- 5.2.1.5 Other Alkylating Agents
- 5.2.2 Targeted Therapy
- 5.2.2.1 EGFR Inhibitors
- 5.2.2.2 VEGF/VEGFR Inhibitors
- 5.2.2.3 IDH Inhibitors
- 5.2.3 Immunotherapy
- 5.2.3.1 Checkpoint Inhibitors
- 5.2.3.2 CAR-T/NK Cell Therapy
- 5.2.3.3 Oncolytic Viruses
- 5.2.4 Device-Based Therapy
- 5.2.5 Radiation Therapy
- 5.2.6 Gene & Cell Therapy
- 5.2.1 Chemotherapy
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Italy
- 5.3.2.5 Spain
- 5.3.2.6 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 Japan
- 5.3.3.3 India
- 5.3.3.4 Australia
- 5.3.3.5 South Korea
- 5.3.3.6 Rest of Asia-Pacific
- 5.3.4 Middle East & Africa
- 5.3.4.1 GCC
- 5.3.4.2 South Africa
- 5.3.4.3 Rest of Middle East & Africa
- 5.3.5 South America
- 5.3.5.1 Brazil
- 5.3.5.2 Argentina
- 5.3.5.3 Rest of South America
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 F. Hoffmann-La Roche
- 6.3.2 Merck & Co.
- 6.3.3 Pfizer
- 6.3.4 Novocure
- 6.3.5 Bristol-Myers Squibb
- 6.3.6 Amgen
- 6.3.7 AbbVie
- 6.3.8 AstraZeneca
- 6.3.9 Chimerix
- 6.3.10 DelMar Pharma
- 6.3.11 Sumitomo Heavy Industries
- 6.3.12 TAE Life Sciences
- 6.3.13 Bluebird Bio
- 6.3.14 Immunomic Therapeutics
- 6.3.15 Ono Pharma
- 6.3.16 GlaxoSmithKline
- 6.3.17 Novartis
- 6.3.18 Boehringer Ingelheim
- 6.3.19 Servier
- 6.3.20 Sun Pharma
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


