

|
시장보고서
상품코드
2122957
육불화황 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Sulfur Hexafluoride - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
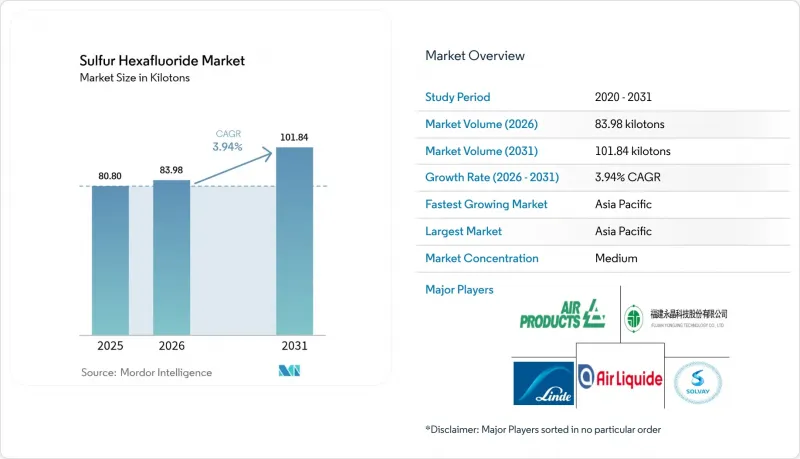
에 의하면, 2026년 육불화황 시장 규모는 83.98 킬로톤으로 추정되고, 2025년 80.80 킬로톤으로부터 확대해, 2031년에는 101.84 킬로톤에 이를 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 3.94%를 기록할 전망입니다.
본 보고서는 제품 유형별(전자·기술 등급, 초고순도 등급), 용도별(전력 및 에너지, 전자기기, 금속 제조, 의료 분야, 기타 용도), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 수량(톤) 단위로 표시되어 있습니다.
세계의 육불화황 시장 동향 및 인사이트
신흥국의 송전망 업그레이드 수요
중국의 육불화황(SF6) 배출량은 송전망 개발 사업자들이 기록적인 규모의 송전망 확장에 대응하기 위해 소형 가스 절연 변전소를 설치한 결과, 2011년 2.6Gg에서 2021년 5.1Gg로 증가했습니다. 인도는 급속한 도시화 속에서 전압 안정성을 확보하기 위해 SF6 개폐기 사용을 규정하는 송전망 현대화 사업에 200억 루피를 배정하고 있습니다. 일반적인 변전소 설비는 25년에서 50년 동안 계속 가동되므로, 설치와 관련된 모든 결정이 사실상 미래의 육불화황 시장 수요를 결정짓게 됩니다. 가스 절연 변전소는 공기 절연 변전소보다 45% 더 빠르게 전력을 공급할 수 있으며, 이러한 시간 단축은 송전망의 혼잡 완화를 서두르는 전력 사업자에게 큰 가치가 있습니다. 그 결과, 환경 대책을 둘러싼 논의가 격화되는 와중에도 육불화황 시장은 아시아태평양 전체에서 그 존재감을 계속해서 강화하고 있습니다.
반도체 및 액정 디스플레이(LCD) 플라즈마 에칭 시장의 성장
2047년까지 16개의 팹을 추가할 예정인 4,710억 달러 규모의 한국 반도체 클러스터는 초고순도 SF6 소비를 끌어올리는 자본 유입의 대표적인 사례입니다. 딥 트렌치 실리콘 에칭에서 SF6는 불소 라디칼을 생성하여 경쟁 가스보다 최대 100배 빠르게 재료를 제거함으로써, 3nm 이하 노드에서 처리량 목표를 달성할 수 있도록 보장합니다. 배출 억제 시스템 덕분에 직접 배출은 억제되고 있지만, 원료의 일부는 여전히 대기로 방출되고 있으며, 제조 능력 확대에 따라 규제 당국의 면밀한 조사가 진행되고 있습니다. 그럼에도 불구하고, 드롭인 대체재가 SF6과 동등한 에칭 정밀도를 실현할 수 있게 될 때까지는 공정 엔지니어들이 계속해서 SF6을 지정할 것이기 때문에 육불화황(SF6) 시장은 첨단 제조 밸류체인에 확고하게 뿌리내린 상태를 유지하고 있습니다.
엄격한 지구 온난화 대책 규제
유럽연합(EU)은 2026년부터 중전압 개폐 장치, 2032년부터 고전압 개폐 장치에 대한 SF6 사용을 금지하고 있어, 전력 사업자들은 개조 계획을 서둘러야만 하는 상황에 처해 있습니다. 캘리포니아주는 2033년까지 완전한 단계적 폐지를 의무화하고 연간 누출률을 1%로 제한하고 있어, 자산 소유자들은 고가의 모니터링 시스템에 투자할 수밖에 없는 상황입니다. 뉴욕주와 매사추세츠주에서도 유사한 추세가 나타나고 있어, SF6에 의존하는 자산의 투자 기간이 단축되고 선진 지역에서의 조달량이 감소하고 있습니다. 이러한 중복되는 조치로 인해 육불화황 시장의 성장 전망은 1.8포인트 하향 조정되었습니다.
부문 분석
2025년, 전력 회사가 개폐 장치, 차단기, 가스 절연 송전선에서 입증된 절연 성능을 우선시한 결과, 전자 기술 등급 부문이 육불화황 시장 점유율의 60.72%를 차지했습니다. 기술 등급 SF6는 원자재 가격 동향에 연동되며, 변전소로 벌크 탱커를 통한 배송을 가능하게 하는 확립된 세계 유통 채널의 혜택을 받고 있습니다. 예측 기간 동안 개보수 프로젝트가 지속됨에 따라, 이 부문은 육불화황 시장 전체를 지탱하는 상당한 베이스로드 수요를 유지하고 있습니다.
초고순도 SF6는 절대 톤수로는 규모가 작지만, 첨단 반도체 및 액정 디스플레이(LCD) 제조 수요에 힘입어 제품 유형 중 가장 높은 연평균 성장률(CAGR, 4.71%)을 기록하며 성장할 것으로 예측됩니다. 불순물 농도를 10억 분의 1(ppb) 이하로 유지하려면 여러 정제 공정, 전용 실린더, 전용 공급망이 필요합니다. 이러한 생산 프로토콜을 습득한 공급업체는 더 높은 이익률을 확보하여 수량 감소를 상쇄할 뿐만 아니라, 환경 정책으로 인해 기존 전력 회사용 수요가 압박받는 상황에서 전략적인 리스크 헤지를 마련할 수 있습니다. 이 두 등급이 결합됨에 따라, 육불화황 시장은 범용 부문과 특수 부문 모두에 걸쳐 균형 잡힌 포트폴리오를 유지하게 될 것입니다.
지역별 분석
아시아태평양은 2025년에 47.82%의 점유율로 육불화황 시장을 독점했으며, 2031년까지 연평균 성장률(CAGR) 4.61%를 나타낼 것으로 예측됩니다. 중국의 송전망 사업자들은 사상 최대 규모의 재생에너지 발전 용량을 수용하기 위해 초고압 송전 회랑 전체에 소형 550kV 가스 절연 변전소를 설치하고 있으며, 이러한 전략은 향후 수십 년에 걸쳐 SF6 수요를 확고히 하고 있습니다. 인도의 주간 송전망 강화 프로그램에서는 급속히 도시화가 진행되는 부하 중심 지역의 신뢰성을 향상시키기 위해 SF6 링 메인 유닛이 채택되고 있습니다. 한국의 반도체 산업 확대는 해당 지역의 초고순도 SF6 수요를 끌어올리고 있는 반면, 일본은 SF6 프리 솔루션의 기술 실증 거점으로서의 위상을 확립하여, 기존 기술과 신기술이 융합된 이중 시장 구조가 형성되고 있습니다.
북미에서는 전력 회사가 노후화된 설비의 교체와 규제 준수의 균형을 모색하는 가운데, SF6 소비량은 한 자릿수 중반대의 성장세를 보이고 있습니다. 캘리포니아주의 2033년까지의 단계적 폐지 및 누출 상한 규제로 인해 모니터링 및 회수 시스템의 조기 도입이 시급한 상황이지만, 다른 주의 송전망 운영자들은 실용화된 대체품이 여전히 부족한 고전압 등급에서 계속해서 SF6 사용을 지정하고 있습니다. 복원력 향상을 위한 연방 정부의 인프라 자금 지원으로 전반적인 수요는 안정적이지만, 재활용률 상승이 신규 공급 수요를 억제하는 데 기여하고 있습니다. 캐나다와 캘리포니아주의 배출권 거래제(Cap-and-Trade) 제도의 연계로 국경을 넘는 정책의 일관성이 촉진되고 있으며, 캐나다의 전력 사업자들은 기존 설비용 중요한 예비 부품을 확보하는 한편, SF6가 없는 시범 사업을 검토하도록 장려받고 있습니다.
유럽은 가장 엄격한 정책 환경에 직면해 있습니다. 개정된 F가스 규제에 따라 2026년부터는 중전압 SF6 개폐 장치, 2032년부터는 고전압 설비의 신규 도입이 금지됩니다. 독일과 북유럽 국가들의 사업자를 필두로 한 송전계통 운영 사업자들은 진공 차단기나 클린 에어 기술의 실증 운영을 추진하고 있지만, 기존 설비의 확충에 있어서는 여전히 SF6에 의존하고 있습니다. 영국은 EU 규정을 준수하고 있으며, 개조 프로그램에 소요되는 규정 준수 비용은 1억-2억 8,000만 파운드로 추정됩니다. 설비 교체 주기가 느린 남유럽 및 동유럽의 전력 회사는 비용 압박에 직면해 있으며, 제한된 SF6 조달 기간이 2020년대 중반 이후까지 연장될 가능성이 있습니다. 라틴아메리카, 중동 및 아프리카는 기초적인 전기화 및 산업 역량 확대에 따라 규모는 작지만 여전히 고성장 지역으로 자리 잡고 있어, 육불화황(SF6) 시장에 미래 성장의 여지를 제공합니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, sulfur hexafluoride market size in 2026 is estimated at 83.98 kilotons, growing from 2025 value of 80.80 kilotons with 2031 projections showing 101.84 kilotons, growing at 3.94% CAGR over 2026-2031.
This report is Segmented by Product Type (Electronic/Technical Grade, Ultra-High Purity Grade), Application (Power and Energy, Electronics, Metal Manufacturing, Medical, Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (tons).
Global Sulfur Hexafluoride Market Trends and Insights
Grid-upgrade demand in emerging economies
China's SF6 emissions climbed from 2.6 Gg in 2011 to 5.1 Gg in 2021 as transmission developers installed compact gas-insulated substations to keep pace with record-setting grid expansions. India has earmarked INR 2,000 crore for network modernization that specifies SF6 switchgear to secure voltage stability during rapid urbanization. Because typical substation assets remain in service for 25 to 50 years, every installation decision effectively locks in future sulfur hexafluoride market demand. Gas-insulated stations can be energized 45% faster than air-insulated yards, a time saving valued by utilities racing to alleviate congestion. As a result, the sulfur hexafluoride market continues to deepen its presence across Asia-Pacific despite intensifying environmental policy debates.
Semiconductor and LCD plasma-etching growth
Korea's USD 471 billion semiconductor cluster, slated to add 16 fabs by 2047, exemplifies capital flows that elevate consumption of ultra-high-purity SF6. In deep-trench silicon etching, SF6 generates fluorine radicals that remove material up to 100 times faster than rival gases, ensuring throughput targets for 3 nm and below nodes. Although abatement systems curb direct emissions, a portion of feedstock still reaches the atmosphere, prompting regulatory scrutiny as fabrication capacity scales. Even so, process engineers continue to specify SF6 until drop-in alternatives can replicate its etching precision, keeping the sulfur hexafluoride market firmly embedded in advanced manufacturing value chains.
Stringent global-warming regulations
The European Union has banned SF6 in medium-voltage switchgear from 2026 and in high-voltage gear from 2032, forcing utilities to accelerate retrofit plans. California mandates complete phase-out by 2033 and restricts annual leak rates to 1%, compelling asset owners to fund costly monitoring systems. Similar trajectories in New York and Massachusetts compress investment horizons for SF6-dependent assets, dampening procurement volumes in developed regions. These overlapping policies subtract 1.8 percentage points from the sulfur hexafluoride market growth outlook.
Other drivers and restraints analyzed in the detailed report include:
- Renewable-integrated HVDC and offshore substations
- Magnesium die-casting oxidation prevention
- Price volatility and export quotas
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The electronic/technical-grade segment accounted for 60.72% of sulfur hexafluoride market share in 2025 as utilities prioritize proven insulation performance for switchgear, breakers, and gas-insulated lines. Technical-grade SF6 follows commodity price dynamics and benefits from established global distribution channels that permit bulk tanker deliveries to substation sites. Because retrofit projects continue through the forecast period, the segment maintains a sizable base-load volume that anchors the overall sulfur hexafluoride market.
Ultra-high-purity SF6, while representing a smaller absolute tonnage, is forecast to expand at 4.71% CAGR, the fastest among product types, propelled by advanced semiconductor and LCD fabrication. Maintaining contaminant thresholds below parts-per-billion requires multiple purification stages, specialised cylinders, and dedicated supply chains. Suppliers that master these production protocols secure higher margins, offsetting lower volumes and providing a strategic hedge as environmental policy squeezes traditional utility demand. Collectively, the two grade tiers ensure that the sulfur hexafluoride market retains a balanced portfolio across commodity and specialty niches.
Complete Report Scope:
- By Product Type
- Electronic / Technical Grade
- Ultra-High Purity Grade
- By Application
- Power and Energy
- Electronics
- Metal Manufacturing
- Medical
- Other Applications (Window Insulation, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominated the sulfur hexafluoride market with 47.82% share in 2025 and is projected to log a 4.61% CAGR through 2031. China's grid operators are installing compact 550 kV gas-insulated substations across ultrahigh-voltage corridors to accommodate record renewable capacity, a strategy that cements multi-decade SF6 demand. India's program to reinforce inter-state transmission uses SF6 ring-main units to improve reliability in rapidly urbanizing load centers. South Korea's semiconductor expansion amplifies regional ultra-high-purity volumes, while Japan positions itself as a technology demonstrator for SF6-free solutions, creating a dual-track landscape that blends incumbent and emerging technologies.
North America shows mid-single-digit consumption growth as utilities balance ageing-asset replacements with regulatory compliance. California's 2033 phase-out and leak caps compel early adoption of monitoring and capture systems, but grid operators in other states continue to specify SF6 in high-voltage classes where field-ready alternatives remain scarce. Federal infrastructure funding for resilience upgrades keeps overall demand stable, although rising recycling rates help temper fresh supply needs. Canada's linkages to California's cap-and-trade system drive cross-border policy alignment, nudging Canadian utilities to explore SF6-free pilots while maintaining critical spares for legacy equipment.
Europe faces the most stringent policy environment: the revised F-gas regulation bans new medium-voltage SF6 switchgear from 2026 and high-voltage installations from 2032. Transmission system operators, led by entities in Germany and the Nordics, are piloting vacuum-interrupter and clean-air technologies but still rely on SF6 for brownfield extensions. The United Kingdom mirrors EU limits, adding compliance costs estimated at GBP 100-280 million for retrofit programs. Southern and Eastern European utilities with slower replacement cycles face cost pressures, potentially extending limited SF6 procurement beyond mid-decade. Latin America, the Middle East, and Africa collectively remain smaller yet high-growth territories as they expand base-line electrification and industrial capacity, offering future upside for the sulfur hexafluoride market.
- Advanced Specialty Gases
- Air Liquide
- Air Products and Chemicals, Inc.
- AIR WATER INC
- Airgas, Inc.
- Concorde Specialty Gases, Inc.,
- Fujian Yongjing Technology Co., Ltd
- Guangdong Huate Gas Co., Ltd.
- Honeywell International Inc.
- Kanto Denka Kogyo Co., Ltd.
- Linde plc
- Matheson Tri-Gas, Inc.
- Messer SE & Co. KGaA
- Resonac Holdings Corporation
- Solvay S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Grid-Upgrade Demand in Emerging Economies
- 4.2.2 Semiconductor and LCD Plasma-Etching Growth
- 4.2.3 Renewable-Integrated HVDC and Offshore Substations
- 4.2.4 Magnesium Die-Casting Oxidation Prevention
- 4.2.5 Increasing Demand in the Medical Sector
- 4.3 Market Restraints
- 4.3.1 Stringent Global-Warming Regulations
- 4.3.2 Price Volatility and Export Quotas
- 4.3.3 Potential Semiconductor-Process Bans
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Electronic / Technical Grade
- 5.1.2 Ultra-High Purity Grade
- 5.2 By Application
- 5.2.1 Power and Energy
- 5.2.2 Electronics
- 5.2.3 Metal Manufacturing
- 5.2.4 Medical
- 5.2.5 Other Applications (Window Insulation, etc.)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 Japan
- 5.3.1.3 India
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 NORDIC Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Advanced Specialty Gases
- 6.4.2 Air Liquide
- 6.4.3 Air Products and Chemicals, Inc.
- 6.4.4 AIR WATER INC
- 6.4.5 Airgas, Inc.
- 6.4.6 Concorde Specialty Gases, Inc.,
- 6.4.7 Fujian Yongjing Technology Co., Ltd
- 6.4.8 Guangdong Huate Gas Co., Ltd.
- 6.4.9 Honeywell International Inc.
- 6.4.10 Kanto Denka Kogyo Co., Ltd.
- 6.4.11 Linde plc
- 6.4.12 Matheson Tri-Gas, Inc.
- 6.4.13 Messer SE & Co. KGaA
- 6.4.14 Resonac Holdings Corporation
- 6.4.15 Solvay S.A.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


