

|
시장보고서
상품코드
2122986
데이터센터 침지 냉각 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Data Center Immersion Cooling - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
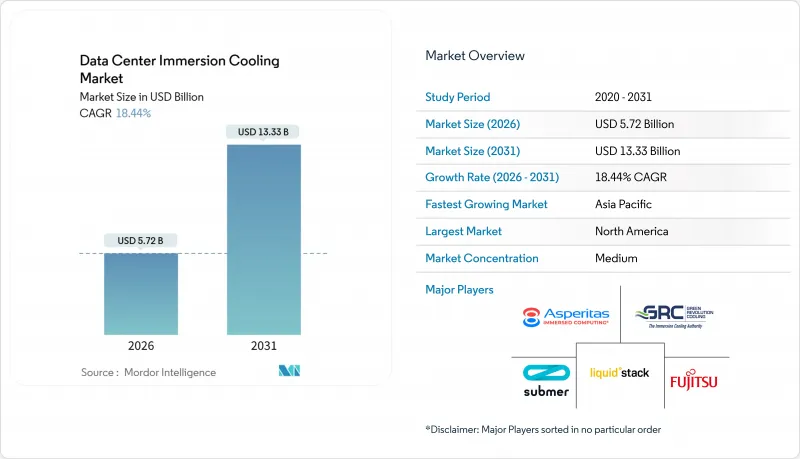
에 의하면, 데이터센터 침지 냉각 시장 규모는 2026년에 57억 2,000만 달러로 추정되고 있어 예측 기간(2026-2031년)에서 CAGR 18.44%로 확대되어 2031년에는 133억 3,000만 달러에 이를 전망입니다.
본 보고서는 유형별(단상 침지 냉각 시스템, 이상 침지 냉각 시스템), 냉각액별(광물유, 기타),용도별(HPC, 기타), 티어 유형별(Tier 1·2, 기타), 데이터센터 규모별(소규모 데이터센터, 기타), 데이터센터 유형별(코로케이션 데이터센터, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 데이터센터 침지 냉각 시장 동향 및 인사이트
하이퍼스케일 데이터센터의 급증
각 사업자들은 대규모 재생에너지를 조달할 수 있고, 거액의 자본 프로젝트 상각이 가능한 기가와트급 캠퍼스로 컴퓨팅 자원을 집약하고 있습니다. Meta는 2025년에 한 곳당 평균 100메가와트를 초과하는 21곳의 이러한 사이트를 운영할 예정이며, 해당 회사의 제출 서류에 따르면 바닥 타일당 서버 밀도 향상은 침지 냉각 덕분인 것으로 나타났습니다. Microsoft는 2025년에 자사 인프라의 15%에서 액체 냉각 도입률을 높이고, 2028년까지 40%를 목표로 하고 있으며, 온대 지역에서 전력 사용 효율(PUE)을 1.15 이하로 억제하기 위한 방안으로 이를 제시하고 있습니다. 구글은 칩당 350와트를 초과하는 텐서 처리 장치(TPU) 클러스터를 수용하기 위해 8개의 기존 홀 개보수 작업에 착수했습니다. 각 프로젝트의 건설 비용은 5억 달러를 초과하지만, 침지 냉각으로의 전환을 통해 연산 유닛당 토지, 기계, 팬에 의한 에너지 소비를 줄일 수 있습니다.
AI·ML 워크로드로 인한 랙당 전력 밀도 상승
현재 대규모 언어 모델 훈련에는 80-120kW를 소비하는 랙이 사용되고 있습니다. NVIDIA의 H100은 1대당 700와트에 달하므로, 42U 캐비닛 내의 듀얼 GPU 서버 8대로 100kW를 초과합니다. 인텔의 Gaudi 3 가속기는 600와트이며, 1,000개 이상의 칩을 사용하는 고객 클러스터의 경우 냉수 루프 확장을 피하기 위해 침지 냉각이 지정되어 있습니다. AMD의 MI300X는 최대 750와트이지만, 총 소유 비용(TCO) 추산에 따르면 랙 밀도가 60kW를 초과할 경우 5년 동안 20%-30%의 비용 절감이 예상됩니다. 공기의 열용량이 낮기 때문에 이 부하를 비용 효율적으로 이동시킬 수는 없지만, 액체의 열전도율은 공기의 25배이므로 성능 여유를 유지하면서 시설 확장을 미룰 수 있습니다.
막대한 초기 설비 투자(CAPEX) 및 시설 재설계 비용
침지 탱크, 매니폴드 배관, 구조 보강으로 인해 1메가와트 블록의 턴키 비용은 250만-350만 달러로, 공랭식 방식의 약 2배가 됩니다. 기존 설비의 개보수 프로젝트에서는 바닥 보강, 클래스 K 소화 시스템 업그레이드, 직원 재교육으로 인해 비용이 15%-25% 추가됩니다. 지역 전력 가격이 kW시당 0.10달러를 초과하지 않거나 열 구매 계약이 체결되지 않는 한, 투자 회수 기간은 4년에서 6년에 이릅니다. 이익률이 낮은 코로케이션 사업자들은 도입을 주저하고 있으며, 소규모 기업들은 재정적 여유가 없어 보급 속도가 둔화되고 있습니다.
부문 분석
2026년부터 2031년까지 2상 아키텍처는 연평균 성장률(CAGR) 19.42%로 성장하여 데이터센터 침지 냉각 시장 전체를 능가하는 규모가 될 전망입니다. 2025년 시점에서는 범용 서버와의 호환성과 유체의 변동성이 최소화되어, 단상 시스템이 여전히 데이터센터 침지 냉각 시장 점유율의 62.43%를 차지하고 있었습니다. LiquidStack은 잠열을 활용하여 펌프를 완전히 배제하고 보조 부하를 40% 절감한 유럽의 AI 연구소 사례를 보고하고 있습니다. 암호화폐 및 일반적인 HPC 워크로드에서는 여전히 단상 방식이 선호되지만, 100kW급 랙을 목표로 하는 사업자에게는 대규모 수동 방열을 실현하는 유일한 수단으로서 2상 방식이 주목받고 있습니다.
펌프리스 운전으로 총 전력 소비가 감소하고, 중력에 의한 응축수 회류로 유지보수가 간소화됩니다. 그러나 하이드로플루오로에테르 계열 유체에 대한 의존은 비용을 높게 유지하게 하며, 구매자를 PFAS 규제의 위험에 노출시키고 있습니다. 각 제조업체는 합성 탄화수소 및 낮은 GWP(지구 온난화 지수) 화학 물질의 인증 획득을 서두르고 있으며, 예측 기간 동안 2상 시스템의 가격 프리미엄은 축소될 전망입니다. 상호 운용성 노력에 힘입어 단일 홀 내 혼합 상 도입이 현실화될 가능성도 있으며, 이를 통해 사업자는 다양한 열 관리 도구를 활용할 수 있게 될 것으로 보입니다.
2025년에는 리터당 3-5달러의 가격 책정과 성숙한 공급망 덕분에 광물유가 총 사용량의 48.65%를 차지했습니다. 그러나 유럽과 북미의 사업자들이 탈탄소화를 추진함에 따라, 바이오 유래 대안은 연평균 성장률(CAGR) 19.56%로 성장할 전망입니다. Cargill의 에스테르계 유체는 0.17W·m·K의 열전도율(광물유 수준의 85%)을 실현하면서 ISO 14001 및 Scope 3 산정 요건을 충족합니다. 불소계 냉각액은 여전히 2상 사이클을 가능하게 하여 22%의 점유율을 유지하고 있지만, 3M의 철수와 Chemours의 배합 변경은 공급 및 규정 준수상의 위험을 부각시키고 있습니다.
Shell의 합성 탄화수소계 제품은 0.16W·m·K의 열전도율과 265°C의 인화점을 겸비하고 있어 대규모 소화 설비가 필요하지 않습니다. 탈이온수는 완전 침지 매체는 아니지만, 하이퍼스케일러의 직접 투 칩 루프에서 8%의 시장 점유율을 확보했습니다. 앞으로 유체 선택은 현지 규제, 폐열 활용 목표, 보험사의 의향에 좌우될 것이며, 사업자들은 리스크 헤지를 위해 화학물질 포트폴리오를 다각화할 가능성이 높습니다.
지역별 분석
북미는 버지니아주, 오리건주, 텍사스주의 하이퍼스케일 기업 투자를 배경으로 2025년에도 40.32%의 점유율을 유지했습니다. 마이크로소프트는 드라이 사이드에서 직접 공기 이용이 가능한 온화한 기후를 이유로, 2028년까지 미국 내 액체 냉각 시스템 구축에 100억 달러를 투자할 것이라고 밝혔습니다. 메타의 프리네빌 캠퍼스에서는 1만 5,000대의 침지형 서버를 가동하여 연간 전력 사용 효율(PUE) 1.06을 기록, 세계 최고 수준의 효율을 보여주었습니다. 캐나다는 퀘벡주와 브리티시컬럼비아주의 수력 발전 덕분에 해당 지역 총 전력 용량의 8%를 차지한 반면, 멕시코는 니어쇼어 제조 거점을 위한 수요로 인해 4%를 차지했습니다.
아시아태평양은 중국의 국가 주도의 AI 추진과 20억 달러 규모의 인도 인센티브 정책에 힘입어 2031년까지 연평균 성장률(CAGR) 19.94%를 나타낼 것으로 예측됩니다. 알리바바와 텐센트는 이미 항저우와 선전에서 침지형 데이터센터를 운영하고 있으며, 각각 냉각 에너지 절감률이 30% 이상의다고 주장하고 있습니다. 일본은 ‘그린 트랜스포메이션’ 프로그램에 따른 보조금에 힘입어 2025년에는 해당 지역 매출의 18%를 차지했습니다. 나머지는 한국, 호주, 뉴질랜드가 나눠 가지고 있으며, 각국은 국내 수요를 위한 저지연 서비스를 목표로 하고 있습니다.
유럽은 2025년, 효율화 의무와 열 회수에 대한 인센티브에 힘입어 전 세계 시장의 28%를 차지했습니다. 독일은 지역 난방용으로 5억 유로의 보조금 패키지를 투입해 프랑크푸르트와 뮌헨의 사업자를 지원한 반면, 네덜란드는 암스테르담 근교의 재생에너지망을 활용했습니다. 영국은 전력 사용 효율(PUE) 1.3이라는 기준을 충족하기 위해 런던 도크랜즈와 맨체스터에 수냉식 시설을 추가했습니다. 중동의 건설은 전 세계 총 용량의 불과 6%에 불과하지만, 기온 45℃의 사막 지대에서 침지 냉각의 열적 우위를 두드러지게 보여주고 있으며, 2026년 말 완공 예정인 아부다비의 150메가와트 규모 프로젝트가 그 대표적인 예입니다. 남미는 3%를 차지하고 있으며, 브라질의 금융 부문이 주도적인 역할을 하고 있습니다. 한편, 아프리카는 2%에 그치고 있어 송전망의 안정성이 과제로 대두되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the data center immersion cooling market size is estimated at USD 5.72 billion in 2026, and is expected to reach USD 13.33 billion by 2031, at a CAGR of 18.44% during the forecast period (2026-2031).
This report is Segmented by Type (Single-Phase Immersion Cooling System, and Two-Phase Immersion Cooling System), Cooling Fluid (Mineral Oil, and More), Application (HPC and More), Tier Type (Tier 1 and 2, and More), Data Center Size (Small Data Center, and More), Data Center Type (Colocation Data Center, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Global Data Center Immersion Cooling Market Trends and Insights
Proliferation of Hyperscale Data Centers
Operators are consolidating compute into gigawatt-class campuses that can negotiate renewable power at scale and amortize large capital projects. Meta ran 21 such sites in 2025 averaging more than 100 megawatts each, and its filings credit immersion cooling for raising server density per floor tile. Microsoft lifted liquid penetration to 15% of its fleet during 2025 and targets 40% by 2028, citing a route to sub-1.15 power usage effectiveness in temperate zones. Google began retrofitting eight legacy halls to house Tensor Processing Unit clusters that top 350 watts per chip. With each build exceeding USD 500 million, shifting to immersion lowers land, mechanical, and fan energy per compute unit.
Rising Rack Power Densities From AI and ML Workloads
Large language model training now fills racks that draw 80-120 kilowatts. NVIDIA's H100 hits 700 watts per device, so eight dual-GPU servers inside a 42U cabinet breach 100 kilowatts. Intel's Gaudi 3 accelerator checks in at 600 watts, and customer clusters above 1,000 chips specify immersion to avoid expanding chilled-water loops. AMD's MI300X peaks at 750 watts, with total cost of ownership modeling showing 20%-30% savings over five years once rack densities cross 60 kilowatts. Air's low heat capacity cannot cost-effectively move that load, whereas liquid's 25-times-higher thermal conductivity preserves performance margins and delays building expansions.
High Upfront CAPEX and Facility-Redesign Costs
Immersion tanks, manifold plumbing, and structural reinforcements push turnkey expense for a 1 megawatt block to USD 2.5-3.5 million, roughly double air cooling levels. Retrofit projects add 15%-25% due to floor strengthening, Class K suppression upgrades, and staff retraining. Payback stretches four to six years unless local power prices exceed USD 0.10 per kilowatt-hour or heat-offtake deals materialize. Colocation operators running thin margins hesitate, while smaller enterprises lack balance-sheet capacity, slowing broad uptake.
Other drivers and restraints analyzed in the detailed report include:
- Superior Energy-Efficiency and PUE Gains Over Air Cooling
- Regulatory Push Toward PFAS-Free Bio-Based Coolants
- Fragmented Standards and Vendor Interoperability Gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Two-phase architectures will outgrow the wider data center immersion cooling market at 19.42% CAGR between 2026 and 2031. In 2025 single-phase systems still commanded a 62.43% data center immersion cooling market share thanks to compatibility with commodity servers and minimal fluid volatility. LiquidStack documented a European AI lab that removed pumps altogether by exploiting latent heat, cutting auxiliary loads 40%. Single-phase remains preferred for cryptocurrency and general HPC workloads, yet operators chasing 100 kilowatt racks view two-phase as the only route to passive rejection at scale.
Pumpless operation lowers total energy draw, and gravity-fed condensate return simplifies maintenance. However, reliance on hydrofluoroether fluids keeps costs high and exposes buyers to PFAS restrictions. Manufacturers are racing to qualify synthetic hydrocarbon and low-GWP chemistries, suggesting the two-phase premium will narrow over the forecast horizon. Interoperability efforts may also make mixed-phase deployments practical inside a single hall, giving operators a menu of thermal tools.
Mineral oil supplied 48.65% of liters in 2025 because of USD 3-5 per liter pricing and mature supply chains. Yet bio-based options are set for a 19.56% CAGR as operators in Europe and North America look to decarbonize. Cargill's ester delivers 0.17 W-m-K conductivity, 85% of oil levels, but satisfies ISO 14001 and Scope 3 accounting. Fluorocarbon fluids still enable two-phase cycles and held 22% share, though 3M's exit and Chemours' reformulation underscore supply and compliance risk.
Shell's synthetic hydrocarbon variant blended 0.16 W-m-K performance with a 265 °C flash point, removing the need for extensive fire suppression. De-ionized water, while not a full-immersion medium, earned 8% share inside direct-to-chip loops at hyperscalers. Going forward, fluid choice will hinge on local regulation, waste-heat goals, and insurer preferences, with operators likely to diversify chemistry portfolios to hedge risk.
Complete Report Scope:
- By Type
- Single-Phase Immersion Cooling System
- Two-Phase Immersion Cooling System
- By Cooling Fluid
- Mineral Oil
- De-Ionized Water
- Fluorocarbon-Based Fluids
- Synthetic Hydrocarbon Fluids
- Bio-Based Fluids
- By Application
- High-Performance Computing (HPC)
- Edge Computing
- Artificial Intelligence and Machine Learning
- Cloud and Hyperscale Applications
- Cryptocurrency Mining
- Other Applications
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small Data Center
- Medium Data Center
- Large Data Center
- Hyperscale Data Center
- By Data Center Type
- Colocation Data Center
- Hyperscalers Data Center/CSPs
- Enterprise and Edge Data Center
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained a 40.32% share in 2025 on the strength of hyperscale spend in Virginia, Oregon, and Texas. Microsoft earmarked USD 10 billion for U.S. liquid builds through 2028, citing temperate climates that allow direct air economization on the dry side. Meta's Prineville campus operated 15 000 submerged servers and posted a 1.06 annual power usage effectiveness, among the best globally. Canada gathered 8% of regional megawatts thanks to hydroelectric power in Quebec and British Columbia, while Mexico captured 4% serving nearshore manufacturing nodes.
Asia-Pacific is projected to grow at a 19.94% CAGR to 2031, led by China's sovereign AI push and India's incentive scheme worth USD 2 billion. Alibaba and Tencent already run immersion halls in Hangzhou and Shenzhen, each claiming cooling energy cuts above 30%. Japan contributed 18% of regional revenue in 2025, supported by subsidies under the Green Transformation program. South Korea, Australia, and New Zealand share the remainder, each targeting low-latency service for local consumption.
Europe controlled 28% of the global tally in 2025, propelled by efficiency mandates and heat-recovery incentives. Germany's EUR 500 million grant package for district heating tapped operators in Frankfurt and Munich, while the Netherlands leveraged renewable grids near Amsterdam. The United Kingdom added liquid rooms in London Docklands and Manchester to meet a 1.3 power usage effectiveness threshold. Middle East builds, though only 6% of world capacity, highlight immersion's thermal edge in 45 °C deserts, exemplified by a 150 megawatt Abu Dhabi project set to complete in late 2026. South America sits at 3%, dominated by Brazil's finance sector, and Africa at 2%, held back by grid stability.
- Fujitsu Limited
- Green Revolution Cooling (GRC) Inc.
- Submer Technologies SL
- LiquidStack Inc.
- Asperitas
- LiquidCool Solutions
- Midas Green Technologies
- Iceotope Technologies Ltd.
- Wiwynn Corporation
- DCX Ltd.
- Dell Technologies
- Intel Corporation
- Schneider Electric SE
- Vertiv Holdings Co.
- NVIDIA Corporation
- Asetek A/S
- Shell plc (Immersion Cooling Fluids)
- Cargill Inc. (NatureCool)
- 3M Company
- Chemours Company
- Molex LLC
- Hypertec Group
- Alibaba Cloud
- Tencent Cloud
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Hyperscale Data Centers
- 4.2.2 Rising Rack-Power Densities from AI and ML Workloads
- 4.2.3 Superior Energy-Efficiency and PUE Gains over Air Cooling
- 4.2.4 Regulatory Push toward PFAS-Free, Bio-Based Coolants
- 4.2.5 Monetization of Waste-Heat for District Heating Networks
- 4.2.6 AI-Assisted Discovery of Next-Generation Dielectric Fluids
- 4.3 Market Restraints
- 4.3.1 High Upfront CAPEX and Facility-Redesign Costs
- 4.3.2 Fragmented Standards and Vendor Interoperability Gaps
- 4.3.3 Supply-Chain Risk for Fluorinated Dielectrics
- 4.3.4 Limited Field Data on Long-Term Fluid-Hardware Compatibility
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.6.1 Evolution of Data-Center Cooling
- 4.6.2 Energy-Consumption and Compute-Density Metrics
- 4.6.3 Teardown of Fluids, Processors, GPUs, Racks and Infrastructure
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Degree of Competition
- 4.7.5 Threat of Substitutes
- 4.8 Assesment of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Single-Phase Immersion Cooling System
- 5.1.2 Two-Phase Immersion Cooling System
- 5.2 By Cooling Fluid
- 5.2.1 Mineral Oil
- 5.2.2 De-Ionized Water
- 5.2.3 Fluorocarbon-Based Fluids
- 5.2.4 Synthetic Hydrocarbon Fluids
- 5.2.5 Bio-Based Fluids
- 5.3 By Application
- 5.3.1 High-Performance Computing (HPC)
- 5.3.2 Edge Computing
- 5.3.3 Artificial Intelligence and Machine Learning
- 5.3.4 Cloud and Hyperscale Applications
- 5.3.5 Cryptocurrency Mining
- 5.3.6 Other Applications
- 5.4 By Tier Type
- 5.4.1 Tier 1 and 2
- 5.4.2 Tier 3
- 5.4.3 Tier 4
- 5.5 By Data Center Size
- 5.5.1 Small Data Center
- 5.5.2 Medium Data Center
- 5.5.3 Large Data Center
- 5.5.4 Hyperscale Data Center
- 5.6 By Data Center Type
- 5.6.1 Colocation Data Center
- 5.6.2 Hyperscalers Data Center/CSPs
- 5.6.3 Enterprise and Edge Data Center
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Netherlands
- 5.7.3.5 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Australia and New Zealand
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 United Arab Emirates
- 5.7.5.1.2 Saudi Arabia
- 5.7.5.1.3 Turkey
- 5.7.5.1.4 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Egypt
- 5.7.5.2.3 Nigeria
- 5.7.5.2.4 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Fujitsu Limited
- 6.4.2 Green Revolution Cooling (GRC) Inc.
- 6.4.3 Submer Technologies SL
- 6.4.4 LiquidStack Inc.
- 6.4.5 Asperitas
- 6.4.6 LiquidCool Solutions
- 6.4.7 Midas Green Technologies
- 6.4.8 Iceotope Technologies Ltd.
- 6.4.9 Wiwynn Corporation
- 6.4.10 DCX Ltd.
- 6.4.11 Dell Technologies
- 6.4.12 Intel Corporation
- 6.4.13 Schneider Electric SE
- 6.4.14 Vertiv Holdings Co.
- 6.4.15 NVIDIA Corporation
- 6.4.16 Asetek A/S
- 6.4.17 Shell plc (Immersion Cooling Fluids)
- 6.4.18 Cargill Inc. (NatureCool)
- 6.4.19 3M Company
- 6.4.20 Chemours Company
- 6.4.21 Molex LLC
- 6.4.22 Hypertec Group
- 6.4.23 Alibaba Cloud
- 6.4.24 Tencent Cloud
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


