|
시장보고서
상품코드
2123008
NaaS(Network as a Service) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Network As A Service - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
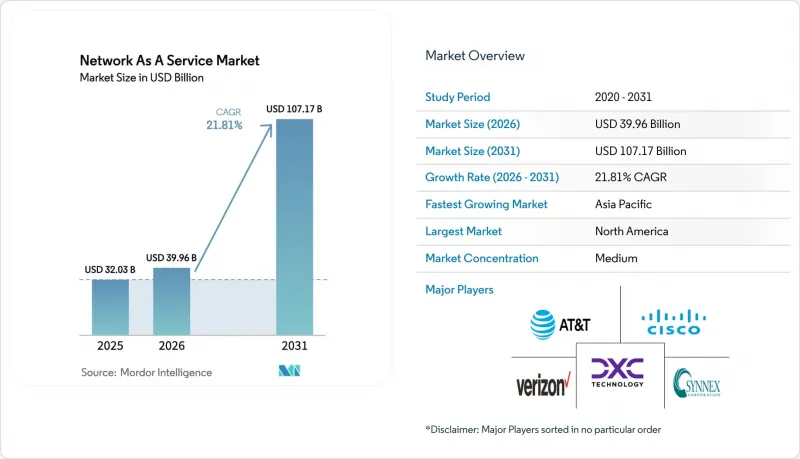
에 의하면, NaaS(Network as a Service)(NAS) 시장 규모는 2025년에 320억 3,000만 달러로 평가되었고, 2026년 399억 6,000만 달러로 추정되고, 2031년까지 1,071억 7,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 21.81%를 나타낼 전망입니다.
본 보고서는 유형별(LAN-as-a-Service 등), 용도별(가상 CPE, 온디맨드 대역폭 등), 조직 규모별(대기업 및 중소기업), 산업별(IT 및 통신 등), 도입 모델별(퍼블릭 클라우드 기반 NaaS 등), 지역별(북미, 남미 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 NaaS(Network as a Service) 시장 동향 및 인사이트
클라우드 우선 네트워크 혁신 로드맵
하이브리드 워크로드가 IT 지출의 대부분을 차지했으며, 하이퍼스케일 클라우드로의 연결은 급증하고 있습니다. Azure ExpressRoute와 AWS Direct Connect는 2024년에 각각 전년 대비 40%의 연결 증가를 기록했는데, 이는 핵심 용도가 기업 데이터센터 외부에 배치되는 사례가 증가하고 있음을 보여줍니다. 기업들은 정적인 MPLS 회선을 SaaS 지연을 30-50밀리초 단축하는 프로그래밍 가능한 오버레이로 대체하고 있습니다. 패킷 손실률을 0.01% 이상 허용할 수 없는 금융 기관들이 실시간 거래를 보호하기 위해 이러한 도입을 주도하고 있습니다. API 기반 프로비저닝에 정통한 엔지니어 부족으로 인해, 사용자 친화적인 포털을 통해 복잡성을 숨기는 완전 관리형 솔루션에 대한 수요가 증가하고 있습니다. 그 결과, 공급업체들은 오케스트레이션 API를 통합하여 기업이 DevOps 파이프라인 내에서 대역폭을 ‘코드’로 스크립팅할 수 있도록 하고 있습니다.
CapEx에서 OpEx로의 전환 및 구독형 예산 편성 압력
개정된 IFRS 16 및 ASC 842 규정에 따라, 소유 하드웨어는 감가상각 대상인 사용권 자산으로 재정의되어 자본이 장기적인 갱신 주기에 묶이게 되었습니다. 구독형 NaaS는 고정 투자를 유연한 경비로 전환하는 것으로, EBITDA를 최적화하는 사모펀드 포트폴리오에서 높이 평가받는 구조입니다. 제조 기업 그룹은 이 모델을 활용하여 설비를 상각하지 않고 경기 침체기에 생산 능력을 조절하고 있습니다. 제로베이스 예산 편성으로 인해 IT 리더는 매년 지출의 정당성을 설명해야만 하지만, 종량제 통신 서비스는 수년에 걸친 하드웨어 상각보다 이 장벽을 더 원활하게 극복할 수 있습니다. 이러한 변화로 인해 벤더 간 경쟁의 초점은 하드웨어 사양에서 서비스 수준의 품질로 옮겨가며, 보안과 가시성을 단일 청구서에 통합하려는 동기가 생겨나고 있습니다.
뿌리 깊은 데이터 주권 및 데이터 소재지 관련 규정 준수 장벽
GDPR(EU 개인정보보호규정), 중국의 사이버 보안법, 그리고 인도에서 곧 시행될 데이터 보호 법안은 공급자에게 각 관할 구역별로 별도의 제어 계층을 구축할 것을 의무화하고 있습니다. 인프라의 중복 구축은 세계 확장을 세분화하고, 사이트별 비용을 상승시키며, 규모의 경제를 저해합니다. 또한, 슈렘스 II 판결은 EU에서 미국으로의 개인 데이터 이전을 더욱 제한하고 있으며, 많은 구매자가 위험이 높다고 간주하는 계약 조항을 의무화하고 있습니다. 바젤 III에서는 모든 호스팅 지역에 걸친 복원력 테스트가 의무화되어 있어, 금융 기관은 더욱 복잡한 과제에 직면해 있습니다. 제어 플레인이 중앙 콘솔에서 분산된 구역을 통합적으로 관리할 수 없는 경우, 기업은 하이브리드 모델을 도입하게 되지만, 이로 인해 NaaS(Network as a Service) 시장의 가치 제안이 훼손됩니다.
부문 분석
2025년, WAN-as-a-Service는 매출의 61.50%를 차지하며 NaaS(Network as a Service) 시장에서 입지를 공고히 했습니다. 50개 이상의 지사를 보유한 다국적 기업은 MPLS 회선을 SD-WAN 오버레이로 대체함으로써 즉각적인 비용 절감을 실현할 수 있으며, 그 결과 메가비트당 비용이 60% 절감됩니다. 컨트롤러에 내장된 AI 엔진은 트래픽을 가장 가까운 클라우드 온램프로 동적으로 유도하여 본사와 퍼블릭 클라우드 간의 파일 전송 시간을 단축합니다. 서비스 제공업체는 미리 프로비저닝된 제로 터치 엣지 디바이스를 활용하여 가치를 높이고, 도입 기간을 몇 주에서 몇 시간으로 단축하고 있습니다.
LAN-as-a-Service는 현재 규모는 작지만, Wi-Fi 7 액세스 포인트가 802.3bt의 전력 예산을 필요로 하기 때문에 2031년까지 연평균 성장률(CAGR) 23.01%로 성장하고 있습니다. 스위치의 전면적인 업그레이드에 자금을 투입할 수 없는 대학이나 병원은 전원, 분석 기능, 단말기 통합을 포함하는 ‘캠퍼스 스위치-어-서비스’ 번들로 전환하고 있습니다. 서비스 제공업체들은 텔레프레즌스 및 전자 차트를 위해 10기가 업링크를 보장하고 있으며, LAN 개편을 자본적 장벽이 아닌 운영비로 간주하고 있습니다. 캠퍼스 네트워크를 예측 가능한 구독 모델로 전환함으로써 공급업체는 잠재적인 구매자층을 확대하고, 이를 통해 ‘네트워크-어즈-어-서비스(Network As A Service)’ 시장 전체의 성장세를 가속화하고 있습니다.
2025년에는 가상 CPE가 용도 지출의 42.80%를 차지한 것으로 평가되었으며, 이는 라우터, 방화벽, WAN 최적화기가 x86 어플라이언스로 통합된 것을 반영합니다. 제로 터치 프로비저닝을 통해 전원을 켤 때 전체 소프트웨어 스택이 로드되므로, 지사에서는 하드웨어 설치 공간을 70% 절감하고 현장 서비스 요청을 대폭 줄일 수 있습니다. 온디맨드 대역폭은 경기장이나 컨퍼런스 센터에서의 일시적인 확장 수요를 충족시켜, ‘Network As A Service’ 시장의 핵심인 탄력성을 입증하고 있습니다.
'Network-as-API'는 아직 발전 단계에 있지만, 2031년까지 연평균 성장률(CAGR) 22.78%를 나타낼 것으로 예측됩니다. GSMA CAMARA 사양을 통해 개발자는 CI/CD 파이프라인에서 직접 서비스 품질(QoS) 및 디바이스 프로파일링을 프로그래밍할 수 있게 됩니다. 통신 사업자는 지오펜싱, 동적 SIM 활성화, 보장된 비트레이트 등의 5G 네트워크 기능을 공개함으로써, 기존의 연결 서비스를 넘어서는 새로운 수익원을 창출하고 있습니다. 기업의 DevOps 팀이 네트워크 호출을 용도 코드에 통합함에 따라, 가치는 물리적 링크에서 API 이용으로 이동하고 있으며, 더 광범위한 ‘Network As A Service’ 시장에서 새로운 비즈니스 기회가 열리고 있습니다.
지역별 분석
2025년, 북미는 Network As A Service 시장의 41.60%를 차지했습니다. 이는 포춘 500대 기업이 MPLS에서 SD-WAN으로 전환한 데 기인하며, 이로 인해 네트워크 지출이 40% 절감되었습니다. 고밀도 클라우드 상호 연결 패브릭 덕분에 미국 기업의 대부분은 최종 사용자로부터 20밀리초 이내의 거리에 있는 최소 3개의 가용성 영역에 액세스할 수 있습니다. 연방 정부의 조달 제도에 따라 임팩트 등급의 보안 승인을 보유한 공급업체로 비즈니스가 집중되고 있어, AT&T, Verizon, Lumen 등의 기존 기업들은 신규 진출기업이 존재함에도 불구하고 시장 점유율을 유지하고 있습니다. 월스트리트 거래를 위한 저지연 5G 슬라이스는 마이크로초 단위의 지터 제어에 기꺼이 비용을 지불하는 프리미엄 이용 사례를 보여줍니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 22.95%를 기록할 전망입니다. 인도의 ‘디지털 인디아(Digital India)’ 이니셔티브가 정부의 클라우드 도입을 주도하고 있으며, 국내 데이터 현지화 조항으로 인해 지역 제어 플레인에 대한 수요가 확보되고 있습니다. 차이나모바일과 화웨이는 산업 거점에서 프라이빗 5G를 구축하고 있는 반면, 일본에서는 지진 재해 이후 회복탄력성 강화 움직임이 기업의 멀티 리전 NaaS 아키텍처로의 전환을 뒷받침하고 있습니다. 한국의 스마트 시티용 센서에는 긴급 차량을 위한 우선 슬라이스가 요구되고 있으며, 호주의 광산에서는 200킬로미터에 달하는 아웃백 지형을 자율 주행 트럭이 주행하기 위해 프라이빗 5G가 활용되고 있습니다. 이러한 노력들이 맞물려, 세계에서 가장 빠르게 성장하는 경제권에서 ‘Network As A Service(NaaS)’ 시장이 확대되고 있습니다.
유럽에서는 GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정)에 따라 지역 내 데이터 처리가 의무화되어 있어 도입 상황이 분열되어 있습니다. 이로 인해 사이트별 비용이 증가하여 전 세계적인 최적화가 저해되고 있습니다. 독일과 프랑스의 주권 클라우드 구역은 규정 준수를 보장하지만, 인력 배치 및 감시에 대한 병행 투자도 필요합니다. 브렉시트 이후 영국의 규제 차이는 상황을 더욱 복잡하게 만들고 있으며, 벤더들은 인프라를 중복으로 구축할 수밖에 없는 실정입니다. 한편, 중동의 주권 펀드는 ‘비전 2030’ 목표 달성을 위해 하이퍼스케일 데이터센터 간의 상호 연결을 지원하고 있으며, 이로 인해 사우디아라비아와 UAE에서 수요가 촉진되고 있습니다. 아프리카에서는 남아프리카공화국과 이집트를 제외한 지역의 진전이 더딘데, 이는 모바일 우선형 인프라가 제한된 주파수 대역을 서로 차지하려고 경쟁하고 있기 때문입니다. 다만, Liquid Intelligent Technologies의 범아프리카 광섬유 프로젝트가 잠재적인 기업 수요를 개척하기 시작한 상황입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the network as a service market size was valued at USD 32.03 billion in 2025 and is estimated to grow from USD 39.96 billion in 2026 to reach USD 107.17 billion by 2031, at a CAGR of 21.81% during the forecast period (2026-2031).
This report is Segmented by Type (LAN-As-A-Service, and More), Application (Virtual CPE, Bandwidth-On-Demand, and More), Organisation Size (Large Enterprises and Small and Medium Enterprises), Industry Vertical (IT and Telecom and More), Deployment Model (Public-Cloud-Based NaaS, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Network As A Service Market Trends and Insights
Cloud-First Network Transformation Roadmaps
Hybrid workloads dominate IT spend, and connections to hyperscale cloud on-ramps are climbing sharply. Azure ExpressRoute and AWS Direct Connect each experienced 40% year-over-year connection growth in 2024, indicating that core applications are now increasingly residing outside of enterprise data centers. Firms are replacing static MPLS circuits with programmable overlays that cut latency for SaaS by 30-50 milliseconds. Financial institutions, which cannot tolerate packet loss above 0.01%, are leading the adoption to protect real-time trading. The shortage of engineers trained in API-driven provisioning intensifies the demand for fully managed solutions that conceal complexity behind user-friendly portals. Consequently, providers embed orchestration APIs that allow enterprises to script bandwidth as code within DevOps pipelines.
Shift from CapEx to OpEx Subscription Budgeting Pressure
Revised IFRS 16 and ASC 842 rules recast owned hardware as a depreciating right-of-use asset, locking capital into long refresh cycles. Subscription NaaS converts fixed investments into elastic expenses, an arrangement prized by private equity portfolios that optimize EBITDA. Manufacturing groups leverage the model to throttle capacity during downturns without writing off equipment. Zero-based budgeting now forces IT leaders to justify spending annually, and pay-as-you-use circuits meet that hurdle more cleanly than multi-year hardware amortization. The shift accelerates vendor competition on service-level quality rather than box specifications, creating an incentive to bundle security and observability in a single invoice.
Persistent Data-Sovereignty and Residency Compliance Barriers
GDPR, China's Cybersecurity Law, and India's forthcoming Data Protection Bill require providers to establish separate control planes in each jurisdiction. Replicated infrastructure fragments the global footprint and raises per-site cost, eroding economies of scale. Schrems II further blocks personal-data transfers from the EU to the United States, requiring contractual clauses that many buyers deem risky. Financial institutions face compounded complexity because Basel III mandates resilience testing across all hosting regions. When control planes cannot orchestrate distributed zones from a central console, enterprises deploy hybrid models that temper the value proposition of the Network-as-a-Service market.
Other drivers and restraints analyzed in the detailed report include:
- SD-WAN and SASE Convergence Accelerating Managed WAN Refresh
- AI-Driven Network Assurance Reducing MTTR below 5 min
- Vendor Lock-In Fears around Proprietary Lifecycle Platforms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, WAN-as-a-Service generated 61.50% of revenue, underscoring its role as the entry point for the Network As A Service market share. Multinationals with 50+ branches can capture immediate savings by replacing MPLS circuits with SD-WAN overlays, resulting in a 60% reduction in per-megabit costs. AI engines embedded in controllers dynamically steer traffic to the nearest cloud on-ramp, shrinking file transfer times between headquarters and public cloud. Service providers reinforce value through zero-touch edge devices that arrive pre-provisioned, thereby reducing deployment windows from weeks to hours.
LAN-as-a-Service, though smaller today, is growing at a 23.01% CAGR through 2031 as Wi-Fi 7 access points demand 802.3bt power budgets. Universities and hospitals that cannot fund wholesale switch upgrades pivot to campus-switch-as-a-service bundles that include power, analytics, and handset integration. Providers guarantee 10-gig uplinks for telepresence and electronic medical records, positioning LAN refresh as an operating expense rather than a capital hurdle. By converting campus networks into predictable subscriptions, suppliers expand the addressable pool of buyers, thereby increasing overall momentum in the Network As A Service market.
Virtual CPE captured 42.80% of application spend in 2025, reflecting the consolidation of routers, firewalls, and WAN optimizers onto x86 appliances. Branch offices reduce their hardware footprint by 70% and slash onsite service calls because zero-touch provisioning loads the full software stack at power-on. Bandwidth-on-demand supports temporary scale-ups at stadiums and conference centers, demonstrating the elasticity at the heart of the Network As A Service market.
Network-as-API, while nascent, is forecast to grow at a 22.78% CAGR to 2031. GSMA CAMARA specifications let developers program quality-of-service and device profiling directly from CI/CD pipelines. Telecommunications operators expose 5G network functions, such as geofencing, dynamic SIM activation, and guaranteed bit rates, creating new revenue paths beyond traditional connectivity. As enterprise DevOps teams integrate networking calls into application code, value shifts from physical links to API consumption, opening up greenfield opportunities within the broader Network As A Service market.
Complete Report Scope:
- By Type
- LAN-as-a-Service
- WAN-as-a-Service
- Campus-Switch-as-a-Service
- Data-Centre-Interconnect-as-a-Service
- Private-5G-as-a-Service
- By Application
- Virtual CPE (vCPE)
- Bandwidth-on-Demand (BoD)
- Integrated Network-Security-as-a-Service
- Virtual Private Network (VPN)
- Private Network Slice-as-a-Service
- Network-as-API
- By Organisation Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Industry Vertical
- IT and Telecom
- BFSI
- Healthcare
- Manufacturing
- Retail and E-commerce
- Government and Public Sector
- Other Industry Verticals
- By Deployment Model
- Public-Cloud-Based NaaS
- Private-Cloud-Based NaaS
- Hybrid NaaS
- On-Prem Subscription NaaS
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America claimed 41.60% of the Network As A Service market in 2025, underpinned by Fortune 500 migrations from MPLS to SD-WAN, which lower network spend by 40%. Dense cloud interconnection fabrics mean most U.S. enterprises have access to at least three availability zones within 20 milliseconds of end users. Federal procurement funnels business toward providers holding impact-level clearances, so incumbents such as AT&T, Verizon, and Lumen defend share despite new entrants. Low-latency 5G slices for Wall Street trading demonstrate premium use cases that are willing to pay for microsecond-grade jitter control.
Asia-Pacific is on course for a 22.95% CAGR through 2031. India's Digital India initiative anchors government cloud adoption, and domestic data-localization clauses ensure demand for regional control planes. China Mobile and Huawei roll out private 5G at industrial hubs, while Japan's post-earthquake resilience push drives enterprises to multi-region NaaS architectures. South Korea's smart city sensors require priority slices for emergency vehicles, and Australia's mines rely on private 5G to guide autonomous trucks across 200 kilometers of outback terrain. Collectively, these programs expand the Network As A Service market across the world's fastest-growing economies.
Europe experiences fragmented deployment because the GDPR requires in-region data processing, which inflates per-site costs and prevents global optimization. Sovereign cloud zones in Germany and France ensure compliance, but they also demand parallel investments in staffing and monitoring. The United Kingdom's regulatory divergence post-Brexit further complicates matters, compelling vendors to duplicate infrastructure. Meanwhile, Middle East sovereign funds are backing hyperscale data-center interconnects to achieve Vision 2030 milestones, thereby reinforcing demand in Saudi Arabia and the UAE. Africa advances slowly outside of South Africa and Egypt, as mobile-first infrastructure competes for limited spectrum, although pan-African fiber projects by Liquid Intelligent Technologies are beginning to unlock latent enterprise demand.
- Cisco Systems, Inc.
- Hewlett Packard Enterprise (Aruba/GreenLake)
- AT&T Inc.
- Verizon Communications Inc.
- IBM Corp.
- DXC Technology
- TD SYNNEX
- NEC Corp.
- Oracle Corp.
- GTT Communications
- VMware (Broadcom)
- Telstra Group
- Lumen Technologies
- Cato Networks
- Aryaka Networks
- Juniper Networks
- Nokia (Alcatel-Lucent Enterprise)
- Akamai Technologies
- Masergy (Comcast Business)
- Proofpoint / Meta Networks
- Extreme Networks
- Fortinet Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Enterprises' "Cloud-First" Network Transformation Roadmaps
- 4.2.2 Shift from CapEx to OpEx Subscription Budgeting Pressure
- 4.2.3 SD-WAN and SASE Convergence Accelerating Managed WAN Refresh
- 4.2.4 Campus-LAN NaaS Demand to Counter Wi-Fi 7 Power Spikes
- 4.2.5 AI-Driven Network Assurance Reducing MTTR below 5 min
- 4.2.6 Private-5G Network Slicing Sold "As-a-Service" by CSPs
- 4.3 Market Restraints
- 4.3.1 Persistent Data-Sovereignty and Residency Compliance Barriers
- 4.3.2 Vendor Lock-In Fears around Proprietary Lifecycle Platforms
- 4.3.3 Complex Lease-Accounting Rules under IFRS 16/ASC 842
- 4.3.4 Edge-Site Power Cost Volatility Impacting NaaS TCO
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of the Impact of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 LAN-as-a-Service
- 5.1.2 WAN-as-a-Service
- 5.1.3 Campus-Switch-as-a-Service
- 5.1.4 Data-Centre-Interconnect-as-a-Service
- 5.1.5 Private-5G-as-a-Service
- 5.2 By Application
- 5.2.1 Virtual CPE (vCPE)
- 5.2.2 Bandwidth-on-Demand (BoD)
- 5.2.3 Integrated Network-Security-as-a-Service
- 5.2.4 Virtual Private Network (VPN)
- 5.2.5 Private Network Slice-as-a-Service
- 5.2.6 Network-as-API
- 5.3 By Organisation Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By Industry Vertical
- 5.4.1 IT and Telecom
- 5.4.2 BFSI
- 5.4.3 Healthcare
- 5.4.4 Manufacturing
- 5.4.5 Retail and E-commerce
- 5.4.6 Government and Public Sector
- 5.4.7 Other Industry Verticals
- 5.5 By Deployment Model
- 5.5.1 Public-Cloud-Based NaaS
- 5.5.2 Private-Cloud-Based NaaS
- 5.5.3 Hybrid NaaS
- 5.5.4 On-Prem Subscription NaaS
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Nigeria
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Cisco Systems, Inc.
- 6.4.2 Hewlett Packard Enterprise (Aruba/GreenLake)
- 6.4.3 AT&T Inc.
- 6.4.4 Verizon Communications Inc.
- 6.4.5 IBM Corp.
- 6.4.6 DXC Technology
- 6.4.7 TD SYNNEX
- 6.4.8 NEC Corp.
- 6.4.9 Oracle Corp.
- 6.4.10 GTT Communications
- 6.4.11 VMware (Broadcom)
- 6.4.12 Telstra Group
- 6.4.13 Lumen Technologies
- 6.4.14 Cato Networks
- 6.4.15 Aryaka Networks
- 6.4.16 Juniper Networks
- 6.4.17 Nokia (Alcatel-Lucent Enterprise)
- 6.4.18 Akamai Technologies
- 6.4.19 Masergy (Comcast Business)
- 6.4.20 Proofpoint / Meta Networks
- 6.4.21 Extreme Networks
- 6.4.22 Fortinet Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment