

|
시장보고서
상품코드
2123053
셀프서비스 BI 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Self-service BI - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 셀프서비스 BI 시장 규모는 2025년 71억 달러로 평가되었고, 2026년에는 79억 1,000만 달러로 추정되고, 2026-2031년 CAGR 11.41%로 성장을 지속할 전망이며, 2031년에는 135억 9,000만 달러에 이를 것으로 예측됩니다.
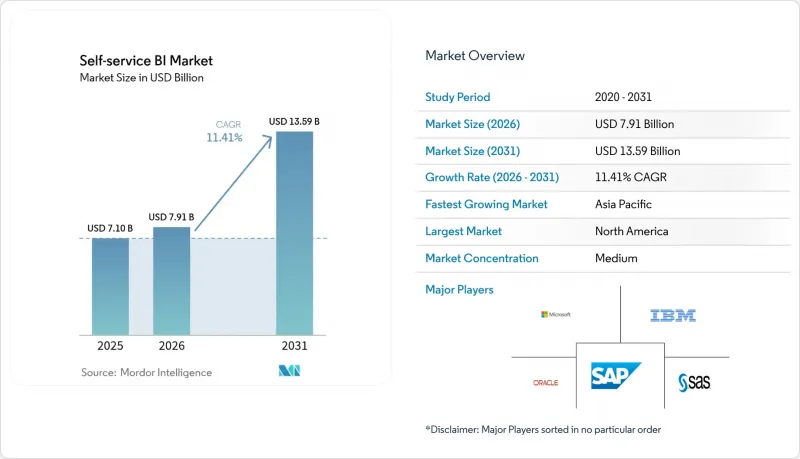
본 보고서는 구성 요소별(소프트웨어 및 서비스), 도입 모델별(클라우드/온디맨드 및 온프레미스), 용도별(영업·마케팅 관리, 고객 참여 및 분석, 부정 및 보안 관리 등), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 헬스케어, 제조업 등), 조직 규모별(대기업 및 중소기업), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 셀프서비스 BI 시장 동향 및 인사이트
로우코드/노코드 도구를 통한 분석의 민주화
로우코드 인터페이스를 통해 비즈니스 전문가들은 개발자에게 의존하지 않고도 대시보드를 생성할 수 있게 되었습니다. 이러한 변화는 북미에서 가장 두드러지며, 해당 지역의 경영진의 80%는 의사 결정의 신속화가 데이터 접근성 확대에 기인한다고 평가했습니다. 시민 데이터 사이언스자들이 전문 지식과 간소화된 도구를 결합함으로써 기존 BI 팀이 간과하기 쉬웠던 패턴을 밝혀냈고, 분석 업무 생산성은 74% 향상되었습니다. 민주화와 견고한 시맨틱 레이어를 융합한 기업은 백로그 이관을 줄이고, 조치가 여전히 중요한 운영 기간 내에 인사이트를 제공했습니다. 이러한 문화적 변화로 인해 플랫폼의 평가 기준은 기능의 깊이에서 기술적 지식이 없는 직원들의 도입 용이성으로 확대되고 있으며, 직관적인 드래그 앤 드롭 방식의 작성 기능과 앱 내 안내를 중심으로 한 플랫폼 통합이 진행되고 있습니다.
클라우드 기반 데이터 웨어하우스의 급증으로 셀프 서비스 도입 가속화
아시아태평양의 기업들은 데이터를 클라우드에 저장함으로써 레거시 스택을 뛰어넘고, 과거 BI 동시 실행을 제한하던 병목 현상을 해소하고 있습니다. 클라우드 데이터 웨어하우스 시장 자체가 연평균 성장률(CAGR) 27.64%로 확대되는 가운데, 분석 팀은 작업을 대기열에 넣지 않고도 최신 데이터를 쿼리할 수 있게 되어 보고서 작성 시간을 최대 40% 단축하고 있습니다. 셀프 서비스 도입과 데이터 웨어하우스 현대화를 연계하는 기업들은 사일로화된 도입 환경에 비해 인사이트 확보까지 걸리는 시간을 3분의 1로 단축하고 있습니다. 또한, 이러한 데이터 웨어하우스에 내장된 통합 거버넌스를 통해 데이터 품질이 향상되고, 부서 간에 일관된 지표 활용이 가능해집니다.
관리되지 않는 시각화 도구가 초래하는 섀도 IT의 위험
검토 과정을 거치지 않은 도구의 도입은 KPI 불일치를 초래하고 기밀성이 높은 데이터 세트의 유출 원인이 되며, 규정 준수 위반 기업에는 건당 평균 103만 달러의 비용이 발생하고 있습니다. 마케팅 부서나 재무 부서는 신속한 반복 작업을 수행하는 과정에서 IT 부서를 우회하는 경향이 있어 이러한 위반을 빈번히 저지르고 있습니다. 업계 선두 기업들은 카탈로그 기반 거버넌스, 자동화된 데이터 계보, 역할 기반 접근 제어를 도입하여 민첩성을 유지하면서 위험을 억제하고 있습니다. 그 결과, 전면적인 차단 방식에 비해 도구 채택률이 45% 더 높습니다.
부문 분석
소프트웨어 부문은 여전히 수익의 주축을 이루고 있지만, 서비스 수익은 연평균 성장률(CAGR) 14.92%로 더 빠르게 증가하고 있습니다. 플랫폼 구매와 교육 프로그램을 병행하는 조직의 경우, 도구만 구매한 기업에 비해 도입률이 45% 더 높습니다. 수요는 데이터 리터러시 역량 강화와 거버넌스 감사를 아우르는 지속적인 역량 강화형 구독 모델로 전환되고 있습니다. 그 결과, 도입 전문가들은 업계별 플레이북을 패키지화하고 대시보드를 업계별 KPI에 맞추어 조정함으로써 가치 실현까지의 시간을 단축하고 있습니다. 셀프 서비스 BI 서비스 시장 규모는 2031년까지 58억 3,000만 달러에 달할 것으로 예상되며, 이는 자동화와 병행하여 인간의 전문 지식에 대한 수요가 지속되고 있음을 반영합니다.
한편, 소프트웨어 벤더들은 AI 기능의 호환성을 우선시하며, NLQ(자연어 쿼리), 자동화된 인사이트, 임베디드 모드를 추가함으로써 경쟁력을 유지하고 있습니다. 끊임없는 업데이트 주기로 인해 기업들은 시맨틱 계층을 제거하지 않고도 분석 엔진을 교체할 수 있는 모듈형 아키텍처를 선호하는 추세입니다. 이러한 접근 방식은 벤더 종속성에 대한 우려를 완화하고, AI 기능의 성숙에 따라 진화하는 멀티툴 환경을 지원합니다.
클라우드 도입은 이용 현황과 성장세 양면에서 우위를 점하고 있으며, 현재 매출의 72.40%를 차지하고, 사용자 수는 연평균 성장률(CAGR) 13.24%로 증가하고 있습니다. 규모의 경제를 통해 중견 기업은 설비 투자 없이 엔터프라이즈급 분석을 도입할 수 있어 대기업과의 경쟁 조건을 평준화하고 있습니다. 또한, 분산된 팀이 공유 작업 공간에서 실시간으로 협업할 수 있어 피드백 루프가 가속화됩니다. 보안 대책도 진화하여, 저장 데이터의 암호화, 프라이빗 링크, 지역별 데이터센터를 통해 현재 대부분의 규제 감사 요건을 충족할 수 있게 되었기 때문에 퍼블릭 클라우드에 대한 이전의 우려는 점차 완화되고 있습니다.
데이터 보관 장소가 의무화되어 있는 규제가 엄격한 업계에서는 온프레미스형 솔루션이 여전히 주류를 이루고 있습니다. 그러나 이러한 업계에서도 하이브리드형 설계가 일반화되고 있습니다. 기밀성이 높은 테이블은 온프레미스에 보관하면서, 집계된 모델은 클라우드에 동기화되어 광범위한 분석이 가능해졌습니다. 예측 기간 동안, 각 하이퍼스케일러 기업들이 BI를 자사의 스토리지 및 AI 서비스와 긴밀하게 통합해 나감에 따라, 클라우드 기반 셀프 서비스 BI 시장 점유율은 80.85%를 소폭 상회할 것으로 예측됩니다.
지역별 분석
북미는 로우코드 플랫폼의 조기 도입과 주요 벤더의 존재에 힘입어 셀프 서비스 BI 시장 매출의 41.50%를 계속 차지하고 있습니다. 이 지역의 금융 서비스 및 의료 서비스 제공업체들은 일상 업무에 자연어 쿼리를 통합하고 있으며, 성숙한 거버넌스 프로그램을 통해 사용자 만족도를 높게 유지하고 섀도 IT의 발생을 억제하고 있습니다. 연구 개발 투자는 고급 AI의 설명 가능성에 중점을 두고 있으며, 규제가 엄격한 환경에서 권고 사항의 근거를 설명할 수 있는 시스템 구축이 진행되고 있습니다. 국경을 넘는 데이터 공유에 관한 규제는 여전히 주시해야 할 사항이지만, 이 지역의 정교한 클라우드 인프라는 플랫폼 생태계를 확장하는 혁신적인 분석 분야 스타트업을 계속해서 유치하고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 연평균 성장률(CAGR) 13.50%를 기록하며 확대되고 있습니다. 중국, 인도, 일본, 호주에서는 국내 주요 클라우드 기업과 하이퍼스케일러들이 데이터센터에 자본을 투자하고 있어 수요가 활발합니다. 이 지역의 중소기업들은 데스크톱 단말기 부족을 극복하기 위해 모바일 우선 분석을 활용하고 있으며, 스마트폰 대시보드가 많은 현장 직원들에게 주요 인터페이스로 자리 잡고 있습니다. 데이터 거버넌스 분야의 인력 부족은 여전히 지속되고 있으며, 이에 따라 정부 및 학술 기관은 인증 프로그램을 출범시키고 있어 2027년 이후에는 이러한 제약이 완화될 전망입니다. 일본과 한국에서는 예측 유지보수가 ‘인더스트리 4.0’ 로드맵과 부합함에 따라 제조업 분야에서 도입이 진행되고 있습니다. 한편, 싱가포르 등의 금융 허브에서는 지역 은행 서비스의 차별화를 위해 고객 분석이 중시되고 있습니다.
유럽에서는 엄격한 개인정보 보호 규제의 영향으로 꾸준한 보급이 진행되고 있습니다. 각 조직은 세심한 동의 관리와 현지 데이터 처리를 지원하는 플랫폼을 도입함으로써 데이터 민주화와 GDPR(EU 개인정보보호규정) 준수의 균형을 맞추고 있습니다. 다국어를 지원하는 자연어 인터페이스는 특히 높은 평가를 받고 있으며, 파일럿 프로젝트에서는 기술에 익숙하지 않은 직원의 참여도를 50% 향상시켰습니다. 서유럽에서는 규제 당국이 암호화와 현지 장애 복구 기능이 주권 요건을 충족한다는 점을 명확히 함에 따라 클라우드 전환이 가속화되고 있습니다. 동유럽에서는 폴란드, 루마니아, 체코 공화국에 디지털 전환 자금이 유입되면서 빠르게 추격하고 있습니다. 소매업과 맞춤형 제조업이 수요의 대부분을 차지하고 있지만, 독점적 락인(lock-in)을 우려하는 기관에서는 오픈소스 대안이 지지를 얻고 있습니다.
남미, 중동 및 아프리카에서는 아직 도입이 초기 단계이지만, 미래 전망은 밝다고 할 수 있습니다. 라틴아메리카에서는 브라질과 멕시코가 도입을 주도하고 있으며, 통신 사업자와 은행이 고객 동향을 실시간으로 파악하기를 원하고 있습니다. 중동에서는 걸프협력회의(GCC) 회원국 정부가 투자의 중심이 되어, 비즈니스 인텔리전스(BI)를 활용하여 경제 다각화 추진 및 스마트 시티 구상을 지원하고 있습니다. 아프리카의 보급 현황은 지역별로 편차가 보이지만, 남아프리카공화국이 기업 대상 도입을 주도하는 한편, 나이지리아와 케냐에서는 핀테크 생태계를 통해 성장세를 보이고 있습니다. 이 지역 전반에 걸쳐 레거시 시스템 도입이 제한적이기 때문에 클라우드 솔루션이 선호되고 있으며, 데스크톱 보급률이 낮은 지역에서는 모바일 대시보드가 인프라 격차를 메우고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the self-service BI market size is expected to grow from USD 7.10 billion in 2025 to USD 7.91 billion in 2026 and is forecast to reach USD 13.59 billion by 2031 at 11.41% CAGR over 2026-2031.
This report is Segmented by Component (Software and Services), Deployment Model (Cloud / On-Demand and On-Premises), Application (Sales and Marketing Management, Customer Engagement and Analysis, Fraud and Security Management and More), End-User Industry (BFSI, Healthcare, Manufacturing and More), Organization Size ( Large Enterprises and SMEs), Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Self-service BI Market Trends and Insights
Democratization of analytics via low-code/no-code tools
Low-code interfaces let business professionals create dashboards without relying on developers, a shift most visible in North America where 80% of executives credit wider data access for faster decisions. Productivity for analytical tasks has risen 74% as citizen data scientists pair domain knowledge with simplified tooling, unearthing patterns traditional BI teams often overlook. Companies that married democratization with robust semantic layers cut backlog hand-offs and delivered insight within the operational window where actions still matter. This cultural change is expanding platform evaluation criteria from feature depth to the ease of onboarding non-technical staff, driving platform consolidation around intuitive drag-and-drop authoring and in-app guidance.
Surge in cloud-based data warehouses accelerating self-service adoption
Asia-Pacific organizations are leapfrogging legacy stacks by landing data in the cloud, eliminating bottlenecks that once restricted BI concurrency. With the cloud warehouse segment itself climbing at 27.64% CAGR, analytics teams now query fresh data without queuing jobs, shrinking report time by as much as 40%. Firms that align self-service rollouts with warehouse modernization gain triple-speed time-to-insight compared with siloed deployments. Centralized governance baked into these warehouses also raises data quality, enabling consistent metrics across departments.
Shadow-IT risks from uncontrolled visualization tools
Unvetted tool adoption has generated conflicting KPIs and exposed sensitive datasets, costing non-compliant firms USD 1.03 million on average per incident. Marketing and finance units are frequent offenders because rapid iterations tempt them to sidestep IT. Best-in-class enterprises deploy catalog-driven governance, automated lineage, and role-based access that preserve agility yet curb risk, yielding 45% higher adoption than blanket lockdown approaches.
Other drivers and restraints analyzed in the detailed report include:
- Integration of generative AI for natural-language querying
- Embedded analytics demand from SaaS vendors
- Shortage of data-governance talent in emerging economies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The software segment continues to anchor revenue, yet services revenue is compounding faster at 14.92% CAGR. Organizations that pair platform purchases with training programs report adoption rates 45% higher than tool-only buyers. Demand is shifting toward continuous enablement subscriptions that cover data-literacy upskilling and governance audits. As a result, implementation specialists are packaging industry-specific playbooks, aligning dashboards with vertical KPIs, and expediting time-to-value. The self-service BI market size for services is projected to reach USD 5.83 billion by 2031, reflecting sustained appetite for human expertise alongside automation.
Software vendors, meanwhile, prioritize AI feature parity, adding NLQ, automated insights, and embedded modes to remain competitive. The relentless update cadence pushes enterprises to favor modular architectures that let them swap analytic engines without ripping out semantic layers. This posture mitigates vendor lock-in concerns and supports mixed-tool environments that evolve as AI capabilities mature.
Cloud deployments own both usage and momentum, commanding 72.40% of current revenue and adding users at a 13.24% CAGR. Economies of scale let mid-market firms implement enterprise-grade analytics without capital outlay, leveling the playing field with larger peers. Moreover, distributed teams can collaborate on shared workspaces in real time, accelerating feedback loops. Security postures have evolved; encryption-at-rest, private links, and regional data centers now satisfy most regulatory audits, tempering earlier reservations about public cloud.
On-premises solutions persist in heavily regulated verticals where data residency is mandatory. Yet even there, hybrid designs are common: sensitive tables stay onsite while aggregated models sync to the cloud for broad exploration. Over the forecast period, the self-service BI market share for cloud is expected to edge past 80.85% as hyperscalers integrate BI tightly with their storage and AI services.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Model
- Cloud / On-Demand
- On-Premises
- By Application
- Sales and Marketing Management
- Customer Engagement and Analysis
- Fraud and Security Management
- Predictive Asset Maintenance
- Risk and Compliance Management
- Supply Chain and Procurement
- Operations Management
- By End-user Industry
- BFSI
- Retail and E-commerce
- Healthcare
- Manufacturing
- Telecommunications
- Media and Entertainment
- Transportation and Logistics
- Energy and Utilities
- Government and Defense
- By Organization Size
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retains 41.50% of self-service BI market revenue, buoyed by early adoption of low-code platforms and the presence of leading vendors. Financial services and healthcare providers there embed natural-language querying in day-to-day workflows, keeping user sentiment high and shadow-IT incidents under control through mature governance programs. R&D investments focus on advanced AI explainability, preparing systems to justify recommendations in regulated settings. Cross-border data-sharing rules remain a watchpoint, yet the region's sophisticated cloud infrastructure continues to attract innovative analytics startups that expand platform ecosystems.
Asia-Pacific is the fastest growing territory, advancing at a 13.50% CAGR. China, India, Japan, and Australia demonstrate vigorous demand as domestic cloud giants and hyperscalers alike pour capital into data centers. SMEs in the region use mobile-first analytics to overcome desktop scarcity, with smartphone dashboards becoming the primary interface for many field employees. Talent shortages in data governance persist, prompting governments and academia to launch certification programs that should ease constraints after 2027. Manufacturing adoption is strong in Japan and South Korea, where predictive maintenance aligns with Industry 4.0 roadmaps, while financial hubs like Singapore emphasize customer analytics to differentiate regional banking services.
Europe shows steady uptake shaped by strict privacy statutes. Organizations balance democratization with GDPR compliance by opting for platforms that support fine-grained consent management and local data processing. Multilingual natural-language interfaces are especially valued, lifting engagement among non-technical staff by 50% in pilot projects. Western European cloud migration is accelerating after regulators clarified that encryption and local failover meet sovereignty requirements. Eastern Europe is catching up quickly as digital transformation funding flows into Poland, Romania, and the Czech Republic. Retail and discrete manufacturing dominate demand, though open-source alternatives gain traction in institutions wary of proprietary lock-in.
South America, the Middle East, and Africa remain early-stage yet promising. Brazil and Mexico head Latin American adoption, with telecom operators and banks seeking real-time customer views. Gulf Cooperation Council governments anchor investment in the Middle East, leveraging BI to support diversification agendas and smart-city initiatives. African uptake is fragmented; South Africa leads enterprise deployments, while Nigeria and Kenya show momentum through fintech ecosystems. Across these regions, cloud solutions enjoy preference owing to limited legacy estates, and mobile dashboards bridge infrastructure gaps in areas where desktop penetration is low.
- Microsoft Corporation
- SAP SE
- Salesforce (Tableau)
- Qlik Tech Intl.
- IBM Corporation
- Oracle Corporation
- SAS Institute
- MicroStrategy Inc.
- TIBCO Software
- Zoho Corporation (Analytics)
- Amazon Web Services (QuickSight)
- Google LLC (Looker)
- Domo Inc.
- Sisense Inc.
- ThoughtSpot Inc.
- Pyramid Analytics
- Yellowfin BI
- GoodData Corp.
- Board International
- Infor (Birst)
- Alibaba Cloud (Quick BI)
- Dundas Data Visualization
- SentryOne (BI Sentry)
- Phocas Software
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Democratization of Analytics via Low-code/No-code Tools in North America
- 4.2.2 Surge in Cloud-based Data Warehouses Accelerating Self-service Adoption in APAC
- 4.2.3 Integration of Generative AI for Natural-Language Querying in Europe
- 4.2.4 Embedded Analytics Demand from SaaS Vendors in BFSI & Retail
- 4.2.5 Rising Data-Literacy Programs Among Mid-Sized Enterprises
- 4.2.6 Regulatory Push for Data-Residency Compliance Driving Localized BI Platforms (MEA)
- 4.3 Market Restraints
- 4.3.1 Shadow-IT Risks from Uncontrolled Data Visualization Tools
- 4.3.2 Shortage of Data Governance Talent in Emerging Economies
- 4.3.3 High Migration Cost from Legacy BI to Self-service Stacks
- 4.3.4 Vendor Lock-in Concerns with Proprietary Semantic Layers
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Model
- 5.2.1 Cloud / On-Demand
- 5.2.2 On-Premises
- 5.3 By Application
- 5.3.1 Sales and Marketing Management
- 5.3.2 Customer Engagement and Analysis
- 5.3.3 Fraud and Security Management
- 5.3.4 Predictive Asset Maintenance
- 5.3.5 Risk and Compliance Management
- 5.3.6 Supply Chain and Procurement
- 5.3.7 Operations Management
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 Retail and E-commerce
- 5.4.3 Healthcare
- 5.4.4 Manufacturing
- 5.4.5 Telecommunications
- 5.4.6 Media and Entertainment
- 5.4.7 Transportation and Logistics
- 5.4.8 Energy and Utilities
- 5.4.9 Government and Defense
- 5.5 By Organization Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium-sized Enterprises (SMEs)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 SAP SE
- 6.4.3 Salesforce (Tableau)
- 6.4.4 Qlik Tech Intl.
- 6.4.5 IBM Corporation
- 6.4.6 Oracle Corporation
- 6.4.7 SAS Institute
- 6.4.8 MicroStrategy Inc.
- 6.4.9 TIBCO Software
- 6.4.10 Zoho Corporation (Analytics)
- 6.4.11 Amazon Web Services (QuickSight)
- 6.4.12 Google LLC (Looker)
- 6.4.13 Domo Inc.
- 6.4.14 Sisense Inc.
- 6.4.15 ThoughtSpot Inc.
- 6.4.16 Pyramid Analytics
- 6.4.17 Yellowfin BI
- 6.4.18 GoodData Corp.
- 6.4.19 Board International
- 6.4.20 Infor (Birst)
- 6.4.21 Alibaba Cloud (Quick BI)
- 6.4.22 Dundas Data Visualization
- 6.4.23 SentryOne (BI Sentry)
- 6.4.24 Phocas Software
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


