|
시장보고서
상품코드
2123083
고급 분석 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Advanced Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
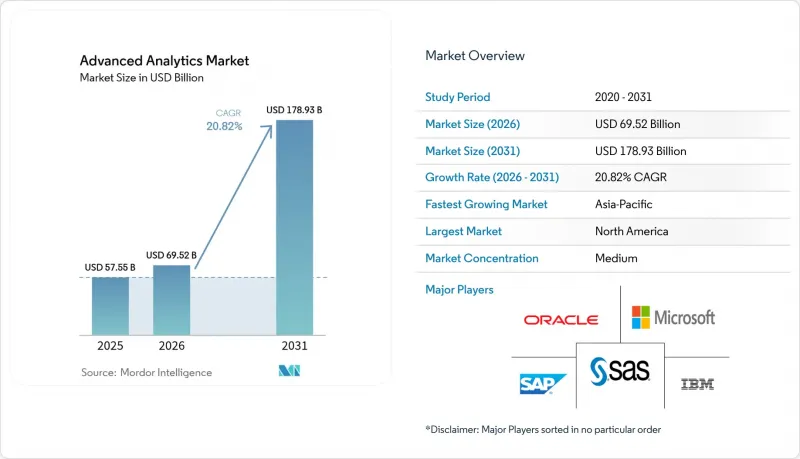
에 의하면, 2026년 고급 분석 시장 규모는 695억 2,000만 달러로 추정되고, 2025년 575억 5,000만 달러에서 확대해, 2031년에는 1,789억 3,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 20.82%를 나타낼 것으로 전망됩니다.
본 보고서는 유형별(통계 분석, 텍스트 분석 등), 도입 형태별(온프레미스, 클라우드, 하이브리드), 구성 요소별(솔루션 및 서비스), 업무 기능별(영업·마케팅, 재무·리스크 등), 최종 사용자 산업별, 조직 규모별(대기업, 중소기업) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 고급 분석 시장 동향 및 인사이트
증가하는 부정 감지 수요
금융 기관은 규칙 기반 시스템으로는 대응하기 어려울 정도로 정교해진 부정 행위 위협에 직면해 있습니다. 미국 규제 당국은 AI를 활용한 모니터링을 권장하고 있으며, 머신러닝 모델은 이미 감지 정확도를 40% 향상시키는 동시에 오탐을 절반으로 줄이고 있습니다. IBM의 조사에 따르면, 대규모 거래 데이터를 거의 실시간으로 분석한 경우 95%의 분류 정확도가 확인되었습니다. 하이브리드 클라우드 및 엣지 아키텍처는 1초 미만의 지연 시간 요건을 충족하며, 서비스 제공업체가 사기 분석, 규정 준수 대시보드, 모델 거버넌스를 통합 플랫폼에 통합할 수 있는 기회를 창출하고 있습니다.
빅데이터의 양과 복잡성의 폭발적인 증가
2024년, 기업들은 하루에 3억 2,877만 TB의 데이터를 생성하고 있으며, 이는 기존의 BI 도구로는 처리하기 어려운 양입니다. 현재 기업의 거의 절반이 고급 분석 솔루션 도입을 위해 사일로화된 데이터 소스를 통합하기 위해 하이브리드 스토리지나 데이터 패브릭 접근 방식을 채택하고 있습니다. 2025년까지 핵심 처리 작업의 50% 이상이 기존 데이터센터 외부에서 이루어질 것으로 예상되며, 기술적 지식이 없는 비즈니스 사용자에게도 인사이트를 제공할 수 있는 자동화된 데이터 준비 및 확장형 분석에 대한 필요성이 높아지고 있습니다.
데이터 통합 및 연결성의 격차
분산된 아키텍처로 인해 데이터는 종종 노후화된 온프레미스 시스템, 클라우드 및 OT(운영 기술) 시스템에 갇히게 됩니다. 조직에서는 엔지니어링 시간의 64%를 분석이 아닌 통합에 소비하고 있으며, 이는 투자 회수를 지연시키고 대규모 프로젝트에 대한 의욕을 저하시킵니다. 제조업체들은 분석 연동을 복잡하게 만드는 독자적인 프로토콜과의 싸움에 직면해 있으며, 데이터 패브릭 및 노코드 통합 솔루션에 대한 기대가 높아지고 있습니다.
부문 분석
엣지 애널리틱스는 지연 시간이 중요한 IoT 시나리오에서의 역할을 반영하여 2031년까지 연평균 성장률(CAGR) 27.35%를 유지할 전망입니다. 대조적으로, 예측 분석은 예측 분야의 주류 옵션으로서 2025년 시점에서 고급 분석 시장의 24.05% 점유율을 유지했습니다. 엣지 디바이스는 로컬에서 추론을 수행함으로써 네트워크 비용을 절감하고, 규제가 엄격한 산업에 필수적인 데이터 주권을 확보합니다. 자동차, 에너지, 제조 업계의 각 기업은 이상 감지 및 자율 제어 루프를 구현하기 위해 소형 추론 칩을 탑재하고 있습니다. 각 벤더는 원시 데이터를 외부로 전송하지 않고도 세계 모델을 학습시키는 페더레이티드 러닝 기능을 통해 차별화를 꾀하고 있습니다. 비정형 데이터의 양이 급증하는 가운데, 텍스트 및 시각적 분석의 도입은 견조한 추세를 보이고 있는 반면, 예측 분석 및 리스크 분석은 최적화 및 시나리오 모델링에 대한 수요에 힘입어 성장하고 있습니다.
5G 커버리지 범위가 확대됨에 따라 엣지 분석의 고급 분석 시장 규모는 급속히 확대될 전망입니다. 중요 인프라 소유자들은 중앙 집중형 클라우드에서 터빈, 변전소, 차량으로 의사결정 로직을 분산시키는 분산형 메쉬 패브릭으로 전환하고 있습니다. 한편, 기존 예측 플랫폼은 구식화를 피하기 위해 실시간 데이터 스트림을 통합하고 있으며, 이는 시장이 하이브리드 클라우드-엣지 설계로 전환되고 있음을 보여줍니다.
은행 및 공공 기관에서 선호하는 온프레미스형 아키텍처는 주로 데이터 주권 관련 규제로 인해 2025년 매출의 53.40%를 차지했습니다. 그럼에도 불구하고, 기업들이 탄력적인 확장성과 종량제 경제성을 추구함에 따라 클라우드 도입은 연평균 성장률(CAGR) 23.95%로 증가하고 있습니다. 하이퍼스케일러들은 GPU 플릿 확장을 우선시하고 있지만, 간헐적인 용량 부족으로 인해 전문 분석용 클라우드 및 코로케이션-엣지 하이브리드 시장에 진입할 기회가 생겨나고 있습니다.
보안 강화와 기밀 컴퓨팅 서비스 덕분에 고객의 우려는 꾸준히 해소되고 있습니다. 클라우드 워크로드를 위한 고급 분석 시장 규모는 드리프트 감지, 버전 관리, 거버넌스를 자동화하는 관리형 모델 운영(ModelOps) 제품군을 통해 더욱 확대되고 있습니다. 하이브리드 시나리오에서는 기밀성이 높은 온프레미스 데이터 처리와 클라우드로의 버스트형 훈련 주기를 결합하여, 혁신을 제한하지 않으면서 규정 준수를 확보하고 있습니다. 지역별 데이터 거주지에 관한 법률이 공급자의 인프라 확충을 좌우하게 되었으며, 특히 EU와 APAC에서는 국내 존이 개인정보 보호 관련 법규를 준수하고 있습니다.
지역별 분석
2025년, 북미는 계속해서 고급 분석 시장 매출의 40.65%를 차지했습니다. 벤처 캐피털은 AI 분야에 1,091억 달러를 투자했으며, 그중 339억 달러는 생성형 모델에 투입되어 스타트업 생태계와 기업의 실험 활동을 확대시켰습니다. 미국의 각 하이퍼스케일러 기업들은 새로운 GPU 클러스터를 도입하여 기존의 용량 제약을 해결하고 있으며, 아마존이 펜실베이니아주에서 200억 달러 규모의 인프라 확장을 단행한 것은 이러한 투자 규모를 여실히 보여줍니다. 규제와 관련된 노력은 많지만 여전히 파편화되어 있으며, 연방과 주 정부의 서로 다른 요건을 해석하는 거버넌스 관련 부가 서비스에 대한 수요가 증가하고 있습니다.
아시아태평양(APAC)은 제조업 자동화, 5G 구축, 그리고 정부의 스마트 시티 보조금을 원동력으로 22.40%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 중국의 AI 모델 기능 강화로 경쟁력 있는 국내 대체 솔루션이 등장하고 있는 반면, 인도의 IT 서비스 수출은 지역 제조업체에 구현을 담당할 인재를 공급하고 있습니다. 일본과 한국은 산업용 로봇 및 자율 주행 분야에서 엣지 분석 용도의 활용을 적극적으로 추진하고 있습니다. 총 소유 비용(TCO) 절감 및 공공 부문의 디지털화 정책에 힘입어, 전자상거래, 핀테크, 물류 플랫폼을 통합하는 동남아시아 국가들에서 고급 분석 시장이 확대되고 있습니다.
유럽에서는 엄격하게 진화하는 정책 하에서 시장이 착실히 성장하고 있습니다. EU AI법에 따라, 특히 중요 분야에서 투명성 관련 규정을 충족하기 위한 설명 가능한 플랫폼의 도입이 가속화되고 있습니다. 독일의 자동차 및 기계 제조업체들은 인더스트리 4.0을 향해 예측 분석 및 처방적 분석을 채택하고 있는 반면, 북유럽의 공공 서비스 기업들은 재생에너지를 최적화하기 위해 지속가능성 분석을 도입하고 있습니다. 영국의 금융 기관들은 브렉시트 이후의 리스크 모델 거버넌스에 투자하고 있습니다. 유럽의 고급 분석 시장 규모는 회원국 간 데이터 공유 기준을 조화시키는 국경을 초월한 데이터 스페이스 이니셔티브의 혜택을 받고 있지만, 규정 준수 대응의 부담이 도입 주기를 장기화시키고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the advanced analytics market size in 2026 is estimated at USD 69.52 billion, growing from 2025 value of USD 57.55 billion with 2031 projections showing USD 178.93 billion, growing at 20.82% CAGR over 2026-2031.
This report is Segmented by Type (Statistical Analysis, Text Analytics, and More), Deployment Mode (On-Premises, Cloud, Hybrid), Component (Solutions and Services), Business Function (Sales & Marketing, Finance & Risk, and More), End-User Industry, Organization Size (Large Enterprises, Smes), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Advanced Analytics Market Trends and Insights
Escalating Fraud-Detection Needs
Financial institutions face highly sophisticated fraud threats that outpace rule-based systems. U.S. regulators urge AI-driven monitoring, and machine-learning models already lift detection accuracy by 40% while halving false positives. IBM research shows 95% classification accuracy when large-scale transaction data is analysed in near real time. Hybrid cloud-edge architectures satisfy sub-second latency requirements and create opportunities for providers bundling fraud analytics, compliance dashboards, and model governance into unified platforms.
Big-Data Volume & Complexity Explosion
Enterprises generated 328.77 million TB daily in 2024, overwhelming traditional BI tooling. Nearly half now employ hybrid storage and data-fabric approaches to integrate siloed sources for advanced analytics market deployments. By 2025, more than 50% of critical processing is expected outside conventional data centers, reinforcing the need for automated data preparation and augmented analytics that expose insights to non-technical business users.
Data Integration & Connectivity Gaps
Fragmented architectures often trap data across aging on-premises, cloud, and operational-technology systems. Organizations allocate 64% of engineering time to integration rather than analysis, delaying returns and dampening enthusiasm for large-scale projects. Industrial firms battle proprietary protocols that complicate analytics linkages, reinforcing the premium placed on data-fabric and no-code integration solutions.
Other drivers and restraints analyzed in the detailed report include:
- Enterprise Digital-Transformation Wave
- Regulatory Push for Explainable AI
- Shortage of Data-Science Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Edge Analytics owns a 27.35% CAGR to 2031, reflecting its role in latency-critical IoT scenarios. In contrast, Predictive Analytics retained 24.05% advanced analytics market share in 2025 as the mainstream choice for forecasting. Edge devices perform localized inference, cutting network costs and ensuring data sovereignty, which is vital for regulated verticals. Automotive, energy, and manufacturing players are embedding compact inference chips to enable anomaly detection and autonomous control loops. Vendors differentiate through federated-learning capabilities that train global models without raw-data egress. Text and Visual Analytics hold steady adoption as unstructured data volumes balloon, while Prescriptive and Risk Analytics are spurred by demand for optimization and scenario modelling.
The advanced analytics market size for Edge Analytics is poised to expand rapidly as 5G coverage broadens. Critical infrastructure owners shift from centralized clouds to distributed mesh fabrics that push decision logic to turbines, substations, and vehicles. Meanwhile, established predictive platforms are integrating real-time data streams to avoid obsolescence, illustrating the market's pivot toward hybrid cloud-edge designs
On-Premises architectures, favored by banks and public agencies, accounted for 53.40% revenue in 2025 largely due to data-sovereignty mandates. Still, Cloud deployment is rising at 23.95% CAGR as enterprises pursue elastic scaling and pay-as-you-go economics. Hyperscalers prioritize GPU fleet expansion, though intermittent capacity shortfalls create openings for specialized analytics clouds and colocation-edge hybrids.
Security improvements and confidential-compute services steadily erode customer objections. The advanced analytics market size for cloud workloads gains further lift from managed model-ops suites that automate drift detection, versioning, and governance. Hybrid scenarios blend sensitive on-premises data processing with burst-to-cloud training cycles, ensuring compliance without capping innovation. Regional data-residency laws now shape provider buildouts, particularly in the EU and APAC, where in-country zones address privacy statutes.
Complete Report Scope:
- By Type
- Statistical Analysis
- Text Analytics
- Risk Analytics
- Predictive Analytics
- Prescriptive Analytics
- Visual Analytics
- Network Analytics
- Geospatial Analytics
- Social Media Analytics
- Edge Analytics
- Other Types
- By Deployment Mode
- On-Premise
- Cloud
- Hybrid
- By Component
- Solutions
- Services
- Consulting
- Managed Services
- By Business Function
- Sales and Marketing
- Finance and Risk
- Operations and Supply-Chain
- Human Resources
- Customer Support
- By End-User Industry
- BFSI
- Retail and Consumer Goods
- Healthcare and Life Sciences
- IT and Telecommunication
- Transportation and Logistics
- Government and Defense
- Manufacturing
- Energy and Utilities
- Media and Entertainment
- Other Industries
- By Organization Size
- Large Enterprises
- Small and Mid-Sized Enterprises (SMEs)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America continued to command 40.65% of advanced analytics market revenue in 2025. Venture capital channelled USD 109.1 billion into AI, including USD 33.9 billion for generative models, expanding startup ecosystems and enterprise experimentation. U.S. hyperscalers address prior capacity constraints by injecting new GPU clusters, with Amazon's USD 20 billion Pennsylvania build-out illustrating the scale of investment. Regulatory initiatives, though numerous, remain fragmented, prompting demand for governance add-ons that interpret divergent federal and state requirements.
APAC posts the highest 22.40% CAGR, propelled by manufacturing automation, 5G rollouts, and government smart-city grants. Chinese AI-model enhancements create competitive domestic alternatives, while India's IT-services exports deliver implementation talent to regional manufacturers. Japan and South Korea push deep into edge-analytics applications for industrial robotics and autonomous mobility. Lower total-cost-of-ownership and public-sector digitalization policies expand the advanced analytics market across Southeast Asian nations integrating ecommerce, fintech, and logistics platforms.
Europe grows steadily under rigorously evolving policy. The EU AI Act accelerates purchases of explainable platforms to satisfy transparency rules, especially in critical sectors. Germany's automotive and machinery firms adopt predictive and prescriptive analytics for Industry 4.0, while Nordic utilities embed sustainability analytics to optimize renewables. United Kingdom financial institutions invest in risk-model governance post-Brexit. The advanced analytics market size in Europe benefits from cross-border data-space initiatives that harmonize sharing standards among member states, yet compliance workloads elongate deployment cycles.
- IBM Corporation
- Microsoft Corporation
- SAS Institute Inc.
- SAP SE
- Oracle Corporation
- Amazon Web Services (AWS)
- Google LLC
- Salesforce Inc. (Tableau)
- Teradata Corporation
- QlikTech International AB
- MicroStrategy Incorporated
- Alteryx Inc.
- KNIME AG
- RapidMiner Inc.
- TIBCO Software Inc.
- Altair Engineering Inc.
- Sisense Inc.
- Domo Inc.
- Fair Isaac Corporation (FICO)
- Avanade Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating fraud-detection needs
- 4.2.2 Big-data volume and complexity explosion
- 4.2.3 Enterprise digital-transformation wave
- 4.2.4 Rapid AI/ML and cloud cost declines
- 4.2.5 Edge analytics for real-time decisions
- 4.2.6 Regulatory push for explainable AI
- 4.3 Market Restraints
- 4.3.1 Data integration and connectivity gaps
- 4.3.2 Shortage of data-science talent
- 4.3.3 Sustainability limits on compute energy
- 4.3.4 Vendor lock-in to hyperscale clouds
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Statistical Analysis
- 5.1.2 Text Analytics
- 5.1.3 Risk Analytics
- 5.1.4 Predictive Analytics
- 5.1.5 Prescriptive Analytics
- 5.1.6 Visual Analytics
- 5.1.7 Network Analytics
- 5.1.8 Geospatial Analytics
- 5.1.9 Social Media Analytics
- 5.1.10 Edge Analytics
- 5.1.11 Other Types
- 5.2 By Deployment Mode
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.2.3 Hybrid
- 5.3 By Component
- 5.3.1 Solutions
- 5.3.2 Services
- 5.3.2.1 Consulting
- 5.3.2.2 Managed Services
- 5.4 By Business Function
- 5.4.1 Sales and Marketing
- 5.4.2 Finance and Risk
- 5.4.3 Operations and Supply-Chain
- 5.4.4 Human Resources
- 5.4.5 Customer Support
- 5.5 By End-User Industry
- 5.5.1 BFSI
- 5.5.2 Retail and Consumer Goods
- 5.5.3 Healthcare and Life Sciences
- 5.5.4 IT and Telecommunication
- 5.5.5 Transportation and Logistics
- 5.5.6 Government and Defense
- 5.5.7 Manufacturing
- 5.5.8 Energy and Utilities
- 5.5.9 Media and Entertainment
- 5.5.10 Other Industries
- 5.6 By Organization Size
- 5.6.1 Large Enterprises
- 5.6.2 Small and Mid-Sized Enterprises (SMEs)
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 United Kingdom
- 5.7.3.2 Germany
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Rest of Asia-Pacific
- 5.7.5 Middle East
- 5.7.5.1 Israel
- 5.7.5.2 Saudi Arabia
- 5.7.5.3 United Arab Emirates
- 5.7.5.4 Turkey
- 5.7.5.5 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Egypt
- 5.7.6.3 Rest of Africa
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 IBM Corporation
- 6.4.2 Microsoft Corporation
- 6.4.3 SAS Institute Inc.
- 6.4.4 SAP SE
- 6.4.5 Oracle Corporation
- 6.4.6 Amazon Web Services (AWS)
- 6.4.7 Google LLC
- 6.4.8 Salesforce Inc. (Tableau)
- 6.4.9 Teradata Corporation
- 6.4.10 QlikTech International AB
- 6.4.11 MicroStrategy Incorporated
- 6.4.12 Alteryx Inc.
- 6.4.13 KNIME AG
- 6.4.14 RapidMiner Inc.
- 6.4.15 TIBCO Software Inc.
- 6.4.16 Altair Engineering Inc.
- 6.4.17 Sisense Inc.
- 6.4.18 Domo Inc.
- 6.4.19 Fair Isaac Corporation (FICO)
- 6.4.20 Avanade Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment