|
시장보고서
상품코드
2123088
디지털 저작권 관리(DRM) 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Digital Rights Management (DRM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 디지털 저작권 관리(DRM) 시장 규모는 69억 3,000만 달러로 추정되고 있어 2025년 62억 3,000만 달러에서 확대해, 2031년에는 117억 6,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 11.16%로 성장할 것으로 전망됩니다.
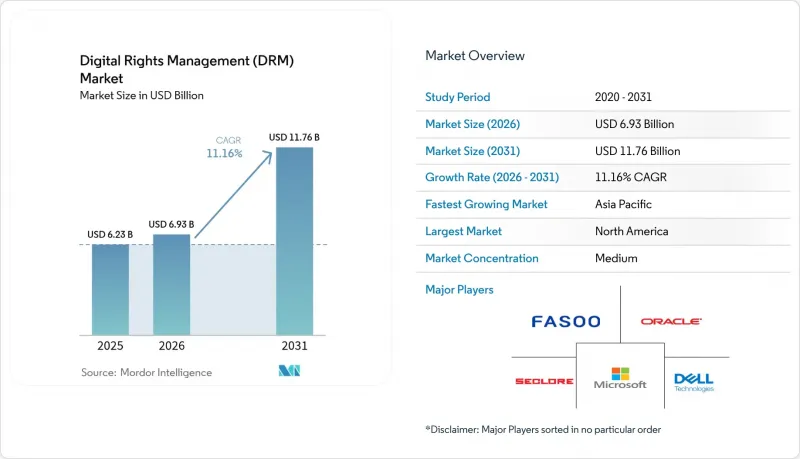
본 보고서는 구성 요소(소프트웨어, 서비스), 배포 방식(On-Premise, 클라우드), 최종 사용자 기업 규모(중소기업, 대기업), 최종 사용자 산업(미디어 및 엔터테인먼트,BFSI, 헬스케어 등) 및 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 세분화되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 디지털 저작권 관리(DRM) 시장 동향 및 인사이트
OTT 동영상 및 스트리밍 구독의 보급
OTT 플랫폼은 Widevine, FairPlay, PlayReady를 아우르는 강력한 암호화 및 멀티 DRM 전략이 필요한 고부가가치 4K 및 8K 컨텐츠를 제공합니다. 스포츠 라이브 스트리밍의 경우, 특히 모바일 중심의 아시아태평양 시청자를 대상으로 저지연 보호 요구 사항이 더욱 높아지고 있습니다. 플랫폼 사업자들은 세션 하이재킹을 억제하기 위해 적응형 비트레이트 스트리밍과 포렌식 워터마크 기술을 결합하여 활용하고 있습니다. 스마트 TV에서 차량용 인포테인먼트 시스템에 이르기까지, 연결 기기의 다양화로 인해 칩셋 간에 원활하게 확장 가능한 표준 기반 DRM에 대한 수요가 증가하고 있습니다. 현재 경쟁적 차별화는 버퍼링이나 해상도 저하 없이 강력한 보안을 제공하는 데 중점을 두고 있으며, 컨텐츠 시장이 점점 더 혼잡해지는 가운데 가입자 유지를 확보하고 있습니다.
BYOD 및 원격 근무에서의 데이터 보안 요구 사항
영구적인 하이브리드 근무 정책에 따라 DRM의 역할은 컨텐츠 보호에서 파일 중심의 데이터 보안 프레임워크로 확대되고 있습니다. 기업들은 제로 트러스트 원칙을 도입하여, 문서와 함께 이동하며 모든 액세스 지점에서 사용자의 신원을 인증하는 지속적인 암호화를 필요로 하고 있습니다. Fasoo의 GPS 지원 화면 워터마크 기술로 대표되는 ‘모바일 퍼스트’ DRM은 관리 대상 외의 Android 및 iOS 기기상의 데이터를 보호하는 동시에, 행동 텔레메트리 데이터를 보안 운영 센터로 전송합니다. ID 및 액세스 관리(IAM) 플랫폼과의 통합을 통해 실시간 액세스 권한 해제가 가능해지며, 감사관이 요구하는 입증 가능한 관리 체계를 충족시킵니다. 이러한 추세는 규정 위반에 대한 벌금이 해마다 높아지고 있는 규제 엄격한 업계에서 특히 두드러집니다.
뿌리 깊은 기기/포맷 비호환성
생태계의 파편화로 인해 브라우저 벤더들이 레거시 모듈을 더 이상 지원하지 않는 상황에서 컨텐츠 소유자는 여러 DRM 구현을 동시에 운영할 수밖에 없게 되었습니다. 구글이 iOS용 Widevine CDM 제공을 종료함에 따라, 개발자는 애플 하드웨어용으로 FairPlay를 통합할 수밖에 없게 되어 유지보수 부담이 두 배로 늘어났습니다. 구형 스마트 TV나 셋톱박스에는 보안 패치가 비정기적으로만 제공되기 때문에 라이선싱 체인에 취약점이 발생하고 있습니다. 모바일 기기와 데스크톱 기기가 혼재된 기업에서는 정책 적용을 표준화하기 어려우며, 그 결과 지원 비용이 증가하고 새로운 컨텐츠 형식의 도입이 지연되고 있습니다.
부문 분석
2025년, 소프트웨어 플랫폼은 디지털 저작권 관리(DRM) 시장 점유율의 63.85%를 차지하며, 통합형 라이선스 서버, 분석 대시보드, 룰 엔진에 대한 꾸준한 수요를 반영하고 있습니다. 한편, 서비스 부문은 조직들이 멀티 DRM 오케스트레이션 및 블록체인 통합을 전문 업체에 의뢰하게 됨에 따라 연평균 성장률(CAGR) 17.32%를 기록했습니다. 관리형 보안 제공업체는 연중무휴 24시간 라이선스 서버 모니터링과 신속한 위협 인텔리전스 업데이트를 결합한 서비스를 제공하며, 사내에 전문 지식이 없는 중소기업에게 매력적인 선택지가 되고 있습니다.
2025년 1분기 Adobe의 디지털 미디어 부문 매출은 42억 3,000만 달러에 달했으며, 이는 구매자 측에서 AI가 통합된 DRM 기능에 대한 투자 의지가 높음을 시사합니다. 컨설팅 업무는 도입 단계에 그치지 않고 지속적인 규정 준수 감사까지 확대되고 있어, 성과 기반 서비스 계약으로의 전환을 뒷받침하고 있습니다. 예측 기간 동안 양자 내성 암호화 시범 프로젝트가 등장함에 따라, 서비스 부문은 기술 격차를 해소하는 역할을 수행할 것으로 예상되며, 증가하는 지출에서 점유율을 공고히할 것입니다.
2025년, 디지털 저작권 관리(DRM) 시장 규모의 56.10%를 클라우드 모델이 차지할 것으로 보이며, 연평균 성장률(CAGR) 17.95%로 확대될 것으로 예측됩니다. 중앙 집중식 라이선스 서버는 정책 업데이트를 용이하게 하고, 스포츠 결승전과 같은 이벤트에 따른 트래픽 급증에 대응할 수 있도록 탄력적으로 확장 가능합니다. IBM에 따르면, 데이터 침해의 82%가 클라우드 환경에서 발생하고 있으며, 이에 따라 기업들은 DRM 관리 대상을 오브젝트 스토리지 계층 및 SaaS 저장소까지 확대되고 있습니다.
하이브리드 토폴로지는 편집을 위해 크리에이티브 자산을 On-Premise에 남겨두면서, 현지화 요구 사항을 충족하기 위해 배포 키를 지역별 클라우드에 배치하는 환경에서 널리 보급되고 있습니다. 엣지 노드에는 경량 DRM이 내장되어 있어, 1초 미만의 지연 시간으로 4K 스트림을 보호함으로써 대역폭이 불안정한 시장에서 발생하는 버퍼링 관련 불만을 완화합니다. 에어 갭 환경이 주류를 이루는 국방 및 공공 안전 분야에서는 여전히 On-Premise 배포가 지속되고 있습니다. 그러나 이러한 분야에서도 운영 비용을 절감하기 위해 프라이빗 클라우드를 통한 키 관리가 검토되고 있습니다.
지역별 분석
2025년, 북미는 디지털 저작권 관리(DRM) 시장의 37.95%를 차지했습니다. 이는 HIPAA, SOX, 캘리포니아주 소비자 개인정보 보호법(CCPA)과 같은 엄격한 업계 규제에 힘입은 결과입니다. 금융 기관과 미디어 대기업은 블록체인 기반의 라이선스 대조 기능을 통합한 멀티 DRM 도입을 주도하며, 로열티 결제 효율화를 도모하고 있습니다. 미국의 클라우드 제공업체는 캐나다 방송사와 제휴하여, 지연 시간을 희생하지 않으면서 상충되는 주권법을 충족하는 국경을 초월한 키볼트 이중화 시스템을 구축하고 있습니다.
아시아태평양은 모바일 동영상 트래픽의 급증과 인도, 인도네시아, 베트남의 데이터 현지화 관련 법규에 힘입어 2031년까지 연평균 성장률(CAGR) 15.94%를 나타낼 것으로 예측됩니다. 중국이 신형 차량에 DRM 수신기 탑재를 의무화하는 지침은 규제 가속화를 여실히 보여주고 있으며, 칩셋 공급업체들에게 비용 최적화된 복호화 블록을 통합하도록 압박하고 있습니다. 인도의 통신 사업자들은 독립 영화 제작자를 위한 수익 분배형 부가가치 서비스로 DRM을 묶어 제공하고 있는 반면, 한국의 교육 기술 기업들은 BYOD 태블릿에서 대화형 교과서의 보안을 확보하고 있습니다. 창작 산업의 수출이 전 세계적으로 수익화를 도모하기 위해서는 상호 운용 가능한 권리 관리가 필요하기 때문에 지역 전체의 지출이 급증하고 있습니다.
유럽에서의 꾸준한 진전은 GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정) 시행의 물결과, 중요 인프라 사업자에게 더 높은 사이버 복원력 기준을 부과할 예정인 NIS2 지침을 반영하고 있습니다. 미디어 규제 당국은 국경을 초월한 스트리밍을 표준화하기 위한 멀티 DRM 협력을 장려하고 있으며, 이는 범유럽 컨텐츠 포털을 지원하고 있습니다. 남유럽의 방송 사업자들은 기존의 CAS 스마트카드에서 통합형 DRM으로 전환하고 있으며, 조건부 접근(CAS) 비용을 30% 절감하고 있습니다. 한편, 남미와 아프리카의 신흥 허브 지역에서는 클라우드 CDN 가격 하락을 발판으로 턴키형 DRM을 도입해 불법 IPTV 서비스를 억제하고 현지 제작 드라마 시리즈를 보호하고 있습니다. 이러한 지역에서는 휴대전화 보급률과 광섬유망 구축이 가속화됨에 따라 시장 점유율이 점차 증가하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, digital rights management market size in 2026 is estimated at USD 6.93 billion, growing from 2025 value of USD 6.23 billion with 2031 projections showing USD 11.76 billion, growing at 11.16% CAGR over 2026-2031.
This report is Segmented by Component (Software, Services), Deployment Mode (On-Premises, Cloud), End-User Enterprise Size (Small and Medium Enterprises, Large Enterprises), End-User Industry (Media and Entertainment, BFSI, Healthcare, and More), and Geography (North America, South America, Europe, Asia Pacific, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Rights Management (DRM) Market Trends and Insights
Proliferation of OTT Video and Streaming Subscriptions
OTT platforms distribute higher-value 4K and 8K assets that demand hardened encryption and multi-DRM strategies to span Widevine, FairPlay, and PlayReady. Live sports streaming intensifies low-latency protection requirements, especially across mobile-centric Asia Pacific audiences. Platform operators leverage adaptive bitrate streaming coupled with forensic watermarking to curb session hijacking. The diversity of connected devices from smart TVs to in-vehicle infotainment fuels demand for standards-based DRM that scales seamlessly across chipsets. Competitive differentiation now centers on delivering robust security without buffering or resolution downgrades, ensuring subscriber retention in an increasingly crowded content landscape.
BYOD and Remote-Work Data-Security Mandates
Permanent hybrid-work policies push DRM from content protection into file-centric data-security frameworks. Enterprises integrate Zero-Trust principles, requiring persistent encryption that travels with a document and authenticates user identity at every access point. Mobile-first DRM, exemplified by Fasoo's GPS-aware screen-watermarking, safeguards data on unmanaged Android and iOS devices while feeding behavioral telemetry into security operations centers . Integration with identity-and-access-management platforms enables real-time revocation, meeting auditors' insistence on demonstrable control. The driver is most pronounced in regulated verticals where fines for non-compliance escalate annually.
Persistent Device/Format Incompatibilities
Ecosystem fragmentation forces content owners to juggle multiple DRM implementations as browser vendors deprecate legacy modules. Google's discontinuation of Widevine CDM on iOS compels developers to integrate FairPlay for Apple hardware, doubling maintenance overhead. Older smart TVs and set-top boxes receive security patches irregularly, creating weak links in license enforcement chains. Enterprises with mixed mobile and desktop fleets struggle to standardize policy enforcement, elevating support costs and delaying rollout of new content formats.
Other drivers and restraints analyzed in the detailed report include:
- Rising Digital-IP Litigation and Penalties
- Government Push for Data-Sovereignty Compliance
- User-Experience Backlash Over Intrusive Controls
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software platforms retained 63.85% of Digital Rights Management market share in 2025, reflecting entrenched demand for integrated license servers, analytics dashboards, and rules engines. Services, however, posted a 17.32% CAGR as organizations turned to specialists for multi-DRM orchestration and blockchain integration. Managed-security providers bundle 24X7 license-server monitoring with rapid threat-intel updates, appealing to SMEs that lack in-house expertise.
Adobe's Digital Media revenue of USD 4.23 billion in Q1 2025 underscores buyers' willingness to invest in AI-infused DRM capabilities. Consulting engagements now extend beyond deployment into continuous compliance auditing, supporting a shift toward outcome-based service contracts. Over the forecast horizon, services are expected to bridge skills gaps as quantum-safe encryption pilots emerge, cementing their share of incremental expenditure.
The cloud model represented 56.10% of Digital Rights Management market size in 2025 and is forecast to expand at 17.95% CAGR. Centralized license servers ease policy updates and scale elastically to support event-driven spikes such as live sports finals. IBM notes that 82% of data breaches occur in cloud venues, prompting enterprises to extend DRM controls into object-storage tiers and SaaS repositories.
Hybrid topologies flourish where creative assets remain on-premises for editing while distribution keys reside in regional clouds to satisfy localization mandates. Edge nodes embed lightweight DRM to secure 4K streams at sub-second latency, reducing buffering complaints in bandwidth-variable markets. On-premises deployments persist in defense and public-safety domains where air-gapped environments prevail, yet even these sectors explore private-cloud key management to cut operational overhead.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Mode
- On-premises
- Cloud
- By End-user Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By End-user Industry
- Media and Entertainment
- BFSI
- IT and Telecommunication
- Healthcare
- Education
- Government and Public Sector
- Others End-user Industry (Manufacturing, Retail, etc.)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 37.95% of Digital Rights Management market in 2025, supported by stringent sectoral mandates such as HIPAA, SOX, and the California Consumer Privacy Act. Financial institutions and media conglomerates lead multi-DRM rollouts that integrate blockchain-anchored license reconciliation to streamline royalty settlements. U.S. cloud providers partner with Canadian broadcasters to deploy cross-border key-vault redundancy that satisfies rival sovereignty laws without sacrificing latency.
Asia Pacific is forecast to record a 15.94% CAGR through 2031, propelled by surging mobile video traffic and data-localization statutes in India, Indonesia, and Vietnam. China's directive mandating DRM receivers in new-model vehicles underscores regulatory acceleration, pushing chipset suppliers to embed cost-optimized decryption blocks. Indian telecom operators bundle DRM as a revenue-sharing value-add for independent filmmakers, while Korean edtech companies secure interactive textbooks across BYOD tablets. Regional spending rises sharply as creative-industry exports require interoperable rights management to monetize globally.
Europe's steady progression reflects the GDPR enforcement wave and the upcoming NIS2 directive that imposes higher cyber-resilience standards on critical-infrastructure operators. Media regulators encourage multi-DRM cooperation to standardize cross-border streaming, aiding pan-European content portals. Southern European broadcasters transition from legacy CAS smart-cards to converged DRM, trimming conditional-access costs by 30%. Meanwhile, emerging hubs in South America and Africa benefit from falling cloud-CDN pricing, adopting turnkey DRM to curb illegal IPTV services and protect locally produced drama series. These regions contribute incremental but rising shares as handset penetration and fiber rollout gather pace.
List of Companies Covered in this Report:
- Adobe Inc.
- Microsoft Corporation
- Google LLC (Widevine)
- Apple Inc.
- Oracle Corporation
- IBM Corporation
- Amazon Web Services Inc. (AWS Elemental)
- Dell Technologies Inc.
- SAP SE (NextLabs Inc.)
- Seclore Technology Pvt Ltd
- Fasoo Inc.
- Irdeto B.V.
- OpenText Corporation
- Locklizard Limited
- Vitrium Systems Inc.
- Bynder B.V.
- CapLinked Inc.
- Digify Pte Ltd
- FADEL Partners Inc.
- ArtistScope Pty Ltd
- Widevine Technologies Inc. (legacy)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of OTT video and streaming subscriptions
- 4.2.2 BYOD and remote-work data-security mandates
- 4.2.3 Rising digital-IP litigation and penalties
- 4.2.4 Government push for data-sovereignty compliance
- 4.2.5 Blockchain-anchored smart contracts for content monetisation
- 4.2.6 Generative-AI-driven piracy deepfakes escalating DRM demand
- 4.3 Market Restraints
- 4.3.1 Persistent device/format incompatibilities
- 4.3.2 User-experience backlash over intrusive controls
- 4.3.3 Open-source watermarking challenging proprietary DRM
- 4.3.4 Quantum-computing threat to current encryption standards
- 4.4 Industry Value--Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 On-premises
- 5.2.2 Cloud
- 5.3 By End-user Enterprise Size
- 5.3.1 Small and Medium Enterprises (SMEs)
- 5.3.2 Large Enterprises
- 5.4 By End-user Industry
- 5.4.1 Media and Entertainment
- 5.4.2 BFSI
- 5.4.3 IT and Telecommunication
- 5.4.4 Healthcare
- 5.4.5 Education
- 5.4.6 Government and Public Sector
- 5.4.7 Others End-user Industry (Manufacturing, Retail, etc.)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Kenya
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Microsoft Corporation
- 6.4.3 Google LLC (Widevine)
- 6.4.4 Apple Inc.
- 6.4.5 Oracle Corporation
- 6.4.6 IBM Corporation
- 6.4.7 Amazon Web Services Inc. (AWS Elemental)
- 6.4.8 Dell Technologies Inc.
- 6.4.9 SAP SE (NextLabs Inc.)
- 6.4.10 Seclore Technology Pvt Ltd
- 6.4.11 Fasoo Inc.
- 6.4.12 Irdeto B.V.
- 6.4.13 OpenText Corporation
- 6.4.14 Locklizard Limited
- 6.4.15 Vitrium Systems Inc.
- 6.4.16 Bynder B.V.
- 6.4.17 CapLinked Inc.
- 6.4.18 Digify Pte Ltd
- 6.4.19 FADEL Partners Inc.
- 6.4.20 ArtistScope Pty Ltd
- 6.4.21 Widevine Technologies Inc. (legacy)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment