

|
시장보고서
상품코드
2123134
전기 및 전자 시험 장비 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Electrical And Electronic Test Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
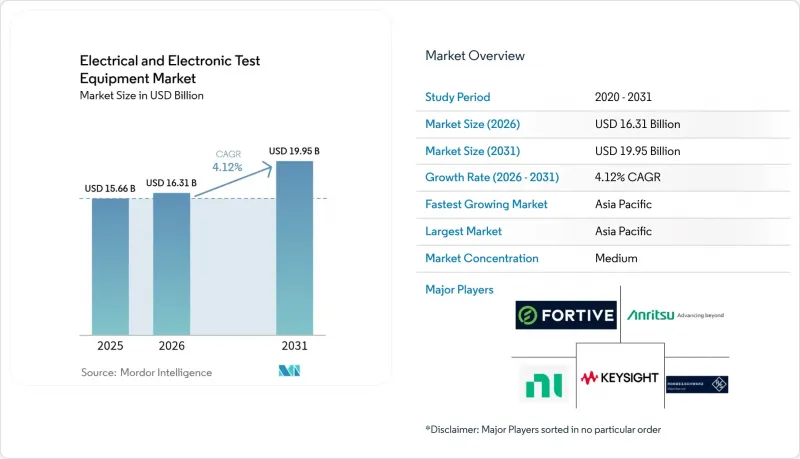
에 의하면, 전기 및 전자 시험 기기 시장 규모는 2025년 156억 6,000만 달러로 평가되었고, 2026년에는 163억 1,000만 달러로 추정되고, 2026-2031년 CAGR 4.12%로 성장을 지속할 전망이며, 2031년까지 199억 5,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형별(오실로스코프, 스펙트럼 분석기, 신호 발생기 등), 폼 팩터별(데스크톱형, 휴대용, 모듈형), 용도 단계별(연구 개발, 제조, 설치, 규정 준수), 최종 사용자 산업별(통신, 반도체, 자동차, 항공우주, 소비자 가전 등), 지역별로 분류되어 있습니다. 시장 전망 금액(달러) 기준으로 제시되어 있습니다.
세계의 전기 및 전자 시험 장비 시장 동향 및 인사이트
5G 및 첨단 무선 기술 확산의 물결
세계 5G 인프라의 확장으로 인해 mm파 및 6GHz 미만 주파수 대역을 지원하는 분석기, 신호 발생기 및 무선 전송 테스트실에 대한 전례 없는 수요가 발생하고 있습니다. 통신 사업자들은 점점 더 혼잡해지는 주파수 대역에서 빔 포밍, 캐리어 애그리게이션 및 위성 백홀의 성능을 검증해야 합니다. 현재 측정 장비에는 도플러 효과, GNSS 타이밍 및 비지상파 네트워크의 지연을 시뮬레이션할 수 있는 기능이 요구되고 있으며, 이는 기존의 지상파 RF 측정 장비로는 대응할 수 없는 과제입니다. 각 벤더사는 소비자 기기 제조업체에게 중요한 요건인 ‘무간섭 구역’의 정확도를 유지하면서, 필요한 설치 면적을 축소한 콤팩트한 CATR(캐리어 어그리게이션 테스트 룸) 시리즈를 출시하고 있습니다. 또한, 제조 공장 및 물류 허브에서의 사설 네트워크 도입으로 인해 수요가 발생하고 있습니다. 이러한 환경에서는 스펙트럼 공존과 매우 높은 신뢰성이 요구되므로, 테스트 랩에는 새로운 검증 부담이 부과되고 있습니다. 이러한 요인들이 맞물려 무선 규격이 5G-Advanced 및 초기 단계의 6G 연구로 진화하는 가운데, 전기 및 전자 시험 장비 시장의 성장세가 유지되고 있습니다.
첨단 노드 반도체의 복잡화
3nm 및 그보다 미세한 노드 제조에서는 칩 제조업체들이 멀티다이 패키징이나 칩렛 아키텍처를 채택함에 따라 테스트 벡터의 수가 비약적으로 증가합니다. 업계 단체인 SEMI는 2024년 반도체 테스트 장비 매출을 67억 달러로 예측하고 있으며, 디바이스의 복잡화에 따라 2025년에는 30.3%의 성장이 예상됩니다. 테라다인(Teradyne)과 그 파트너 기업들은 현재 실리콘 포토닉스 웨이퍼의 양면을 한 번의 패스로 검사하여, 코패키징된 광 소자의 사이클 타임을 대폭 단축하고 있습니다. 고대역폭 메모리 스택, AI 가속기, 온패키지 트랜시버에는 엄격한 열 제어와 멀티 기가비트 인터페이스 지원이 요구되어, 기존 ATE(자동 테스트 장비)의 한계를 뛰어넘고 있습니다. 프로브 카드 공급업체인 FormFactor와 Technoprobe는 차세대 콘택터 공급을 확보하기 위해 Advantest로부터 전략적 투자를 받았습니다. 설비 투자 증가는 대상 워크로드를 확대함으로써 전기 및 전자 테스트 장비 시장의 장기적인 성장을 뒷받침하고 있습니다.
높은 설비 투자 비용과 렌탈로의 전환
주력 제품인 5G 및 반도체용 ATE 플랫폼은 대당 100만 달러를 초과하는 경우도 있어 설비 투자 예산에 부담을 주고 있습니다. 고객들은 렌탈이나 구독 모델을 점점 더 많이 선택하고 있습니다. Electro Rent사는 이러한 수요에 부응하기 위해 12억 달러 상당의 재고를 유지하고 있습니다. 미국 장비 리스·금융 협회(ELFA)는 2024년에는 장비 취득의 54%가 금융을 통해 이루어질 것으로 예측하고 있으며, 2030년까지 ‘Equipment-as-a-Service(EaaS)’가 연평균 성장률(CAGR) 50%로 성장할 것으로 전망하고 있습니다. 지속적인 수익은 공급업체에게 장기적인 이점이 되지만, 단기적인 하드웨어 판매는 정체되어 전기 및 전자 시험 장비 시장 전체의 성장을 둔화시키고 있습니다.
부문 분석
전기 및 전자 시험 장비 시장에서 오실로스코프 시장 규모는 2025년에 46억 1,000만 달러에 달하여 총 매출의 29.45%라는 압도적인 점유율을 차지했습니다. 오실로스코프는 연구 개발(R&D), 검증, 문제 해결에 여전히 필수적이지만, 설계가 70GHz를 초과함에 따라 대역폭 상한선과 프로토콜 디코딩 깊이가 차별화 요인으로 작용하고 있습니다. RF 및 마이크로파 계측기는 5G 비지상파 네트워크, 위성 IoT, 자동차용 레이더 수요에 힘입어 연평균 성장률(CAGR) 4.63%로 확대되고 있습니다. 실시간 트리거 기능을 갖춘 스펙트럼 분석기나 2GHz의 변조 대역폭을 지원하는 신호 발생기는 실험실에서 현장 사용으로 점차 전환되고 있습니다. 40GHz를 지원하는 USB 전원 공급형 VNA400과 같은 휴대용 벡터 네트워크 분석기는 소형화가 더 이상 성능을 저해하지 않는다는 것을 입증하고 있습니다.
반도체 ATE 시장은 팹 확장에 따른 주기적인 수요에 좌우되지만, 핀 수를 늘리고 멀티사이트 테스트를 촉진하는 치플렛 아키텍처의 혜택을 받고 있습니다. 환경 스트레스 시험기 및 전기 안전 시험기는 특히 배터리 구동형 소비자 가전 기기에서 IEC 및 UL 규격의 강화로 인해 수요가 증가하고 있습니다. 광학 및 전기 기술의 융합으로, 단일 워크플로우에서 삽입 손실, 아이 다이어그램, RF 임페어먼트를 측정하는 하이브리드 테스터가 등장하여 데이터센터 내 코패키지드 옵틱스에 대한 수요를 충족시키고 있습니다. 전반적으로 일부 변동은 있으나, 제품의 다양화가 전기 및 전자 시험 장비 시장의 수익 안정성을 뒷받침하고 있습니다.
벤치탑형 플랫폼은 벤치마크 수준의 정밀도, 직관적인 전면 패널, 견고한 입력 보호 기능을 갖추고 있으며, 2025년 매출의 47.12%를 차지했습니다. 이러한 플랫폼은 랙 밀도보다 유연성이 중시되는 초기 설계 단계나 대학 연구실에서 주류를 이루고 있습니다. 한편, 모듈형 PXI 시스템은 사용자가 병렬 테스트를 위해 동기화된 소프트웨어 정의 채널을 선호함에 따라 연평균 성장률(CAGR) 5.02%로 가장 빠르게 성장하고 있습니다. 공장의 품질 검사 스테이션 디지털화와 전환 주기 단축이 진행됨에 따라, PXI 구성에 기인한 전기 및 전자 시험 장비 시장 규모는 2031년까지 51억 8,000만 달러를 넘어설 것으로 예측됩니다.
NI는 자사 브랜드로 600종 이상의 PXI 모듈을, 더 광범위한 생태계 전체에서는 1,500종 이상을 라인업하고 있으며, 엔지니어들에게 RF, 혼합 신호, 파워 카드 등 레고와 같은 다채로운 선택지를 제공합니다. ADLINK는 처리량 면에서 전용 랙 시스템에 필적하는 PXI 기반 파라메트릭 테스터를 통해 양산 라인으로의 적용을 확대되고 있습니다. 핸드헬드형 분석기는 현장 서비스, 재생에너지 발전소, 통신 타워 감사에서 공백을 메우는 역할을 하고 있으며, 현재는 즉각적인 보고서 작성이 가능한 클라우드 대시보드를 탑재하고 있습니다. 이러한 폼 팩터의 융합으로 인해 전기 및 전자 시험 장비 시장 내 건전한 경쟁이 유지되고 있습니다.
지역별 분석
북미는 국방 분야의 연구 개발, 애리조나주의 반도체 팹 확장, 그리고 5G C-밴드 구축을 배경으로 큰 시장 점유율을 차지하고 있습니다. 연방 정부의 인센티브와 공인 교정 실험실을 통해 추적성과 신속한 서비스를 중시하는 성숙한 생태계가 유지되고 있습니다. 캐나다의 통신 사업자와 전기차(EV) 스타트업 기업들도 규정 준수 서비스에 대한 수요를 더욱 끌어올리고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 5.22%를 기록하며, 2031년까지 북미와 어깨를 나란히 할 전망입니다. 중국의 국산 반도체 추진, 대만의 첨단 노드 분야 리더십, 그리고 한국의 메모리 분야 투자가 판매량 성장을 견인하고 있습니다. 동남아시아 국가들은 제조 거점으로서의 역할을 수행하며, 중가대 오실로스코프 및 PXI 랙을 위한 새로운 시장 기회를 창출하고 있습니다. Open RAN을 도입하는 인도의 통신 사업자와 고체 배터리 검증을 진행 중인 일본의 자동차 제조업체가 전기 및 전자 시험 장비 시장에 다양한 수익원을 제공합니다.
유럽에서는 자동차의 전동화, 재생에너지 목표, 디지털 주권에 대한 노력으로 설비 투자가 지속되고 있어 완만하지만 안정적인 성장이 나타나고 있습니다. 독일과 프랑스에서는 대규모 교정 및 렌탈 사업이 전개되고 있는 반면, 북유럽 국가들에서는 5G에 대한 선진적인 현장 시험이 선도적으로 이루어지고 있습니다. 동유럽의 EMS 제공업체들은 니어쇼어링 계약을 수주하며, 엔트리 레벨이면서도 네트워크 연결 기능을 갖춘 계측기에 대한 수요를 뒷받침하고 있습니다. 남미, 중동 및 아프리카는 여전히 발전 단계에 있지만 성장 잠재력이 높으며, 광업 자동화, 대규모 태양광 발전, 공항 개보수를 통해 모듈식 테스트 벤치의 첫 도입이 진행되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the electrical and electronic test equipment market size is expected to grow from USD 15.66 billion in 2025 to USD 16.31 billion in 2026 and is forecast to reach USD 19.95 billion by 2031 at 4.12% CAGR over 2026-2031.
This report is Segmented by Product Type (Oscilloscopes, Spectrum Analyzers, Signal Generators, and More), Form Factor (Benchtop, Portable, and Modular), Application Stage (R&D, Manufacturing, Installation, and Compliance), End-User Industry (Communications, Semiconductors, Automotive, Aerospace, Consumer Electronics, and More), and Geography. Market Forecasts in Value (USD).
Global Electrical And Electronic Test Equipment Market Trends and Insights
5G and Advanced Wireless Deployment Wave
Global 5G infrastructure expansion is driving unprecedented demand for millimeter-wave and sub-6 GHz analyzers, generators and over-the-air chambers. Operators need to validate beamforming, carrier aggregation and satellite backhaul performance across increasingly crowded spectrum allocations. Equipment must now simulate Doppler effects, GNSS timing and non-terrestrial network latency, tasks that conventional terrestrial RF sets cannot handle. Vendors are launching compact CATR ranges that shrink required floor space while retaining quiet-zone fidelity, a key need for consumer-device makers. Demand also flows from private-network deployments in manufacturing plants and logistics hubs, where spectral coexistence and ultra-reliability place fresh verification burdens on test labs. These factors collectively sustain momentum for the electrical and electronic test equipment market as wireless standards evolve toward 5G-Advanced and early 6G research.
Advanced-Node Semiconductor Complexity
Fabricating 3 nm and finer nodes multiplies test vectors as chipmakers adopt multi-die packaging and chiplet architectures. Industry association SEMI forecasts USD 6.7 billion in semiconductor test-equipment sales for 2024, with a 30.3% lift expected in 2025 as device complexity rises. Teradyne and partners now probe both sides of silicon-photonics wafers in one pass, slashing cycle times for co-packaged optics. High-bandwidth memory stacks, AI accelerators and on-package transceivers require tight thermal control and multi-gigabit interface coverage, pushing legacy ATE beyond its limits. Probe-card vendors FormFactor and Technoprobe have gained strategic investment from Advantest to secure next-gen contactor supply. The rising capital spend underpins long-term growth for the electrical and electronic test equipment market by widening addressable workloads.
High Capital Cost and Shift to Rentals
Flagship 5G or semiconductor ATE platforms can exceed USD 1 million apiece, straining capex budgets. Customers increasingly choose rental or subscription models; Electro Rent maintains USD 1.2 billion of inventory to meet these needs. The U.S. Equipment Leasing and Finance Association projects that 54% of equipment acquisitions will be financed in 2024 and expects Equipment-as-a-Service to grow 50% CAGR through 2030. While recurring revenue benefits vendors long term, near-term hardware sales flatten, tempering overall expansion of the electrical and electronic test equipment market.
Other drivers and restraints analyzed in the detailed report include:
- EV and Power-Electronics Test Needs
- AI/ML-Assisted Automated Testing
- Low-Cost Asian Vendor Price Pressure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The electrical and electronic test equipment market size for oscilloscopes stood at USD 4.61 billion in 2025, translating to a dominant 29.45% slice of total revenue. Oscilloscopes remain indispensable across R&D, validation, and troubleshooting, yet bandwidth ceilings and protocol-decode depth are now differentiators as designs push beyond 70 GHz. RF and microwave instruments are expanding at a 4.63% CAGR thanks to 5G non-terrestrial networks, satellite IoT, and automotive radar. Spectrum analyzers with real-time triggers and signal generators capable of 2 GHz modulation bandwidth are moving from lab to field use. Portable vector-network analyzers such as the 40 GHz USB-powered VNA400 are proof that miniaturization no longer compromises performance.
Semiconductor ATE faces cyclical buying tied to fab expansions but benefits from chiplet architectures that raise pin counts and drive multisite test. Environmental-stress chambers and electrical-safety testers are getting a lift from stricter IEC and UL updates, especially in battery-powered consumer devices. Optical-electrical convergence is spawning hybrid testers that measure insertion loss, eye diagrams, and RF impairments in a single workflow, meeting data-center demand for co-packaged optics. Overall, product diversification underpins revenue stability for the electrical and electronic test equipment market despite pockets of volatility.
Benchtop platforms deliver benchmark accuracy, intuitive front panels and robust input protection, securing 47.12% of 2025 revenue. They dominate early-stage design and university labs, where flexibility outranks rack density. Modular PXI systems, however, are climbing fastest with a 5.02% CAGR as users favor synchronized, software-defined channels for parallel test. The electrical and electronic test equipment market size attributed to PXI setups is forecast to exceed USD 5.18 billion by 2031 as factories digitize quality stations and shorten changeover cycles.
NI counts more than 600 PXI modules under its brand and 1,500 across the broader ecosystem, giving engineers a Lego-like palette of RF, mixed-signal, and power cards. ADLINK extends reach into mass-production lines with PXI-based parametric testers that rival proprietary rack systems on throughput. Handheld analyzers fill gap-filling tasks in field service, renewable-energy farms, and telecom tower audits, now featuring cloud dashboards for instant report generation. This convergence of form factors sustains healthy competition inside the electrical and electronic test equipment market.
Complete Report Scope:
- By Product Type
- Oscilloscopes
- Spectrum and Network Analyzers
- Signal Generators
- Semiconductor Automatic Test Equipment (ATE)
- RF and Microwave Test Equipment
- Data Acquisition (DAQ) Systems
- Electrical and Environmental Safety Test
- By Form Factor
- Benchtop
- Portable / Hand-held
- Modular / PXI / PC-based
- By Application Stage
- Design and R&D
- Manufacturing and Production
- Installation and Maintenance
- Certification and Compliance
- By End-user Industry
- Communications and Networking
- Semiconductors and Computing
- Automotive and Electric Vehicles
- Aerospace and Defense
- Consumer Electronics and Appliances
- Industrial and Energy
- Healthcare and Life Sciences
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated significant share on the back of defense R&D, fab expansions in Arizona and 5G C-band build-outs. Federal incentives and accredited calibration labs sustain a mature ecosystem that values traceability and rapid service. Canadian telecom carriers and electric-vehicle startups add incremental demand for compliance services.
Asia-Pacific is on track for a 5.22% CAGR and will likely approach parity with North America by 2031. China's push for indigenous semiconductors, Taiwan's leadership in advanced nodes and South Korean investments in memory assist volume growth. Southeast Asian nations provide a manufacturing off-load valve, creating greenfield opportunities for mid-range oscilloscopes and PXI racks. Indian telcos embracing Open RAN and Japanese automakers validating solid-state batteries add diverse revenue streams to the electrical and electronic test equipment market.
Europe shows moderate but stable growth as automotive electrification, renewable-energy targets, and digital-sovereignty initiatives keep capex flowing. Germany and France host significant calibration and rental operations, while Nordic nations pioneer 5G advanced field trials. Eastern European EMS providers attract near-shoring contracts, bolstering demand for entry-level but network-connected instruments. South America and the Middle East and Africa remain nascent yet promising, with mining automation, utility-scale solar, and airport upgrades enabling first-time installations of modular test benches.
- Keysight Technologies Inc.
- Rohde and Schwarz GmbH and Co. KG
- Fortive Corporation (Fluke, Tektronix)
- National Instruments Corporation (NI)
- Anritsu Corporation
- Teledyne LeCroy Inc.
- Yokogawa Test and Measurement Corporation
- Teradyne Inc.
- Advantest Corporation
- Chauvin Arnoux Group
- VIAVI Solutions Inc.
- EXFO Inc.
- BandK Precision Corporation
- Rigol Technologies Co., Ltd.
- GW Instek (Good Will Instrument Co., Ltd.)
- Hioki E.E. Corporation
- Chroma ATE Inc.
- Cobham Advanced Electronic Solutions
- Spectrum Instrumentation GmbH
- Signal Hound Inc.
- Pico Technology Ltd.
- Microchip Technology Inc. (Microsemi Timing Systems)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 5G and Advanced Wireless Deployment Wave
- 4.2.2 Advanced-Node Semiconductor Complexity
- 4.2.3 EV and Power-Electronics Test Needs
- 4.2.4 AI/ML-Assisted Automated Testing
- 4.2.5 Ultra-Wide-Bandgap Device Characterization
- 4.2.6 IoT Cyber-Security Compliance Mandates
- 4.3 Market Restraints
- 4.3.1 High Capital Cost and Shift to Rentals
- 4.3.2 Low-Cost Asian Vendor Price Pressure
- 4.3.3 Precision-Component Supply Shortages
- 4.3.4 Right-to-Repair Curtailing Proprietary Protocols
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
- 4.8 Assessment of Key Macroeconomic Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Oscilloscopes
- 5.1.2 Spectrum and Network Analyzers
- 5.1.3 Signal Generators
- 5.1.4 Semiconductor Automatic Test Equipment (ATE)
- 5.1.5 RF and Microwave Test Equipment
- 5.1.6 Data Acquisition (DAQ) Systems
- 5.1.7 Electrical and Environmental Safety Test
- 5.2 By Form Factor
- 5.2.1 Benchtop
- 5.2.2 Portable / Hand-held
- 5.2.3 Modular / PXI / PC-based
- 5.3 By Application Stage
- 5.3.1 Design and R&D
- 5.3.2 Manufacturing and Production
- 5.3.3 Installation and Maintenance
- 5.3.4 Certification and Compliance
- 5.4 By End-user Industry
- 5.4.1 Communications and Networking
- 5.4.2 Semiconductors and Computing
- 5.4.3 Automotive and Electric Vehicles
- 5.4.4 Aerospace and Defense
- 5.4.5 Consumer Electronics and Appliances
- 5.4.6 Industrial and Energy
- 5.4.7 Healthcare and Life Sciences
- 5.4.8 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Netherlands
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Keysight Technologies Inc.
- 6.4.2 Rohde and Schwarz GmbH and Co. KG
- 6.4.3 Fortive Corporation (Fluke, Tektronix)
- 6.4.4 National Instruments Corporation (NI)
- 6.4.5 Anritsu Corporation
- 6.4.6 Teledyne LeCroy Inc.
- 6.4.7 Yokogawa Test and Measurement Corporation
- 6.4.8 Teradyne Inc.
- 6.4.9 Advantest Corporation
- 6.4.10 Chauvin Arnoux Group
- 6.4.11 VIAVI Solutions Inc.
- 6.4.12 EXFO Inc.
- 6.4.13 BandK Precision Corporation
- 6.4.14 Rigol Technologies Co., Ltd.
- 6.4.15 GW Instek (Good Will Instrument Co., Ltd.)
- 6.4.16 Hioki E.E. Corporation
- 6.4.17 Chroma ATE Inc.
- 6.4.18 Cobham Advanced Electronic Solutions
- 6.4.19 Spectrum Instrumentation GmbH
- 6.4.20 Signal Hound Inc.
- 6.4.21 Pico Technology Ltd.
- 6.4.22 Microchip Technology Inc. (Microsemi Timing Systems)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


