

|
시장보고서
상품코드
2124556
전기 시험 장비 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Electrical Test Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 전기 시험 장비 시장 규모는 2026년에 173억 1,000만 달러에서 2031년까지 231억 5,000만 달러에 이르고, CAGR은 5.99%를 나타낼 전망입니다.
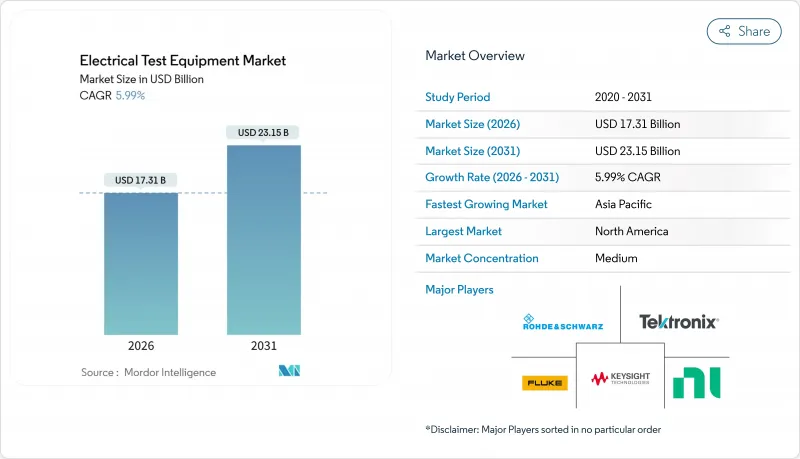
본 보고서는 장비의 이동성(고정형, 휴대형), 제품 카테고리(오실로스코프, 멀티미터 등), 시험 용도(전압, 성능, 시운전, 예방 정비, 규정 준수, 교정), 산업용도(에너지, 항공우주, 제조업, 자동차 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 전기 시험 장비 시장 동향 및 인사이트
전 세계 전기 안전 규제의 강화
세계 규제 당국은 절연 조정 기준을 상향 조정하고 전기 안전 프로토콜에 사이버 보안 점검을 통합하고 있으며, 이로 인해 제조업체와 최종 사용자 모두 보유한 계측 장비를 업데이트해야 하는 상황에 처해 있습니다. 2024년 1월에 발효된 IEC 61010-1 제4.0판에서는 1,000 V를 초과하는 장비의 절연 간격 및 표면 간격이 상향 조정됨에 따라, 공급업체는 외장 재설계를 해야만 했으며, 고객은 이미 도입한 장비에 대한 재교정을 수행해야 하는 상황이 되었습니다. 미국에서는 UL 9540A에 따라 배터리 에너지 저장 시스템에 대한 다단계 열폭주 검증이 의무화된 결과, 인증 시 테스터 이용률이 3배로 증가했습니다. 유럽연합(EU)은 저전압 지침을 개정하여 IEC 62443에 기반한 부품의 보안 인증을 의무화하고, 절연 시험을 사이버 보안 감사와 연계했습니다. 가동 중단으로 인한 손실이 계측기 비용을 상회하는 데이터센터나 제약 시설에서는 장비 교체 수요가 극히 높아지고 있습니다. 그 결과, 견고한 케이스와 보안이 강화된 펌웨어를 갖춘 휴대용 안전 분석기의 출하 대수는 두 자릿수 성장을 기록하고 있습니다.
재생에너지 설비의 확대
대규모 태양광 발전, 풍력 발전 및 이에 연계된 배터리 자산으로 인해, 고조파, 전력 품질, 절연 검증이 필요한 그리드 에지 테스트 지점이 급증하고 있습니다. 미국 에너지부의 ‘그리드 복원력 및 혁신 파트너십(GRIP)’ 프로그램은 송전망 업그레이드에 34억 6,000만 달러를 배정하고 있으며, 50차 고조파까지의 서브사이클 전압 강하를 감지할 수 있는 분석기의 사용을 규정하고 있습니다. 북해의 해상 풍력 발전소에는 525 kV의 HVDC 링크가 도입되어 있으며, 선상 변환기 스테이션의 케이블에는 Megger사의 IDAX 350과 같은 절연 시험기가 필요합니다. 중국의 GB/T 36547-2024 표준에서는 10 MWh를 초과하는 모든 그리드 저장 시설에 대해 표준화된 성능 시험의 실시가 의무화되어 있으며, 이로 인해 국내 재생에너지 부하에 대한 수요가 증가하고 있습니다. 이러한 정책에 힘입어 전기 시험 장비 시장 전반에서 고전압·고정밀 휴대용 계측기에 대한 지속적인 투자가 촉진되고 있습니다.
계측기 구입 비용의 높음
10 기가헤르츠급 오실로스코프는 10만 달러가 넘는 가격대여서, 많은 지역의 실험실에서는 여전히 감당하기 어려운 수준이며, 이는 동남아시아와 남미의 현대화 진전을 지연시키고 있습니다. 각 벤더들은 테크트로닉스의 MSO 2 시리즈(1,200달러)와 같은 저사양 모델을 시험적으로 출시하고 있지만, 200MHz의 대역폭으로는 그 용도가 가전제품 수리에 국한될 수밖에 없습니다. 에머슨 테스트 앤드 메저먼트(Emerson Test and Measurement)의 PXI 수주 중 운영 리스가 현재 34%를 차지하고 있어, 노후화 위험이 구매자에서 공급업체로 이전되고 있습니다. 그럼에도 불구하고, 인도의 20% 기본 관세와 같은 관세 조치로 인해 고가 분석기의 입고 비용은 여전히 높은 수준을 유지하고 있습니다. 그 결과, 예산 제약으로 인해 혼합된 장비군의 수명 주기가 장기화되어 전기 시험 장비 시장의 단기적인 업그레이드가 제한되고 있습니다.
부문별 분석
2025년, 전기 시험 장비 시장에서 휴대용 장비의 점유율은 61.73%를 차지했습니다. 유틸리티체, 도급업체, 재생에너지 설치업체들이 시운전 중 회로의 전원을 차단할 필요가 없는 배터리 구동 장치를 선호함에 따라, 이 부문은 2031년까지 연평균 성장률(CAGR) 7.12%를 나타낼 것으로 예측됩니다. Fluke사의 무게 4.2kg인 전력 분석기 ‘Norma 6000’은 현장에서 실험실 수준의 정밀도를 실현하는 좋은 예이며, 한편 Rohde & Schwarz사의 8시간 구동이 가능한 핸드헬드 오실로스코프는 자동차 정비 공장에서 보급이 확대되고 있습니다. 반도체 제조 공장에서는 환경 제어가 최우선시되므로 고정형 장비의 중요성은 여전히 높지만, 견고한 케이스와 IEC 61010-1 낙하 시험 규격 준수를 통해 휴대용 장비의 이용 사례가 확대되고 있습니다.
휴대용 파형 발생기의 액세서리 생태계에는 무선 프로브, 클라우드 대시보드, 그리고 기업의 자산 관리 소프트웨어와 원활하게 통합되는 엣지형 AI 안전 기능이 포함되어 있습니다. 그 결과, 조달 프레임워크에서는 단순한 정확도뿐만 아니라 종합적인 연결성과 사이버 보안이 점점 더 중요시되고 있습니다. 중국 경쟁사들의 영향으로 2024년 평균 판매 가격이 8% 하락함에 따라, 프리미엄 브랜드들은 이익 마진을 지키기 위해 교정 바우처와 펌웨어 잠금 해제 코드를 번들로 제공하며, 이를 통해 전기 시험 장비 시장에서 차별화를 유지하고 있습니다.
멀티미터와 클램프 미터는 2025년 매출의 28.74%를 차지했으나, 저비용 신규 진출기업들로 인한 가격 하락 압력에 직면해 있습니다. 한편, 회생형 전자 부하는 절대값은 작지만 연평균 성장률(CAGR) 6.33%를 나타낼 것으로 예측되어, 전체 카테고리 중 가장 높은 성장률을 보일 것으로 전망됩니다. EA Elektro-Automatik사의 에너지 회수율 96%를 자랑하는 모델을 통해, 한 유럽 배터리 연구소는 연간 전력 소비량을 1.2 GWh 절감하는 데 성공했습니다. 오실로스코프 시장은 양극화되어 있으며, 2,000달러 미만의 기종이 교육 및 수리 시장에서 지지를 얻는 반면, 5만 달러의 혼합 신호 모델이 항공우주 프로그램의 기반을 뒷받침하고 있습니다.
실리콘 카바이드(SiC) 구동 장치가 HVAC(난방·환기·공조) 및 산업용 자동화 분야에 보급됨에 따라 전력 분석기에 대한 수요가 다시 증가하고 있습니다. 반면, 사용자가 교정 주기를 18개월로 연장함에 따라 안전 시험 장비는 상품화가 진행되고 있습니다. EV 및 그리드 스토리지를 위한 배터리 전용 시험 장비에 대한 수요가 급증하고 있으며, PXI 및 FPGA 플랫폼을 기반으로 한 소프트웨어 정의 파형 발생기가 노후화된 아날로그 장비를 대체하고 있습니다. 이러한 변화는 효율성, 모듈성 및 소프트웨어 확장성이 전기 시험 장비 시장의 구매 동향을 어떻게 형성하고 있는지를 보여줍니다.
지역별 분석
2025년, 북미는 전 세계 매출의 38.73%를 차지했습니다. 이는 34억 6,000만 달러 규모의 연방 정부 주도의 송전망 업그레이드와 미시간주 및 캘리포니아주의 전기차 배터리 연구소 확장에 힘입은 결과입니다. 캐나다의 그리드 규모 에너지 저장 시스템 도입이 47% 급증한 것과 멕시코의 10억 달러 규모 전기차 공장 전환이 이러한 성장세를 더욱 뒷받침하고 있습니다.
유럽의 에너지 전환 가속화는 전력 품질 및 절연 진단 도구에 대한 투자를 촉진하고 있습니다. 독일의 해상 풍력 발전 확대, 영국의 43억 달러 규모 변전소 개보수, 프랑스의 원자력 발전소 가동 기간 연장 프로젝트가 맞물려 고전압 시험 장비에 대한 수요를 높이고 있습니다. 유럽연합(EU)의 배터리 규제는 추적 가능한 에너지 소비량 측정을 의무화하고 있어, 교정된 분석기 구매를 촉진하고 있습니다.
아시아태평양은 대만의 650억 달러 규모 반도체 설비 투자, 한국의 메모리 칩 제조 공장, 그리고 국내 공급업체를 우대하는 중국의 스토리지 테스트 의무화에 힘입어 2031년까지 6.65%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 인도에서는 298억 루피의 인센티브 지급을 통해 멀티미터 및 전력 분석기를 조달하는 전자기기 공장이 더욱 유치되고 있습니다. 한편, 일본의 고체 배터리 시범 사업과 아세안(ASEAN)으로의 제조 거점 이전이 해당 지역의 구매 수요를 확대시키고 있습니다. 남미, 중동 및 아프리카의 신흥 시장은 절대적인 판매량에서는 뒤처지고 있지만, 휴대용 안전 시험기나 그리드 코드 분석기가 필요한 견실한 프로젝트 파이프라인을 바탕으로 전기 시험 장비 시장의 입지를 넓혀가고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the electrical test equipment market size was USD 17.31 billion in 2026 and is projected to reach USD 23.15 billion by 2031, registering a 5.99% CAGR.
This report is Segmented by Equipment Mobility (Stationary and Portable), Product Category (Oscilloscopes, Multimeters, and More), Testing Application (Voltage, Performance, Commissioning, Maintenance, Compliance, and Calibration), Industry Application (Energy, Aerospace, Manufacturing, Automotive, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Electrical Test Equipment Market Trends and Insights
Stricter Global Electrical-Safety Regulations
Regulators worldwide are increasing insulation-coordination thresholds and incorporating cybersecurity checks into electrical safety protocols, compelling both manufacturers and end-users to update their instrument fleets. IEC 61010-1 Edition 4.0, effective January 2024, increased clearance and creepage distances for equipment above 1 000 V, leading vendors to redesign enclosures and customers to recalibrate installed bases. In the United States, UL 9540A now mandates multi-level thermal-runaway validation for battery-energy storage systems, resulting in a threefold increase in tester utilization rates during certification. The European Union amended the Low Voltage Directive to require IEC 62443 component security attestations, tying dielectric tests to cybersecurity audits. Replacement demand is acute in data-center and pharmaceutical facilities where downtime penalties outweigh instrument cost. Consequently, portable safety analyzers with ruggedized housings and secure firmware record double-digit shipment growth.
Expansion of Renewable-Energy Installations
Utility-scale solar, wind, and co-located battery assets multiply grid-edge test points that need harmonic, power-quality, and insulation verification. The U.S. Department of Energy's Grid Resilience and Innovation Partnerships program earmarked USD 3.46 billion for transmission upgrades that specify analyzers able to capture sub-cycle voltage sags through the 50th harmonic. North Sea offshore wind farms deploy 525 kV HVDC links, requiring insulation testers such as Megger's IDAX 350 for on-board converter-station cables. China's GB/T 36547-2024 forces every grid-storage site above 10 MWh to complete standardized performance tests, boosting bids for domestic regenerative loads. These policies drive sustained investment in high-voltage, high-precision portable instruments across the electrical test equipment market.
High Acquisition Cost of Instruments
Ten-gigahertz oscilloscopes priced above USD 100 000 remain out of reach for many regional labs, slowing modernization in Southeast Asia and South America. Vendors experiment with lower-spec models such as Tektronix's MSO 2 Series at USD 1 200, yet 200 MHz bandwidth confines usage to consumer-electronics repair. Operating leases now constitute 34% of PXI orders at Emerson Test and Measurement, transferring obsolescence risk from buyers to suppliers. Nevertheless, tariffs like India's 20% basic customs duty still inflate landed cost on premium analyzers. Budget constraints therefore lengthen mixed-fleet lifecycles, limiting near-term electrical test equipment market upgrades.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of 5G and High-Speed Networks
- Rising EV Adoption and Battery-Test Demand
- Rapid Technology-Driven Obsolescence
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Portable assets represented 61.73% of the electrical test equipment market share in 2025. The segment is projected to deliver a 7.12% CAGR through 2031, as utilities, contractors, and renewable-energy installers prefer battery-powered devices that eliminate the need for de-energizing circuits during commissioning. Fluke's 4.2 kg Norma 6000 power analyzer exemplifies laboratory-grade precision on the job site, while Rohde and Schwarz's eight-hour handheld oscilloscope gains traction in automotive service bays. Stationary gear maintains relevance in semiconductor fabs where environmental control is paramount, but ruggedized housings and IEC 61010-1 drop-test compliance broaden portable use cases.
The portable wave drives accessory ecosystem includes wireless probes, cloud dashboards, and edge-AISafety features that integrate seamlessly with enterprise asset-management software. As a result, procurement frameworks are increasingly assessing total connectivity and cybersecurity, rather than raw accuracy. With average selling prices falling 8% in 2024 due to Chinese competition, premium brands are bundling calibration vouchers and firmware unlock codes to protect their margins, thereby sustaining differentiation in the electrical test equipment market.
Multimeters and clamp meters delivered 28.74% of 2025 revenue but face price erosion from low-cost entrants. Conversely, regenerative electronic loads, though smaller in absolute terms, are projected to register a 6.33% CAGR, the fastest among all categories. EA Elektro-Automatik's 96% energy-recovery models helped one European battery lab cut annual consumption by 1.2 GWh annually. Oscilloscopes polarize, with sub-USD 2 000 instruments winning education and repair markets and USD 50 000 mixed-signal editions anchoring aerospace programs.
Power analyzers see renewed demand as silicon-carbide drives penetrate HVAC and industrial automation, while safety testers commoditize as users stretch calibration to 18-month intervals. Battery-specific testers surge in demand for EVs and grid storage, and software-defined waveform generators based on PXI or FPGA platforms replace aging analog units. These shifts illustrate how efficiency, modularity, and software extensibility shape purchasing in the electrical test equipment market.
Complete Report Scope:
- By Equipment Mobility
- Stationary
- Portable
- By Product Category
- Oscilloscopes
- Multimeters and Clamp Meters
- Power Analyzers
- Electrical Safety Testers
- Battery Testing Equipment
- High-Voltage Testers
- Electronic Loads
- Signal and Function Generators
- Network and Protocol Analyzers
- Data Acquisition Systems
- By Testing Application
- Voltage Testing
- Functionality / Performance Testing
- Installation and Commissioning Testing
- Preventive Maintenance and Condition Monitoring
- Compliance and Certification Testing
- Quality Assurance and Lab Calibration
- By Industry Application
- Energy and Power
- Aerospace and Defense
- Manufacturing and Industrial Automation
- Consumer Electronics
- Oil and Gas
- Automotive and E-Mobility
- Telecommunications and IT Infrastructure
- Healthcare and Medical Devices
- Research and Academics
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 38.73% of global revenue in 2025, underpinned by USD 3.46 billion in federal transmission upgrades and expanding EV battery labs in Michigan and California. Canada's 47% surge in grid-scale storage deployments and Mexico's USD 1 billion EV plant conversion sustain additional momentum.
Europe's accelerated energy transition propels investment in power-quality and insulation-diagnostic tools. Germany's offshore wind expansion, the United Kingdom's USD 4.3 billion substation upgrades, and France's nuclear life-extension projects together elevate demand for high-voltage test gear. The European Union's Battery Regulation reinforces traceable energy-consumption metering, compelling purchase of calibrated analyzers.
Asia-Pacific is forecast to post the strongest 6.65% CAGR to 2031, driven by Taiwan's USD 65 billion semiconductor capex, South Korea's memory-chip fab, and China's storage-testing mandate favoring local suppliers. India's INR 29.8 billion incentive payouts attract additional electronics factories that procure multimeters and power analyzers, while Japan's solid-state battery pilots and ASEAN manufacturing relocations amplify regional purchasing. Emerging markets in South America, the Middle East and Africa lag in absolute volumes but register robust project pipelines that require portable safety testers and grid-code analyzers, broadening the electrical test equipment market footprint.
- Keysight Technologies, Inc.
- Rohde and Schwarz GmbH and Co. KG
- Tektronix, Inc.
- Fluke Corporation
- National Instruments Corporation
- Yokogawa Test and Measurement Corporation
- Anritsu Corporation
- Chroma ATE Inc.
- Hioki E.E. Corporation
- Megger Group Limited
- Chauvin Arnoux SA
- BandK Precision Corporation
- Viavi Solutions Inc.
- Advantest Corporation
- Teledyne LeCroy Inc.
- Good Will Instrument Co., Ltd.
- Rigol Technologies Co., Ltd.
- Mastech Group Limited
- Ideal Industries, Inc.
- Kikusui Electronics Corporation
- EA Elektro-Automatik GmbH and Co. KG
- NH Research, Inc.
- Itech Electronic Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter Global Electrical-Safety Regulations
- 4.2.2 Expansion of Renewable-Energy Installations
- 4.2.3 Proliferation of 5G and High-Speed Networks
- 4.2.4 Rising EV Adoption and Battery-Test Demand
- 4.2.5 Predictive-Maintenance-as-a-Service Uptake
- 4.2.6 Demand for Energy-Regenerative Loads
- 4.3 Market Restraints
- 4.3.1 High Acquisition Cost of Instruments
- 4.3.2 Rapid Technology-Driven Obsolescence
- 4.3.3 Shortage of Skilled Metrology Technicians
- 4.3.4 Cybersecurity Risks in Connected Devices
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment Mobility
- 5.1.1 Stationary
- 5.1.2 Portable
- 5.2 By Product Category
- 5.2.1 Oscilloscopes
- 5.2.2 Multimeters and Clamp Meters
- 5.2.3 Power Analyzers
- 5.2.4 Electrical Safety Testers
- 5.2.5 Battery Testing Equipment
- 5.2.6 High-Voltage Testers
- 5.2.7 Electronic Loads
- 5.2.8 Signal and Function Generators
- 5.2.9 Network and Protocol Analyzers
- 5.2.10 Data Acquisition Systems
- 5.3 By Testing Application
- 5.3.1 Voltage Testing
- 5.3.2 Functionality / Performance Testing
- 5.3.3 Installation and Commissioning Testing
- 5.3.4 Preventive Maintenance and Condition Monitoring
- 5.3.5 Compliance and Certification Testing
- 5.3.6 Quality Assurance and Lab Calibration
- 5.4 By Industry Application
- 5.4.1 Energy and Power
- 5.4.2 Aerospace and Defense
- 5.4.3 Manufacturing and Industrial Automation
- 5.4.4 Consumer Electronics
- 5.4.5 Oil and Gas
- 5.4.6 Automotive and E-Mobility
- 5.4.7 Telecommunications and IT Infrastructure
- 5.4.8 Healthcare and Medical Devices
- 5.4.9 Research and Academics
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Keysight Technologies, Inc.
- 6.4.2 Rohde and Schwarz GmbH and Co. KG
- 6.4.3 Tektronix, Inc.
- 6.4.4 Fluke Corporation
- 6.4.5 National Instruments Corporation
- 6.4.6 Yokogawa Test and Measurement Corporation
- 6.4.7 Anritsu Corporation
- 6.4.8 Chroma ATE Inc.
- 6.4.9 Hioki E.E. Corporation
- 6.4.10 Megger Group Limited
- 6.4.11 Chauvin Arnoux SA
- 6.4.12 BandK Precision Corporation
- 6.4.13 Viavi Solutions Inc.
- 6.4.14 Advantest Corporation
- 6.4.15 Teledyne LeCroy Inc.
- 6.4.16 Good Will Instrument Co., Ltd.
- 6.4.17 Rigol Technologies Co., Ltd.
- 6.4.18 Mastech Group Limited
- 6.4.19 Ideal Industries, Inc.
- 6.4.20 Kikusui Electronics Corporation
- 6.4.21 EA Elektro-Automatik GmbH and Co. KG
- 6.4.22 NH Research, Inc.
- 6.4.23 Itech Electronic Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


