|
시장보고서
상품코드
2123253
인도의 전동 릭샤 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)India Electric Rickshaw - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
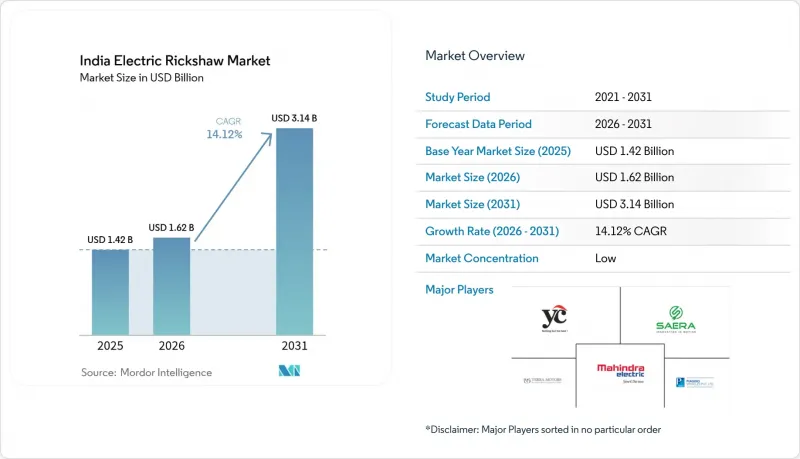
인도 전동 릭샤 시장 규모는 2025년에 14억 2,000만 달러로 평가되었고 2026년 16억 2,000만 달러에서 2031년까지 31억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 14.12%를 나타낼 전망입니다.
본 보고서는 차량 유형(승객 운송용 등), 출력(1kW 이하 등), 배터리 유형(납산 배터리 등), 배터리 용량(3kWh 이하 및 그 이상), 충전 방식(플러그인 충전 및 기타), 소유 형태(개인 소유·운전자 및 기타), 그리고 주(우타르 프라데시 주, 델리 및 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대수)으로 제시되어 있습니다.
인도 전동 릭샤 시장 동향 및 인사이트
FAME-II 보조금 연장 및 각 주의 인센티브가 2급 도시에서의 보급을 가속화
연장된 FAME-II 프로그램과 ‘2024년 전기 모빌리티 촉진 계획’의 연방 차원에서의 연속성으로 인해, 대당 보조금이 유지되어 주요 대도시권 외 지역의 운전자들에게 구매 비용 장벽이 낮아졌습니다. 마하라슈트라주, 카르나타카주, 델리주에서 시행하는 구매 리베이트부터 도로세 면제에 이르는 주 정부의 추가 지원 조치로 인해 절감 효과가 누적되어, 판매 시점에서 전기 삼륜차는 내연기관(ICE) 모델과 가격 경쟁력을 갖추게 되었습니다. 보조금 규모와 등록 대수 간에는 강한 상관관계가 나타나며, 분석에 따르면 주 정부의 지원 강도가 표준편차 1단위 상승할 때마다 판매 대수가 46.16% 증가하는 것으로 밝혀졌습니다. 현지 금융 기관들은 투자 회수 기간이 단축되었다고 보고하고 있으며, 이에 따라 더 폭넓은 대출 참여가 촉진되고 있습니다. 이러한 재정적 조치들이 맞물리면서, 인도의 전기 삼륜차 시장은 비용에 민감하고 비공식 교통 수요가 급증하고 있는 2급 도시권으로 더욱 침투하고 있습니다.
급속한 도시화가 진행되는 도시에서 라스트 마일 공유 모빌리티 수요 증가
인도에서 계속 확대되고 있는 중규모 도시 네트워크에서는 대중교통의 퍼스트 마일과 라스트 마일 간의 격차를 메우기 위해 자동 릭샤에 크게 의존하고 있습니다. 전기차 모델은 휘발유나 CNG의 1km당 3-4루피에 비해 운행 비용을 0.50-0.70루피로 절감하여, 소유 운전자에게 즉각적인 수익 향상을 가져다주고 있습니다. Uber나 Rapido와 같은 공유 모빌리티 중개업체들은 지자체의 대기 오염 대책 규제와 이용자의 가격 민감도에 대응하기 위해 전기 리크샤 도입을 추진하고 있습니다. 일일 가동률이 높아 연료비 차익이 확대됨에 따라, 높은 초기 구매 비용에 대한 투자 회수 속도를 가속화하고 있습니다. 원활한 디지털 예약을 통해 자산 생산성이 향상되고 사업자의 수익성이 더욱 강화됨과 동시에, 인도 전동 삼륜차 시장 전반의 보급을 촉진하고 있습니다.
분산되고 비공식적인 자금 조달 채널이 운전자의 구매를 제약
대규모 대출 파이프라인의 부재로 인해 실질 금리는 높은 수준을 유지하고 있으며, 대출 대 평가액 비율(LTV)은 낮은 수준에 머물러 있어, 일일 운임 수입에 생계를 의존하는 개인 운전자의 도입 의욕을 저해하고 있습니다. 기술적 위험에 대한 우려로 인해 많은 대출 기관은 전기 삼륜차를 비표준 자산으로 취급하여, 운영 비용이 낮음에도 불구하고 신용 한도를 제한하고 있습니다. 비공식 대출업자들이 그 공백을 메우고는 있지만, 터무니없이 높은 이자율을 부과하고 있어 총 소유 비용(TCO)의 이점이 훼손되고 있습니다. 개발 금융 기관들은 소매 대출의 위험을 완화하기 위해 혼합 금융 풀을 제안하고 있지만, 주요 도시 이외의 지역에서는 도입이 여전히 더딘 실정입니다. 대형 은행들이 전기 삼륜차에 대한 신용 심사를 정상화할 때까지, 초기 비용 부담에 가장 민감한 부문에서는 성장이 잠재적 수준에 미치지 못할 것입니다.
부문 분석
인도 전동 릭샤 시장 점유율에서는 현재 승객 운송 부문이 지배적이며, 2025년 판매 대수의 83.45%를 차지하여 도심 공유 모빌리티의 중추적인 역할을 확고히 하고 있습니다. 혼잡한 도시 지역의 노선과 하루 종일 운행 덕분에 운전자는 1킬로미터당 불과 몇 페니에 불과한 에너지 비용을 최대한 활용할 수 있어, 이 부문의 회복력을 강화하고 있습니다. 반면, 화물 운송 부문은 온라인 소매업이 기동성이 뛰어나고 배기가스가 없는 라스트 마일 배송에 대한 수요를 끌어올리고 있어 28.10%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. Amazon India, Flipkart 및 퀵 커머스 사업자들은 주요 OEM 제조업체들과 공식적인 조달 파이프라인을 구축하여 예측 가능한 판매량 증가를 보장받고 있습니다. 냉장 차체 등 부문별 특화 설계를 통해 식품 유통 및 의약품 분야의 목표 시장이 확대되고 있습니다. 높은 적재 능력과 텔레매틱스 기능의 통합으로 화물용 전동 릭샤는 미래 도시 물류 구상에서 필수적인 요소가 되고 있습니다.
절대 수량으로 볼 때, 인도 전기 삼륜차 시장에서는 여전히 승용 모델이 주류를 이룰 전망이지만, 화물용 모델의 가치 기여도는 프리미엄 사양의 조합을 통해 꾸준히 증가할 것입니다. 상용차에 대한 세제 혜택과 2급 도시 내 전용 마이크로 풀필먼트 허브 구축을 통해 화물용 모델의 누적 보급률은 더욱 높아질 전망입니다. 도시 지역의 정체 요금이 인상됨에 따라 화물 운송 사업자들은 소형 트럭보다 전동 삼륜차를 선호하게 되어, 이 부문의 장기적인 성장 기반이 확고해질 것입니다.
출력별 인도 전동 릭샤 시장 점유율에서는 1-1.5kW 모터 부문이 선두를 차지하여, 2025년에는 총 수요의 53.90%를 차지했습니다. 이 출력 대역은 잦은 출발과 정지가 수반되는 도시 주행에 충분한 토크를 제공하면서도 배터리 수명을 절약할 수 있어 일반 승객 운송에 최적입니다. 사업자들 사이에서는 합리적인 초기 비용과 실용적인 주행 거리가 조화를 이룬 균형 잡힌 성능이 높이 평가받고 있으며, 특히 사용 빈도가 높은 도시 지역의 운영 주기에서 큰 인기를 끌고 있습니다.
대조적으로, 1.5kW를 초과하는 출력 등급의 파워트레인은 적재량 수요와 가파른 경사면 주행 요건이 높아짐에 따라 인도 전동 릭샤 시장에서 가장 빠른 성장을 기록하고 있으며, 연평균 성장률(CAGR) 30.95%로 확대되고 있습니다. 이 부문은 통합형 모터 컨트롤러 및 IP 규격 준수 케이스 등 e-액슬 기술의 발전으로 혜택을 보고 있으며, 이러한 기술은 인도의 혹독한 몬순 조건 하에서 내구성을 높여 사업자들의 차량 도입에 대한 신뢰도를 높이고 있습니다.
고출력 등급의 경우, 냉장 화물, 급경사 산악 지대, 그리고 더 빠른 이동 시간을 요구하는 프리미엄 배달 서비스를 지원합니다. 부품 공급업체들은 자석 및 고정자의 현지 생산을 추진하여 수입 부품의 비율을 줄이고 가격 수준을 안정화하고 있습니다. 단위 경제성 개선에 따라, 1.5kW 초과 등급의 인도 전기 삼륜차 시장 규모는 매출 점유율을 확대할 것으로 예상되며, 단순한 비용뿐만 아니라 성능에 초점을 맞춘 새로운 경쟁 단계가 도래할 전망입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the indian electric rickshaw market size was valued at USD 1.42 billion in 2025 and estimated to grow from USD 1.62 billion in 2026 to reach USD 3.14 billion by 2031, at a CAGR of 14.12% during the forecast period (2026-2031).
This report is Segmented by Vehicle Type (Passenger Carriers and More), Power Output ( Up To 1 KW and More), Battery Type (Lead-Acid and More), Battery Capacity (Up To 3 KWh and More), Charging Mode (Plug-In Charging and More), Ownership Model (Individual Owner-Drivers and More), and States (Uttar Pradesh, Delhi, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
India Electric Rickshaw Market Trends and Insights
FAME-II Subsidy Extension and State Incentives Accelerating Tier-II Adoption
Federal continuity between the extended FAME-II program and the Electric Mobility Promotion Scheme 2024 keeps per-vehicle subsidies intact, lowering acquisition cost barriers for drivers outside major metros. State top-ups-ranging from purchase rebates to road-tax waivers in Maharashtra, Karnataka, and Delhi-stack further savings, making electric three-wheelers price-competitive with ICE models at the point of sale. Subsidy density correlates strongly with registrations; assessments reveal a 46.16% sales uplift for each standard-deviation rise in state support intensity. Local financiers report shorter payback periods, encouraging broader credit participation. Combined, these fiscal levers push the Indian electric three-wheeler market deeper into cost-sensitive Tier-II clusters where informal transit demand is surging.
Rising Demand for Last-Mile Shared Mobility in Rapidly Urbanising Towns
India's expanding network of mid-sized cities relies heavily on auto-rickshaws to bridge first- and last-mile gaps in public transit. Electric variants cut running expenses to INR 0.50-0.70/km against INR 3-4/km for petrol or CNG, creating immediate earnings upside for owner-drivers. Shared-mobility aggregators such as Uber and Rapido are onboarding e-rickshaws to meet municipal clean-air mandates and rider price sensitivity. High daily utilization amplifies fuel-cost arbitrage, accelerating payback on the higher upfront purchase. Seamless digital booking elevates asset productivity, further reinforcing operator economics and boosting adoption across the Indian electric three-wheeler market.
Fragmented & Informal Financing Channels Constraining Driver Purchases
The lack of scale credit pipelines keeps effective interest rates high and loan-to-value ratios low, dampening uptake among independent drivers whose livelihood depends on daily fare receipts. Technology-risk perceptions lead many lenders to treat electric variants as non-standard assets, constricting credit lines despite lower running costs. Informal money-lenders bridge the gap but charge punitive rates, eroding total cost of ownership benefits. Development-finance institutions advocate blended-finance pools to de-risk retail lending, yet implementation remains slow outside major cities. Until mainstream banks normalize underwriting for electric three-wheelers, growth will undershoot potential in segments most sensitive to up-front affordability.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce Logistics Embracing Cargo E-Rickshaws for Intra-City Delivery
- Lead-Acid Battery Recycling Ecosystem Lowering Total Cost of Ownership
- Safety Concerns Over Chassis Integrity on Rural Roads
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
India electric rickshaw market share is currently dominated by the passenger carrier segment, which accounted for 83.45% of unit sales in 2025, cementing its role as the backbone of intra-city shared mobility. Dense urban routes and all-day utilization let drivers exploit penny-per-kilometer energy costs, reinforcing segment resilience. Goods carriers, however, are registering the fastest 28.10% CAGR as online retail pushes demand for nimble, emissions-free last-mile delivery. Amazon India, Flipkart, and quick-commerce players are formalizing procurement pipelines with established OEMs, ensuring predictable volume growth. Segment-specific designs such as refrigerated bodies widen addressable markets in food distribution and pharmaceuticals. Higher payload ratings and telematics integration make cargo e-rickshaws an essential piece of future city-logistics blueprints.
In absolute volume terms, passenger variants will continue to dominate the Indian electric three-wheeler market, yet the value contribution from cargo units will rise steadily through premium specification mixes. Tax breaks for commercial vehicles and dedicated micro-fulfillment hubs in Tier-II cities will push cumulative cargo penetration higher. As urban congestion charges tighten, freight operators will prefer electric three-wheelers over light trucks, cementing the segment's long-term upside.
India electric rickshaw market share by power output was led by the 1-1.5 kW motor segment, which accounted for 53.90% of total demand in 2025. This power band delivers sufficient torque for frequent stop-start city driving while conserving battery life, making it ideal for typical passenger operations. Operators value its balanced offering-affordable upfront cost with practical range-especially in high-usage urban duty cycles.
In contrast, powertrains rated above 1.5 kW are witnessing the fastest growth in the India electric rickshaw market, expanding at a 30.95% CAGR as payload demands and gradient-handling requirements rise. The segment is benefiting from advancements in e-axle technologies, including integrated motor controllers and IP-rated enclosures, which enhance durability during India's heavy monsoon conditions and boost fleet confidence.
The higher-powered bracket supports refrigerated cargo, steep-gradient hill-stations, and premium ride-hailing tiers that demand faster trip times. Component suppliers are localizing magnets and stators, cutting imported content and stabilizing price points. As unit economics improve, the Indian electric three-wheeler market size for the above-1.5 kW class is projected to widen its revenue share, ushering in a new competitiveness layer focused on performance rather than solely cost.
Complete Report Scope:
- By Vehicle Type
- Passenger Carriers
- Goods Carriers
- By Power Output
- Up to 1 kW
- 1 - 1.5 kW
- Above 1.5 kW
- By Battery Type
- Lead-Acid
- Lithium-ion (NMC/NCA)
- Lithium-ion (LFP)
- Other Chemistries (Li-Polymer, Ni-MH)
- By Battery Capacity
- Up to 3 kWh
- 3 - 6 kWh
- Above 6 kWh
- By Charging Mode
- Plug-in Charging
- Battery Swapping
- By Ownership Model
- Individual Owner-Drivers
- Fleet Operators
- Aggregators / MaaS Platforms
- By State
- Uttar Pradesh
- Delhi
- Maharashtra
- Bihar
- Rajasthan
- Karnataka
- Tamil Nadu
- Punjab
- Telangana
- Rest of India
List of Companies Covered in this Report:
- Terra Motors India Corp.
- Piaggio Vehicles Pvt. Ltd.
- Mahindra Electric Mobility Ltd.
- Kinetic Green Energy & Power Solutions Ltd.
- ATUL Auto Ltd.
- Saera Electric Auto Pvt. Ltd.
- YC Electric Vehicle
- Goenka Electric Motor Vehicles Pvt. Ltd.
- Udaan E-Rickshaw
- Thukral Electric Bikes
- Mini Metro EV LLP
- E-Ashwa Automotive Pvt. Ltd.
- CityLife EV
- Adapt Motors Pvt. Ltd.
- Vani Electric Vehicles Pvt. Ltd. (Jezza Motors)
- Omega Seiki Mobility
- Euler Motors
- Lohia Auto Industries
- Bajaj Auto Ltd. (Electric 3W Division)
- Altigreen Propulsion Labs
- Gayam Motor Works
- Lectrix EV
- Saarthi E-Rickshaw
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 FAME-II Subsidy Extension and State Incentives Accelerating Tier-II Adoption
- 4.2.2 Rising Demand for Last-Mile Shared Mobility in Rapidly Urbanising Towns
- 4.2.3 E-Commerce Logistics Embracing Cargo E-Rickshaws for Intra-City Delivery
- 4.2.4 Lead-Acid Battery Recycling Ecosystem Lowering Total Cost of Ownership
- 4.2.5 Battery-as-a-Service Subscription Models Reducing Up-front Capex
- 4.2.6 Mandatory Phase-Out of ICE Three-Wheelers in Delhi-NCR by 2030
- 4.3 Market Restraints
- 4.3.1 Fragmented & Informal Financing Channels Constraining Driver Purchases
- 4.3.2 Safety Concerns Over Chassis Integrity on Rural Roads
- 4.3.3 Quality Variability in Unorganised Lead-Acid Battery Supply Chain
- 4.3.4 Slow Roll-Out of Swappable Battery Standards Hindering Interoperability
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory & Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Buyers
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Passenger Carriers
- 5.1.2 Goods Carriers
- 5.2 By Power Output
- 5.2.1 Up to 1 kW
- 5.2.2 1 - 1.5 kW
- 5.2.3 Above 1.5 kW
- 5.3 By Battery Type
- 5.3.1 Lead-Acid
- 5.3.2 Lithium-ion (NMC/NCA)
- 5.3.3 Lithium-ion (LFP)
- 5.3.4 Other Chemistries (Li-Polymer, Ni-MH)
- 5.4 By Battery Capacity
- 5.4.1 Up to 3 kWh
- 5.4.2 3 - 6 kWh
- 5.4.3 Above 6 kWh
- 5.5 By Charging Mode
- 5.5.1 Plug-in Charging
- 5.5.2 Battery Swapping
- 5.6 By Ownership Model
- 5.6.1 Individual Owner-Drivers
- 5.6.2 Fleet Operators
- 5.6.3 Aggregators / MaaS Platforms
- 5.7 By State
- 5.7.1 Uttar Pradesh
- 5.7.2 Delhi
- 5.7.3 Maharashtra
- 5.7.4 Bihar
- 5.7.5 Rajasthan
- 5.7.6 Karnataka
- 5.7.7 Tamil Nadu
- 5.7.8 Punjab
- 5.7.9 Telangana
- 5.7.10 Rest of India
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles
- 6.4.1 Terra Motors India Corp.
- 6.4.2 Piaggio Vehicles Pvt. Ltd.
- 6.4.3 Mahindra Electric Mobility Ltd.
- 6.4.4 Kinetic Green Energy & Power Solutions Ltd.
- 6.4.5 ATUL Auto Ltd.
- 6.4.6 Saera Electric Auto Pvt. Ltd.
- 6.4.7 YC Electric Vehicle
- 6.4.8 Goenka Electric Motor Vehicles Pvt. Ltd.
- 6.4.9 Udaan E-Rickshaw
- 6.4.10 Thukral Electric Bikes
- 6.4.11 Mini Metro EV LLP
- 6.4.12 E-Ashwa Automotive Pvt. Ltd.
- 6.4.13 CityLife EV
- 6.4.14 Adapt Motors Pvt. Ltd.
- 6.4.15 Vani Electric Vehicles Pvt. Ltd. (Jezza Motors)
- 6.4.16 Omega Seiki Mobility
- 6.4.17 Euler Motors
- 6.4.18 Lohia Auto Industries
- 6.4.19 Bajaj Auto Ltd. (Electric 3W Division)
- 6.4.20 Altigreen Propulsion Labs
- 6.4.21 Gayam Motor Works
- 6.4.22 Lectrix EV
- 6.4.23 Saarthi E-Rickshaw
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment