

|
시장보고서
상품코드
2123297
자동차용 파워 모듈 패키징 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Power Module Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
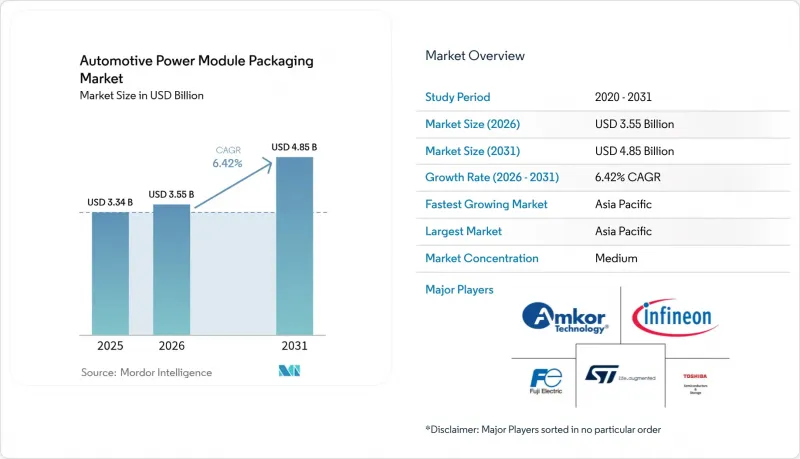
자동차용 파워 모듈 패키징 시장 규모는 2026년에 35억 5,000만 달러로 추정되고 있어 2025년 33억 4,000만 달러에서 확대해, 2031년에는 48억 5,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 6.42%가 될 것으로 전망됩니다.
본 보고서는 모듈 유형(IPM, SiC 파워 모듈, GaN 파워 모듈 등), 정격 전력(600V 이하, 601-1200V 등), 패키징 기술(와이어 본딩, 와이어 본딩리스/파워 오버레이 등),구동 방식(BEV, HEV, PHEV, FCEV), 차종(승용차 등), 용도(트랙션 인버터, 차량용 충전기, DC-DC 컨버터, 보조/공조/EPS), 지역별로 분류되어 있습니다.
전 세계 자동차용 파워 모듈 패키징 시장 동향 및 인사이트
EV 및 HEV 생산 대수의 급증
2024년, 전 세계 배터리식 전기차 및 하이브리드 차량의 생산 대수는 급증하여, SiC 수요의 70% 이상을 이미 자동차 용도가 차지하고 있었습니다. 테슬라의 ‘사이버트럭’에 탑재된 전력 변환기는 800V 플랫폼이 전압 부하를 두 배로 늘려 열 관리에 대한 요구를 더욱 높이고 있음을 보여줍니다. 보그워너(BorgWarner)와 같은 1차 공급업체들은 eProduct 매출이 전년 대비 47% 증가했다고 보고했는데, 이는 정평이 나 있는 드라이브트레인 전문 기업들이 고밀도 모듈로 자원을 전환하고 있음을 시사합니다. ZF의 300kW ‘eBeam’ 액슬을 포함한 상용차 프로그램은 내환경성이 뛰어난 패키징의 적용 범위를 더욱 확대되고 있습니다.
SiC 및 GaN 광대역 갭 디바이스로의 전환
4세대 SiC MOSFET는 현재 200°C를 초과하는 접합 온도를 견딜 수 있게 되었으며, 구리 클립, 은 소결 및 다이 직접 냉각의 필요성이 높아지고 있습니다. 인피니온은 2025년이 자동차용 GaN, 특히 차량용 충전기 및 고주파 DC-DC 컨버터 분야에서 전환점이 될 것으로 예측했습니다. SiC 기판공급 병목 현상으로 인해 200mm 웨이퍼로의 전환과 생산 능력을 안정화하기 위한 멀티 소스 계약에 대한 관심이 높아지고 있습니다.
표준화된 인증 프로토콜의 부재
파워 일렉트로닉스 공급업체들은 AEC-Q100, AEC-Q101 및 AEC-Q200에 대한 해석이 지역별 OEM마다 달랐기 때문에 반복적인 시험 과정에 직면하게 되었고, 이로 인해 시장 출시까지의 기간이 길어지고 비경상 비용이 증가했습니다. IECQ는 절차의 통일을 도모하기 위해 ‘자동차용 인증 프로그램’을 시작했으나, 그 채택 상황은 여전히 불균일한 상태였습니다.
부문 분석
지능형 파워 모듈은 2025년 매출의 37.85%를 차지하며, 엔트리급 전기차 및 하이브리드 차량에서 여전히 주류 옵션으로 자리매김했습니다. SiC 파워 모듈은 비용이 높고, 프리미엄 및 상용 플랫폼에서 효율성이 우선시됨에 따라 연평균 성장률(CAGR) 14.7%를 달성할 것으로 예측됩니다. SiC 디바이스용 자동차 파워 모듈 패키징 시장 규모는 2031년까지 점유율을 7.3퍼센트포인트 더 확대할 것으로 예측됩니다. ROHM과 Valeo의 TRCDRIVE 팩은 SiC가 열적 타협 없이 인버터의 소형화를 가능하게 한다는 점을 입증했습니다. 한편, GaN은 고주파 스위칭이 전류 제한을 초과하는 차량용 충전기 분야에 침투했습니다. IGBT 및 FET 모듈은 중거리 및 보조 부하용으로 계속해서 채택되고 있으며, 미쓰비시 전기가 최근 발표한 제품은 스위칭 손실을 15% 줄이는 동시에 내습성도 향상시켰습니다.
자동차용 파워 모듈 패키징 시장에서는 각 OEM 업체들이 비용, 효율 및 공급 안정성 간의 균형을 모색하는 가운데 시장의 다변화가 지속되었습니다. 200mm 웨이퍼의 양산화가 진행되고 수직 통합 전략이 성숙해지면 SiC의 비용 절감이 예상됩니다. 이에 따라 설계 툴,게이트 드라이버, 그리고 열적으로 최적화된 하우징을 패키지화한 공급업체들은 수년에 걸친 플랫폼 수주를 확보할 수 있도록 자사의 입지를 다지고 있습니다. 고객이 턴키 방식의 모듈 서브시스템을 요구하게 됨에 따라, 집적 소자 제조업체와 전문 조립 제조업체 간의 경쟁은 줄어들 것으로 전망됩니다.
2025년에는 기존의 400V 승용차 플랫폼을 기반으로, 600V까지의 시스템이 44.05%의 점유율을 유지했습니다. 그러나 601-1200V 대역은 급속 충전 시간을 단축하는 800V 토폴로지로의 전환을 반영하여, 연평균 성장률(CAGR) 6.84%로 자동차용 파워 모듈 패키징 시장에서 가장 빠르게 성장하고 있습니다. Aptiv사는 견고한 패키징의 중요성을 높이는 절연 관련 과제와 크레인지 거리 요건에 대해 개괄적으로 설명했습니다. 1200V를 초과하는 모듈은 여전히 틈새 시장으로 남아 있으며, 대형 차량 및 인프라 용도를 대상으로 합니다.
고전압화에 대한 요구가 높아짐에 따라, 더 두꺼운 절연 젤, 낮은 인덕턴스의 구리 클립, 그리고 정격 전압 1.5 kV를 초과하는 압입 핀의 개발이 가속화되었습니다. 인피니언의 1200V CoolSiC MOSFET이 800V DC-DC 컨버터용으로 포르비아 헤라(Forvia Hera)사에 채택된 것은 이러한 플랫폼 전환을 뒷받침하는 사례입니다. 각 OEM 업체들이 차세대 고전압 도메인 컨트롤러의 표준화를 추진하는 가운데, 부분 방전 내성 및 현장 고장 분석을 보장하는 패키징 공급업체가 사양 채택을 확보하게 될 것입니다.
지역별 분석
아시아태평양은 2025년에 56.80%의 점유율을 유지하며, 2031년까지 연평균 성장률(CAGR) 8.72%라는 가장 높은 전망을 보였습니다. 중국의 이중 크레딧 제도와 규모의 경제로 인해 SiC 분야에 대한 대규모 투자가 유치되었습니다. 여기에는 지역 생산 능력의 회복력을 높이기 위해 말레이시아에 건설된 인피니언의 20억 달러 규모 200mm 팹도 포함됩니다. 기판, 메탈라이제이션 페이스트, 성형 컴파운드에 이르는 현지 공급망을 통해 리드타임이 단축되고 비용도 절감되었습니다.
북미에서는 국내 OEM 업체들이 신형 800V 지원 픽업 트럭과 SUV를 발표함에 따라 수요가 가속화되었습니다. 온세미(onsemi)는 체코 공화국에 엔드투엔드 SiC 생산 라인을 건설하기 위해 20억 달러를 투자하여 웨이퍼에서 모듈에 이르는 관리 체계를 확보함과 동시에 수입 의존도를 낮췄습니다. 또한, 연방 정부의 제조 세액 공제 제도도 미국 내 모듈 조립을 촉진했습니다.
유럽에서는 프리미엄 전기차 브랜드와 엄격한 배기가스 규제에 초점이 맞추어졌습니다. 비테스코 테크놀로지스(Vitesco Technologies)는 오스트라바에서 첨단 전자 제품 생산 확장에 5억 7,600만 유로(6억 5,000만 달러)를 투자하며, 해당 지역의 전기화 추세에 대한 확신을 보여주었습니다. 전반적으로, 지역 분산화 노력은 단일 지역에 대한 위험을 분산시키는 동시에, 세계적 품질 기준을 향상시키는 기술 이전을 촉진하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, automotive power module packaging market size in 2026 is estimated at USD 3.55 billion, growing from 2025 value of USD 3.34 billion with 2031 projections showing USD 4.85 billion, growing at 6.42% CAGR over 2026-2031.
This report is Segmented by Module Type (IPM, Sic Power Module, Gan Power Module, and More), Power Rating (Up To 600V, 601-1200V, and More), Packaging Technology (Wire-Bond, Wire-bondless/Power Overlay, and More), Propulsion Type (BEV, HEV, PHEV, and FCEV), Vehicle Type (Passenger Cars, and More), Application (Traction Inverter, On-Board Charger, DC-DC Converter, Auxiliary/Climate/EPS), and Geography.
Global Automotive Power Module Packaging Market Trends and Insights
Rapid EV and HEV production growth
Global battery-electric and hybrid output climbed sharply in 2024, and automotive applications already accounted for more than 70% of SiC demand. Tesla's Cybertruck power converter illustrated how 800 V platforms double voltage stresses and intensify thermal management needs. Tier-1 suppliers such as BorgWarner reported 47% year-on-year eProduct sales growth, signaling that established drivetrain specialists are pivoting resources toward high-density modules.Commercial vehicle programs, including ZF's 300 kW eBeam axle, further widen the addressable base for ruggedized packaging.
Shift toward SiC and GaN wide-bandgap devices
Fourth-generation SiC MOSFETs now sustain junction temperatures above 200 °C, intensifying the need for copper clips, silver sintering, and direct die cooling. Infineon forecasts 2025 as an inflection year for automotive GaN, especially in on-board chargers and high-frequency DC-DC converters. Supply bottlenecks for SiC substrates sharpened focus on 200 mm wafer transitions and on multi-source agreements that stabilize capacity.
Lack of standardized qualification protocols
Power-electronics suppliers faced repeated test loops because AEC-Q100, AEC-Q101, and AEC-Q200 were interpreted differently by regional OEMs, prolonging time-to-market and inflating non-recurring expenses. IECQ launched its Automotive Qualification Programme to harmonize procedures, yet adoption remained uneven.
Other drivers and restraints analyzed in the detailed report include:
- Vehicle electrification demands higher power-density modules
- Stringent global emission regulations
- High cost and supply constraints of SiC/GaN substrates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Intelligent Power Modules held 37.85% of 2025 revenue and remained the volume choice for entry-level EVs and hybrids. SiC Power Modules, though costlier, achieved 14.7% CAGR forecasts as premium and commercial platforms prioritized efficiency. The automotive power module packaging market size for SiC devices is projected to capture an additional 7.3 percentage-point share by 2031. ROHM and Valeo's TRCDRIVE pack showed how SiC enables inverter downsizing without thermal compromise. Meanwhile, GaN penetrated on-board chargers where high-frequency switching outweighed current limits. IGBT and FET modules continue to serve mid-range and auxiliary loads, and recent Mitsubishi Electric releases reduced switching losses by 15% while extending moisture tolerance.
Market diversification persisted across the automotive power module packaging market as OEMs balanced cost, efficiency, and availability. SiC cost declines are expected once 200 mm wafers reach scale and vertical-integration strategies mature. Hence, suppliers that bundle design tools, gate drivers, and thermally optimized housings are positioning themselves to capture multi-year platform awards. The competitive split between integrated device makers and specialized assembly firms is likely to narrow as customers demand turnkey module sub-systems.
Systems up to 600 V retained a 44.05% share in 2025, anchored by existing 400 V passenger-car platforms. However, the 601-1200 V band is the automotive power module packaging market's fastest climber at 6.84% CAGR, mirroring the shift to 800 V topologies that cut fast-charging times. Aptiv outlined insulation challenges and creepage requirements that raise the value of robust packaging. Above-1200V modules remain niche, targeting heavy-duty and infrastructure roles.
Higher voltage demands intensified the development of thicker insulation gels, copper clips with lower inductance, and press-fit pins rated beyond 1.5 kV. Infineon's 1200 V CoolSiC MOSFETs were selected by Forvia Hella for 800 V DC-DC converters, underscoring the platform shift. Packaging suppliers that guarantee partial discharge endurance and field-failure analytics will win specifications as OEMs standardize on next-generation high-voltage domain controllers.
Complete Report Scope:
- By Module Type
- Intelligent Power Module (IPM)
- SiC Power Module
- GaN Power Module
- IGBT Module
- FET Module
- By Power Rating
- Up to 600 V
- 601 - 1200 V
- Above 1200 V
- By Packaging Technology
- Wire-bond
- Wire-bondless / Power Overlay
- Press-fit / Direct Pressed-Die
- PCB-embedded
- By Propulsion Type
- Battery-Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV)
- Plug-in Hybrid (PHEV)
- Fuel-Cell Electric Vehicle (FCEV)
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles and Buses
- By Application
- Traction Inverter
- On-board Charger
- DC-DC Converter
- Auxiliary / Climate / EPS
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific retained a 56.80% share in 2025 and posted the highest outlook at 8.72% CAGR to 2031. China's dual-credit rules and scale advantages drew major SiC investments, including Infineon's USD 2 billion 200 mm fab in Malaysia that addressed regional capacity resilience. Local supply chains spanning substrates, metallization pastes, and molding compounds shortened lead times and trimmed costs.
North American demand accelerated as domestic OEMs unveiled new 800 V pickups and SUVs. onsemi committed USD 2 billion to build an end-to-end SiC line in the Czech Republic, ensuring wafer-to-module control and reducing import dependency. Federal manufacturing tax credits also encouraged module assembly within the United States.
Europe focused on premium EV brands and strict emissions mandates. Vitesco Technologies invested EUR 576 million (USD 650 million) to expand advanced-electronics production in Ostrava, signaling confidence in regional electrification momentum. Collectively, regional diversification initiatives are diluting single-region risk and fostering technology transfers that elevate global quality benchmarks.
- Amkor Technology, Inc.
- Kulicke & Soffa Industries, Inc.
- Powertech Technology Inc. (PTI)
- Infineon Technologies AG
- STMicroelectronics N.V.
- Fuji Electric Co., Ltd.
- Toshiba Electronic Devices & Storage Corporation
- SEMIKRON Danfoss GmbH & Co. KG
- JCET Group Co., Ltd.
- StarPower Semiconductor Ltd.
- Mitsubishi Electric Corporation
- ROHM Co., Ltd.
- onsemi Corporation
- Nexperia B.V.
- Wolfspeed, Inc.
- Microchip Technology Inc.
- Littelfuse, Inc. (IXYS)
- Vitesco Technologies Group AG
- Vincotech GmbH
- CISSOID SA
- Hitachi Astemo, Ltd.
- Danfoss Silicon Power GmbH
- BYD Semiconductor Co., Ltd.
- Dynex Semiconductor Ltd.
- Shenzhen BASiC Semiconductor Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid EV and HEV production growth
- 4.2.2 Shift toward SiC and GaN wide-bandgap devices
- 4.2.3 Vehicle electrification demanding higher power-density modules
- 4.2.4 Stringent global emission regulations
- 4.2.5 OEM adoption of wire-bondless / top-side-cooling packages
- 4.2.6 Cell-to-pack architectures integrating power modules
- 4.3 Market Restraints
- 4.3.1 Lack of standardized qualification protocols
- 4.3.2 High cost and supply constraints of SiC / GaN substrates
- 4.3.3 Thermal-management limits in emerging 800 V platforms
- 4.3.4 Potential SiC supply-chain over-capacity
- 4.4 Impact of Macroeconomic Factors
- 4.5 Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Module Type
- 5.1.1 Intelligent Power Module (IPM)
- 5.1.2 SiC Power Module
- 5.1.3 GaN Power Module
- 5.1.4 IGBT Module
- 5.1.5 FET Module
- 5.2 By Power Rating
- 5.2.1 Up to 600 V
- 5.2.2 601 - 1200 V
- 5.2.3 Above 1200 V
- 5.3 By Packaging Technology
- 5.3.1 Wire-bond
- 5.3.2 Wire-bondless / Power Overlay
- 5.3.3 Press-fit / Direct Pressed-Die
- 5.3.4 PCB-embedded
- 5.4 By Propulsion Type
- 5.4.1 Battery-Electric Vehicle (BEV)
- 5.4.2 Hybrid Electric Vehicle (HEV)
- 5.4.3 Plug-in Hybrid (PHEV)
- 5.4.4 Fuel-Cell Electric Vehicle (FCEV)
- 5.5 By Vehicle Type
- 5.5.1 Passenger Cars
- 5.5.2 Light Commercial Vehicles
- 5.5.3 Heavy Commercial Vehicles and Buses
- 5.6 By Application
- 5.6.1 Traction Inverter
- 5.6.2 On-board Charger
- 5.6.3 DC-DC Converter
- 5.6.4 Auxiliary / Climate / EPS
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 France
- 5.7.3.3 United Kingdom
- 5.7.3.4 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 Saudi Arabia
- 5.7.5.1.2 United Arab Emirates
- 5.7.5.1.3 Turkey
- 5.7.5.1.4 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amkor Technology, Inc.
- 6.4.2 Kulicke & Soffa Industries, Inc.
- 6.4.3 Powertech Technology Inc. (PTI)
- 6.4.4 Infineon Technologies AG
- 6.4.5 STMicroelectronics N.V.
- 6.4.6 Fuji Electric Co., Ltd.
- 6.4.7 Toshiba Electronic Devices & Storage Corporation
- 6.4.8 SEMIKRON Danfoss GmbH & Co. KG
- 6.4.9 JCET Group Co., Ltd.
- 6.4.10 StarPower Semiconductor Ltd.
- 6.4.11 Mitsubishi Electric Corporation
- 6.4.12 ROHM Co., Ltd.
- 6.4.13 onsemi Corporation
- 6.4.14 Nexperia B.V.
- 6.4.15 Wolfspeed, Inc.
- 6.4.16 Microchip Technology Inc.
- 6.4.17 Littelfuse, Inc. (IXYS)
- 6.4.18 Vitesco Technologies Group AG
- 6.4.19 Vincotech GmbH
- 6.4.20 CISSOID SA
- 6.4.21 Hitachi Astemo, Ltd.
- 6.4.22 Danfoss Silicon Power GmbH
- 6.4.23 BYD Semiconductor Co., Ltd.
- 6.4.24 Dynex Semiconductor Ltd.
- 6.4.25 Shenzhen BASiC Semiconductor Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


