

|
시장보고서
상품코드
2123302
광학 세라믹 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Optical Ceramics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
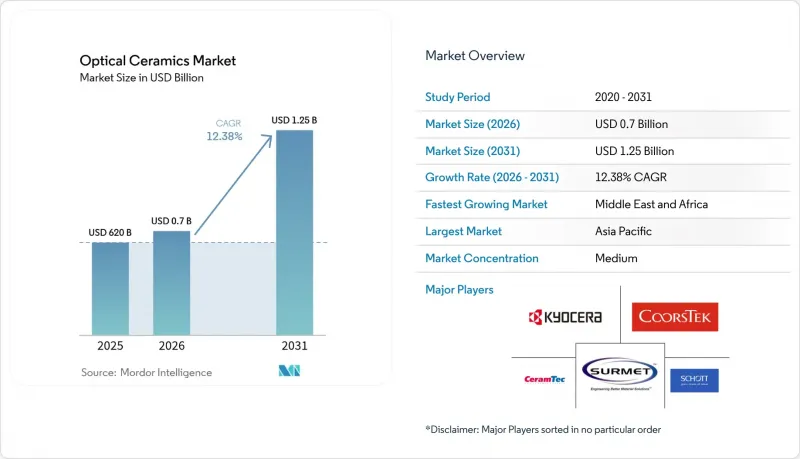
에 의하면, 광학 세라믹 시장 규모는 2025년에 6억 2,000만 달러로 평가되었고 2026년 6억 9,680만 달러에서 2031년까지 12억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 12.38%를 나타낼 전망입니다.
본 보고서는 재료 유형(이트륨·알루미늄·가넷 등), 제조 방법(고상 소결 등), 제품 유형(다결정 및 단결정), 용도(투명 장갑 및 방탄 창 등), 최종 이용 산업(항공우주 및 방위, 의료 등),및 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다.
세계 광학 세라믹 시장 동향 및 인사이트
차세대 전투 차량에서 적외선 투과형 장갑의 급속한 보급
방위 프로그램에서는 ALON 및 스피넬 재질의 윈도우가 채택되어, 탄도 차단 성능을 유지하면서도 접합 유리에 비해 최대 60%의 경량화를 실현함으로써 연비 효율과 승무원의 기동성을 향상시켰습니다. 구성 부품의 크기는 8제곱피트 패널 크기까지 확대되어, 차량 전체의 유리 적용이 실용화되었습니다. 머신러닝에 기반한 적층 방식을 통해 두께를 22.2% 줄이면서도 투과율을 42.3% 향상시켜, 이 개념의 확장성이 입증되었습니다. 미국 육군과공급 계약을 통해 대형 부품의 인증이 가속화되었고, 시험 주기가 단축되었습니다. 그 결과, 조달 기관은 수량을 확정하고 가격을 안정화하는 다년 계약을 발주했습니다.
UV-LED 및 레이저 기반 의료기기의 급증으로 인해 다결정 YAG 광학 소자에 대한 수요가 증가하고 있습니다.
저침습 치료에서는 물에 잘 흡수되는 파장을 가진 Ho:YAG 및 Nd:YAG 레이저에 대한 의존도가 높아지고 있으며, 이를 통해 주변 조직에 미치는 열적 영향을 최소화하면서 조직을 정확하게 절제할 수 있게 되었습니다. 다결정 YAG는 유리에 비해 열전도율이 뛰어나, 더 높은 펄스 에너지로 작동하고 부품 수명을 연장할 수 있게 되었습니다. 공정 혁신을 통해 1064 nm에서 83.7%의 투과율을 달성하고월플러그 효율이 향상됨에 따라, 외래 진료에 적합한 휴대형 수술 플랫폼의 구현이 촉진되었습니다. 아시아의 의료기기 수탁 제조업체들이 생산을 확대함에 따라, 해당 지역에서의 보급 곡선이 가속화되었습니다.
설비 투자가 필요한 열등정압 성형 라인이 신흥 시장 진입을 가로막고 있다.
상용 HIP 설비의 도입 비용은 종종 1,500만 달러를 초과하여, 신규 진출기업에게는 높은 자금적 장벽이 되고 있습니다. 압력 용기 설계 및 제어 분위기 하에서의 운영에 관한 전문 지식은 여전히 성숙한 산업 지역에 집중되어 있어, 기술력 격차를 확대되고 있습니다. ‘클린 HIP’이나 ‘스티어드 쿨링’과 같은 기술 개선은 성능을 향상시켰지만, 동시에 자본 집약도를 높여 기존 기업의 우위를 더욱 공고히 했습니다.
부문 분석
YAG는 산업용 레이저, 신틸레이터, 센싱 광학 시스템 등 폭넓은 용도에 대응할 수 있는 범용성을 바탕으로, 2025년 광학 세라믹 시장에서 29.85%의 점유율을 유지했습니다. 소결 기술의 다각적인 개선을 통해 1064 nm에서의 투과율이 향상되었고, 10 kW급 레이저 커터의 빔 품질이 개선되었습니다. ALON사는 경량임에도 방탄 등급의 창문에 대한 엄격한 방위·우주 분야 사양을 충족함으로써 연평균 성장률(CAGR) 12.86%를 기록했습니다. 사파이어는 타의 추종을 불허하는 경도(모스 경도 9)와 2,000°C의 열안정성으로 에너지 분야에서의 입지를 유지했습니다. 스피넬의 입방 격자 구조 덕분에 복굴절 현상이 해소되어 항공기 탑재형 이미징 기술이 뒷받침되었습니다. 이트리아는 반도체 팹의 플라즈마 에칭 챔버 라이너 용도로 시장을 꾸준히 확대했습니다. 신흥 소재인 루테튬계 가넷은 차세대 신틸레이터 분야에서 유망한 소재로 주목받고 있습니다.
YAG 시스템용 광학 세라믹 시장 규모는 연평균 11.38%로 확대될 것으로 예측되지만, ALON의 점유율 확대로 인해 YAG의 판매량이 현저히 감소하지 않으면서 업계 전체 시장 가치가 상승할 것으로 전망됩니다. 현재 밸류체인에서는 YAG와 ALON을 상시 듀얼 소스로 조달하여 혼합 재료 어셈블리를 맞춤 제작하고 있으며, 이는 엄격한 대체가 아니라 설계 최적화를 반영한 것입니다.
열등방압 소결(HIP)은 방탄 장갑 및 고출력 광학 시스템에 필수적인, 낮은 기공률과 이론 밀도에 가까운 부품을 제조함으로써 2025년에는 매출의 40.70%를 차지했습니다. 가스 정제 챔버 등의 공정 개선을 통해 대형 패널의 수율이 향상되어, 고급 제품에서 HIP의 경제적 우위가 더욱 강화되었습니다. 한편, 진공 소결은 단위 에너지 소비량을 억제하면서도 투명 알루미나에서 70%의 투과율을 실현하여, 비용 효율을 중시하는 분야에서 지지를 얻음에 따라 10.96%라는 가장 높은 연평균 성장률(CAGR)이 예상됩니다. 고체 소결은 단순한 형상에서 여전히 중요성을 유지하고 있는 반면, 연구자들이 구배 굴절률 요소의 적층 조형을 수행하게 됨에 따라 적층 조형은 ‘기타’ 범주로 분류되었습니다.
2031년까지 진공 소결이 확대됨에 따라 광학 세라믹 시장에서 HIP의 점유율은 소폭 하락할 가능성이 있으나, 대형 장갑 세트가 생산량을 견인할 것으로 예상되어 HIP로에서의 총 생산량은 증가할 전망입니다. 투명성과 비용의 균형을 맞추기 위해, 진공을 이용한 예비 소결과 최종 HIP 치밀화 과정을 결합한 하이브리드 공정이 검토되고 있습니다.
지역별 분석
아시아태평양은 중국의 배터리 팩용 레이저의 급속한 확대와 일본의 경량 위성 광학 시스템에 대한 집중으로 인해 2025년 매출의 37.90%를 차지하며 광학 세라믹 시장을 주도했습니다. 한국과 대만에서는 세라믹 플래시 램프 및 센서 윈도우를 전문으로 하는 제조 거점이 증가했습니다. 일본의 ‘파인 세라믹 로드맵 2050’과 같은 정부 주도의 노력을 통해 장기적인 기술 수요가 명확해졌습니다.
북미는 견조한 국방 지출, 특히 투명 장갑 및 레이저 시스템 업그레이드를 진행하는 미국의 프로그램을 활용하여 큰 시장 점유율을 유지했습니다. 샌디아 국립연구소와 민간 기업이 협력하는 클러스터는 시행착오를 물리 기반 모델링으로 대체함으로써 개발 주기를 단축했습니다. 캐나다와 멕시코는 전문적인 생산 및 연구 개발(R&D)에 기여하여 북미 공급망의 회복력을 확보했습니다.
중동 및 아프리카은 10.98%라는 가장 높은 연평균 성장률(CAGR)을 기록했으며, 사우디아라비아와 아랍에미리트는 ALON이 제조한 항공기 탑재용 적외선 센서 돔에 자금을 지원했습니다. 이스라엘의 세라믹·규산염 연구소는 지역으로의 노하우 이전을 가능하게 하여, 국내에서 탄도용 장갑재 개발을 촉진했습니다.
유럽은 터빈용 고온 사파이어 창 및 과학 연구용 정밀 광학 기기에 관한 중요한 전문 지식을 유지했습니다. 독일과 영국이 제품 혁신을 주도하는 한편, 북유럽 클러스터는 세라믹 가공 시 탄소 발자국을 줄이기 위해 수소 연소식 가마 도입을 선도적으로 추진했습니다. 남미에서는 브라질과 아르헨티나가 현지 광물 자원을 활용하여 정제 및 의료 분야에 사파이어 검사 포트를 도입함으로써 소규모 기반에서 성장을 이루었습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the optical ceramics market size was valued at USD 620 million in 2025 and estimated to grow from USD 696.8 million in 2026 to reach USD 1.25 billion by 2031, at a CAGR of 12.38% during the forecast period (2026-2031).
This report is Segmented by Material Type (Yttrium Aluminum Garnet, and More), Fabrication Method (Solid-State Sintering, and More), Product Type (Polycrystalline and Monocrystalline), Application (Transparent Armor and Bullet-Resistant Windows, and More), End-Use Industry (Aerospace and Defense, Healthcare, and More), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa).
Global Optical Ceramics Market Trends and Insights
Rapid Adoption of IR-Transparent Armor in Next-Gen Combat Vehicles
Defense programs integrated ALON and spinel windows that cut weight up to 60% versus laminated glass while maintaining ballistic stop levels, enhancing fuel efficiency, and crew mobility. Components grew to panel sizes of eight square feet, making full-vehicle glazing practical. Machine-learning-guided stacking schemes lowered thickness 22.2% yet raised transmission 42.3%, proving the concept's scalability. Supply contracts from the U.S. Army accelerated the qualification of larger parts and shortened testing cycles. As a result, procurement agencies issued multi-year orders that locked in volume and stabilized pricing.
Surge in UV-LED and Laser-Based Medical Devices Demanding Polycrystalline YAG Optics
Minimally invasive therapies increasingly relied on Ho:YAG and Nd:YAG lasers whose wavelengths are strongly absorbed by water, ensuring precise tissue removal with limited collateral heating. Polycrystalline YAG offered improved thermal conductivity over glass, enabling higher pulse-energy operation and longer component lifetimes. Process innovations delivered 83.7% transmittance at 1064 nm, lifting wall-plug efficiency and facilitating portable surgical platforms well suited to outpatient clinics. Asian contract-device makers expanded production, accelerating regional adoption curves.
Capex-Intensive Hot-Isostatic-Pressing Lines Limiting Emerging-Market Entry
Commercial HIP installations often exceeded USD 15 million, creating high financial thresholds for newcomers. Expertise in pressure-vessel design and controlled-atmosphere operations remained concentrated in mature industrial regions, widening the capability gap. Upgrades such as 'Clean HIP' and 'Steered Cooling' improved performance but also raised capital intensity, reinforcing incumbent advantages.
Other drivers and restraints analyzed in the detailed report include:
- Growth of High-Temperature Gas-Turbine Inspections That Require Sapphire Windows
- Spacecraft Light-Weighting Drives ALON/Spinel Viewports in LEO Satellites
- Yield Losses Above 15% for 120 mm-Diameter Components Keep Unit Costs Uncompetitive vs. Glass
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
YAG retained 29.85% dominance within the optical ceramics market in 2025 through versatility across industrial lasers, scintillators, and sensing optics. Multiple sintering refinements elevated its 1064 nm transmittance, improving beam quality in 10 kW-class laser cutters. ALON posted a 12.86% CAGR by fulfilling aggressive defense and space specifications for lightweight yet ballistic-grade windows. Sapphire maintained energy-sector loyalty thanks to unmatched hardness (Mohs 9) and 2,000 °C thermal stability. Spinel's cubic lattice removed birefringence, supporting airborne imaging. Yttria expanded steadily for plasma-etch chamber liners in semiconductor fabs. Emerging lutetium-based garnets showed promise in next-generation scintillators.
The optical ceramics market size for YAG systems is projected to rise at 11.38% annually, while ALON share gains are forecast to elevate total industry value without materially eroding YAG volumes. Supply chains now routinely dual-source YAG and ALON to tailor mixed-material assemblies, reflecting design optimization rather than strict substitution.
Hot isostatic pressing secured 40.70% revenue in 2025 by producing near-theoretical-density parts with low porosity, essential for ballistic armor and high-power optics. Process refinements like gas-purified chambers raised yield in large panels, reinforcing HIP's economic edge in premium products. Vacuum sintering, however, posted the highest 10.96% CAGR outlook by delivering 70% transmittance in transparent alumina at lower unit energy, appealing to cost-sensitive sectors. Solid-state sintering kept relevance for simpler geometries, while additive manufacturing joined the "Others" category as researchers printed gradient-index elements.
Through 2031, the optical ceramics market share for HIP may slip modestly as vacuum sintering scales, yet overall output from HIP furnaces will climb because larger armor sets drive volume. Hybrid flows that combine vacuum pre-sintering with final HIP densification are under evaluation to balance clarity and cost.
Complete Report Scope:
- By Material Type
- Yttrium Aluminum Garnet (YAG)
- Aluminum Oxynitride (ALON)
- Spinel
- Sapphire
- Yttria
- Others
- By Fabrication Method
- Solid-state Sintering
- Hot Isostatic Pressing (HIP)
- Vacuum Sintering
- Others
- By Product Type
- Polycrystalline
- Monocrystalline
- By Application
- Transparent Armor and Bullet-resistant Windows
- Sensor and Imaging Optics
- Laser and Lighting Components
- Medical Imaging and Diagnostics
- LEDs and Phosphors
- Energy and Power Generation Optics
- Others
- By End-Use Industry
- Aerospace and Defense
- Healthcare
- Energy
- Consumer Electronics
- Industrial and Manufacturing
- Research and Instrumentation
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Nordics (Sweden, Finland, Norway, Denmark)
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- Taiwan
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific led the optical ceramics market with 37.90% 2025 revenue thanks to China's rapid battery-pack laser expansion and Japan's focus on light-weighted satellite optics. South Korea and Taiwan added fabs specializing in ceramic flash lamps and sensor windows. Government initiatives such as Japan's Fine Ceramics Roadmap 2050 mapped long-range technology needs.
North America leveraged strong defense spending, particularly U.S. programs upgrading transparent armor and laser systems, maintaining a sizeable share. Collaborative clusters involving Sandia National Laboratories and private industry shortened development cycles by replacing trial-and-error with physics-based modeling. Canada and Mexico contributed specialized production and R&D, securing resiliency in North American supply chains.
The Middle East and Africa recorded the fastest 10.98% CAGR, with Saudi Arabia and the United Arab Emirates funding airborne IR sensor domes built from ALON. Israel's Ceramic and Silicate Institute enabled regional know-how transfer, fostering domestic ballistic-grade armor developments.
Europe retained critical expertise in high-temperature sapphire windows for turbines and precision optics for scientific research. Germany and the United Kingdom drove product innovation, while the Nordic cluster pioneered hydrogen-fired kilns to cut carbon footprints in ceramic processing. South America grew from a small base as Brazil and Argentina introduced sapphire inspection ports in refining and healthcare sectors, leveraging local mineral resources.
- Surmet Corporation
- CoorsTek Inc.
- CeramTec GmbH
- CeraNova Corporation
- Schott AG
- Saint-Gobain S.A.
- Kyocera Corporation
- Murata Manufacturing Co., Ltd.
- Konoshima Chemical Co., Ltd.
- Ceradyne Inc. (3M)
- II-VI Incorporated / Coherent Corp.
- Rubicon Technology Inc.
- Adamant Namiki Precision Jewel Co., Ltd.
- Crystalwise Technology Inc.
- Advanced Ceramics Manufacturing LLC
- AGC Inc.
- Baikowski SA
- Zhongke Jingcheng New Material Co., Ltd.
- Sinoma Advanced Nitride Ceramics Co., Ltd.
- SICCAS High-Tech Materials Co., Ltd.
- American Elements
- Toshima Manufacturing Co., Ltd.
- Ceratec Technical Ceramics BV
- Tera YAG Co., Ltd.
- Precision Ceramics International Ltd.
- Blasch Precision Ceramics Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid adoption of infra-red transparent armor in next-gen combat vehicles
- 4.2.2 Surge in UV-LED and laser-based medical devices demanding polycrystalline YAG optics
- 4.2.3 Growth of high-temperature gas-turbine inspections that require sapphire windows
- 4.2.4 Spacecraft light-weighting drives ALON/spinel viewports in LEO satellites
- 4.2.5 Large-area Li-ion battery pack lasers using ceramic flash lamps
- 4.2.6 Military modernization budgets earmarked for airborne IR sensors with ceramic domes
- 4.3 Market Restraints
- 4.3.1 Capex-intensive hot-isostatic-pressing lines limiting emerging-market entry
- 4.3.2 Yield-losses (>15 %) above 120 mm diameter keep unit costs uncompetitive vs. glass
- 4.3.3 Limited transmittance in the 5-7 µm band constrains long-wave IR adoption
- 4.3.4 IP consolidation-over 120 active U.S. patents block new formulations
- 4.4 Value Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Investment and Funding Trends Analysis
- 4.9 Impact of Macroeconomic factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Yttrium Aluminum Garnet (YAG)
- 5.1.2 Aluminum Oxynitride (ALON)
- 5.1.3 Spinel
- 5.1.4 Sapphire
- 5.1.5 Yttria
- 5.1.6 Others
- 5.2 By Fabrication Method
- 5.2.1 Solid-state Sintering
- 5.2.2 Hot Isostatic Pressing (HIP)
- 5.2.3 Vacuum Sintering
- 5.2.4 Others
- 5.3 By Product Type
- 5.3.1 Polycrystalline
- 5.3.2 Monocrystalline
- 5.4 By Application
- 5.4.1 Transparent Armor and Bullet-resistant Windows
- 5.4.2 Sensor and Imaging Optics
- 5.4.3 Laser and Lighting Components
- 5.4.4 Medical Imaging and Diagnostics
- 5.4.5 LEDs and Phosphors
- 5.4.6 Energy and Power Generation Optics
- 5.4.7 Others
- 5.5 By End-Use Industry
- 5.5.1 Aerospace and Defense
- 5.5.2 Healthcare
- 5.5.3 Energy
- 5.5.4 Consumer Electronics
- 5.5.5 Industrial and Manufacturing
- 5.5.6 Research and Instrumentation
- 5.5.7 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Nordics (Sweden, Finland, Norway, Denmark)
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 Taiwan
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Surmet Corporation
- 6.4.2 CoorsTek Inc.
- 6.4.3 CeramTec GmbH
- 6.4.4 CeraNova Corporation
- 6.4.5 Schott AG
- 6.4.6 Saint-Gobain S.A.
- 6.4.7 Kyocera Corporation
- 6.4.8 Murata Manufacturing Co., Ltd.
- 6.4.9 Konoshima Chemical Co., Ltd.
- 6.4.10 Ceradyne Inc. (3M)
- 6.4.11 II-VI Incorporated / Coherent Corp.
- 6.4.12 Rubicon Technology Inc.
- 6.4.13 Adamant Namiki Precision Jewel Co., Ltd.
- 6.4.14 Crystalwise Technology Inc.
- 6.4.15 Advanced Ceramics Manufacturing LLC
- 6.4.16 AGC Inc.
- 6.4.17 Baikowski SA
- 6.4.18 Zhongke Jingcheng New Material Co., Ltd.
- 6.4.19 Sinoma Advanced Nitride Ceramics Co., Ltd.
- 6.4.20 SICCAS High-Tech Materials Co., Ltd.
- 6.4.21 American Elements
- 6.4.22 Toshima Manufacturing Co., Ltd.
- 6.4.23 Ceratec Technical Ceramics BV
- 6.4.24 Tera YAG Co., Ltd.
- 6.4.25 Precision Ceramics International Ltd.
- 6.4.26 Blasch Precision Ceramics Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


