

|
시장보고서
상품코드
2123346
항공기 연료 탱크 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Aircraft Fuel Tanks - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
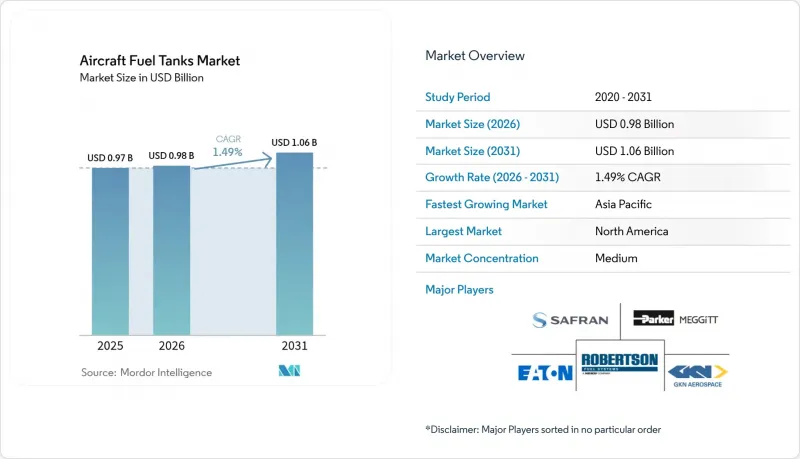
에 의하면, 항공기용 연료 탱크 시장 규모는 2025년 9억 7,000만 달러에서 2026년에는 9억 8,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 1.49%로 성장을 지속하여, 2031년까지 10억 6,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형(내장형 및 외장형), 소재(금속 합금, 탄소섬유 복합재, 폴리머/엘라스토머 블래더 등), 플랫폼(민간 항공기, 군용기 등), 최종 용도(OEM, 애프터마켓/개조), 지역(북미, 유럽,아시아태평양 등)별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
전 세계 항공기 연료 탱크 시장 동향 및 인사이트
민간 항공기 생산 확대기
항공사들은 구형 나로우바디 기종을 가동률이 높은 단일 통로 제트기로 교체하고 있으며, 거시경제의 불확실성이 있음에도 불구하고 연료 탱크 수요는 견조하게 유지되고 있습니다. 에어버스 A321XLR의 1만 2,900리터 용량의 후방 중앙 탱크는 항속 거리를 4,700해리까지 연장하고 있으며, 독창적인 연료 저장 방식이 기존보다 효율적인 새로운 항로를 개척할 수 있음을 입증하고 있습니다. 기록적인 수주 잔고(대부분 10년을 초과)가 예상에 따라, 탱크 공급업체는 미래를 내다보며 생산 능력을 계획할 수 있게 되었습니다. 각 OEM 업체는 현재 객실에서 주익에 이르는 개조 주기를 90일로 하는 것을 목표로 하고 있으며, 초기 프로그램의 120일에서 단축되어 라인 피팅을 통한 생산 능력이 확대되고 있습니다. 단일 통로 항공기의 비중이 지속적으로 변화하는 가운데, 항공사들이 고밀도 좌석 배치를 표준화함에 따라 무게 중심 관리를 용이하게 하는 기술이 중요시되고 있습니다. 공급망의 취약성이 단기적인 생산량을 억제하고는 있지만, 중기적인 관점에서 볼 때 이러한 동향이 가져오는 긍정적 효과는 여전히 크다고 할 수 있습니다.
방위 분야의 함대 현대화 프로그램
미국의 3단계 급유기 교체 계획에는 2029년까지 KC-46A 납품을 완료하고, 140-160대의 KC-Y를 조달하며, 2040년경에 스텔스형 NGAS 플랫폼을 배치하는 내용이 포함되어 있습니다. KC-46A만으로도 전 세계 작전에서 2억 파운드 이상의 연료를 수송하고 있어, 첨단 급유 기술이 임무 수행에 있어 지극히 중요한 역할을 하고 있음이 부각되고 있습니다. 전 세계 무기 수입의 42%를 차지하는 아시아태평양 지역의 지출은 해당 군용기군의 기반을 확대시키고 있습니다. 유럽의 8대로 구성된 다국적 MRTT 기단은 다른 지역이 비용 대비 효과가 높은 공중 급유 능력을 확보하기 위해 참고할 수 있는 협력 모델을 제공합니다. 스텔스기에 대응하는 급유기의 프리미엄 가격은 방위 프로그램에 전형적인 소량 생산이라는 과제를 상쇄하고, 장기적으로 견실한 수익 기여를 보장합니다.
항공우주용 원자재 가격 변동과 공급망 리스크
티타늄 스폰지의 조달 상황은 여전히 불안정하며, 미국은 지정학적으로 민감한 공급처에서 90% 이상을 수입하고 있습니다. 러시아와 우크라이나 간의 분쟁 및 중국의 생산 능력 확대는 가격 안정성을 저해하고 있으며, 2027년까지 전 세계 티타늄 가격의 연평균 성장률(CAGR)을 6.8%로 끌어올리고 있습니다. 합금 제품 위조 사건으로 인해 에어버스와 보잉의 생산 라인에서는 입고 검사 절차가 강화되어 비용 및 일정 측면의 압박이 커지고 있습니다. 미결 주문으로 인해 단조품 및 주조품의 리드타임이 길어지고 있어, 각 OEM 기업들은 주요 탱크 부품의 조달처를 2개사로 분산할 수밖에 없는 상황입니다. 조달처의 다각화나 니어쇼어링 추진에는 수년에 걸친 설비 투자가 필요하며, 이로 인해 1차 공급업체의 이익률 개선 여지가 줄어들고 있습니다.
부문 분석
외부 탱크는 3.9%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 이는 각국 군이 전술적 필요성이 변화했을 때 투하 또는 분리 가능한 드롭 탱크, 컨포멀 시스템, 버디팟식 급유 장치를 우선적으로 채택하고 있기 때문입니다. 내부 시스템은 2025년 매출의 59.12%를 차지하며 여전히 주류를 이루고 있으며, 민간 항공 분야에서 공간 효율성과 무게 중심 면에서 두드러진 이점을 가지고 있습니다. 이튼(Eaton)사의 1,360갤런 용량 투하 가능 유닛은 JP-4, JP-5, JP-8과의 호환성을 갖추면서도 초음속 비행 시 탑재에 견딜 수 있는 구조적 요건을 충족합니다. 컨포멀 형상의 등장으로, 기존의 날개 상자를 갖지 않는 블렌디드 윙 바디(BWB) 실증기가 지원되고 있습니다. 자가 밀폐 기술의 발전으로 화염탄으로부터의 보호가 도모되는 한편, 통합형 연료 계량기는 디지털 프로브를 통해 0.25% 미만의 정확도를 실현하고 있습니다.
성장의 초점은 스텔스성과 페리 항속 거리를 요구하는 새로운 하이브리드 전투기의 임무로 이동하고 있으며, 설계자들은 내부 베이와 저가시성 외부 포드를 융합해야만 하는 상황에 직면해 있습니다. 블래더식 보조 키트는 애프터마켓의 성장세를 뒷받침하며, 항공사가 구조 재인증 없이도 항속 거리 연장 패키지를 도입할 수 있도록 해줍니다. 능동형 상태 모니터링(AHM) 센서는 예측 유지보수 알고리즘에 데이터를 제공하여 누출이 확대되기 전에 정비 시기를 계획합니다. 따라서 항공기 연료 탱크 시장 규모는 정체되어 있지만, 내부 시스템 및 외부 탱크의 혁신이 증분 수익의 과반수를 차지하고 있습니다.
탄소섬유 복합재는 단거리 항공기 1대당 15-35kg의 경량화를 원동력으로 2025년 매출의 40.95%를 차지하며, 이는 수명 주기 동안 수백만 달러 규모의 연료 소비 감축으로 이어집니다. 하이브리드 극저온 구조는 2030년대 중반의 취항을 중심으로 수소 로드맵이 구체화됨에 따라 연평균 성장률(CAGR) 5.28%로 성장을 지속하고, 있습니다. 라이너리스형 V 탱크는 40%의 추가 경량화가 예상되지만, 높은 주기적 압력 하에서 미세 균열이 전파되는 문제에 직면해 있습니다. 알루미늄·리튬 등의 금속 합금은 입증된 파괴 인성이 최우선으로 요구되는 분야, 특히 와이드바디기의 주익 일체형 탱크에서 여전히 중요한 역할을 하고 있습니다. 폴리머 기반 블래더는 신속한 설치와 낮은 설비 투자 비용 덕분에 계속해서 개조 수요를 충족시키고 있습니다.
자동 섬유 배열(AFP) 기술에서는 초음파 용접을 결합하여 액체 밀폐 이음매를 형성하고 있으며, 이는 극저온 LH2의 필수 조건입니다. 하이브리드 구조에서는 티타늄 라이너와 탄소 오버랩을 결합함으로써 라이너리스 설계의 성숙을 촉진하고 있습니다. 내장형 광섬유 센서가 변형 및 온도를 실시간으로 추적하여 예측 유지보수 비즈니스 모델을 실현하고 있습니다. 그 결과, 현재 복합재료가 시장 가치의 대부분을 차지하고 있지만, 항공기 연료 탱크 시장에서 하이브리드 및 스마트 소재 솔루션의 점유율은 앞으로도 계속 상승할 전망입니다.
지역별 분석
북미는 보잉사의 대량 생산 모델인 B737 및 B787 시리즈에 더해, 미 공군의 급유기 교체 계획에 힘입어 2025년 매출의 35.05%를 차지하며 1위를 유지했습니다. KC-46A 프로그램은 일정 지연이 있었음에도 불구하고, 분당 1,200갤런의 급유 속도를 가능하게 하는 첨단 비활성화 처리 및 붐 급유 대응 탱크의 유효성을 입증하고 있습니다. 워싱턴의 정책은 티타늄 및 알루미늄 밸류체인의 국내 복귀에 초점을 맞추고 있으며, 러시아와 중국으로 인한 지정학적 위험을 완화하는 것을 목표로 하고 있습니다. 바이든 행정부의 2025년 ‘인플레이션 억제법’은 수소 항공기 실증기를 지원하고 있으며, LH2 탱크의 초기 연구 개발 자금을 촉진하고 있습니다.
중국이 2043년까지 상용 항공기 기단을 두 배로 늘리는 것을 목표로 하고 있으며, 8,000대 이상의 단일 통로형 항공기가 필요함에 따라 아시아태평양은 5.07%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 이 항공기들에는 일체형 탄소섬유 탱크가 탑재될 예정입니다. COMAC C919의 인도 대수는 2024년 말까지 10대에 달할 전망이며, 이는 국산 서브시스템 생태계를 활성화시키고 있습니다. 인도에서는 연간 8.3%의 여객 수 증가가 좌석 수가 많은 협폭기 수주를 뒷받침하고 있습니다. 한편, ‘메이크 인 인디아(Make in India)’ 구상에 따라 LEAP 엔진 부품을 위한 사프란(Safran)·HAL 등의 연료 시스템 합작 사업이 유치되고 있습니다. 전 세계 수입의 42%를 차지하는 국방 지출로 인해 다목적 급유기 및 개조된 전투기 편대를 위한 컨포멀 솔루션에 대한 수요가 증가하고 있습니다.
유럽 시장 점유율은 에어버스의 안정적인 생산과 네덜란드에서 납품된 8대 규모의 MRTT 기단과 같은 공동 방위 프로젝트를 통해 서서히 확대되고 있습니다. EASA의 ‘RefuelEU’ 규정에 따르면 2025년에 SAF를 2% 혼합하는 것이 의무화되며, 2050년까지 70%로 확대될 예정이어서 연료 특성의 변동에 대응하기 위해 연료 탱크의 업그레이드가 요구되고 있습니다. 스웨덴과 프랑스의 지역 연구개발 클러스터는 극저온 실증 기체에 대한 투자를 적극적으로 진행하고 있으며, 그 일례로 AFP 셀과 디지털 트윈을 통합한 GKN사의 트롤헤탄 거점의 5,000 m² 확장 사업을 들 수 있습니다. 브렉시트로 인한 통관 마찰이 영국 공급업체의 경쟁력을 약화시키고 있지만, 스피릿 에어로시스템즈(Spirit AeroSystems)의 집중적인 투자를 통해 핵심 구조물의 생산 능력이 강화되고 있습니다. 전반적으로, 수요의 지리적 이동으로 인해 아시아태평양이 생산량 성장을 주도하는 한편, 북미는 기술 면에서 계속해서 선도적인 역할을 수행하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the aircraft fuel tanks market size is expected to grow from USD 0.97 billion in 2025 to USD 0.98 billion in 2026 and is forecast to reach USD 1.06 billion by 2031 at 1.49% CAGR over 2026-2031.
This report is Segmented by Type (Internal and External), Material (Metallic Alloys, Carbon-Fiber Composites, Polymer/Elastomer Bladders, and More), Platform (Commercial Aircraft, Military Aircraft, and More), End Use (OEM, Aftermarket/Retrofit), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Aircraft Fuel Tanks Market Trends and Insights
Commercial Aircraft Production Up-Cycle
Airlines are replacing older narrow-bodies with high-utilization single-aisle jets, sustaining baseline fuel-tank demand even during macroeconomic uncertainty. The Airbus A321XLR's 12,900-liter rear-center tank extends range to 4,700 nm, proving that creative fuel storage unlocks new, thinner routes. Record backlog visibility-often exceeding 10 years-allows tank suppliers to forward-plan capacity. OEMs now target 90-day cabin-to-wing modification cycles, down from 120 days on early programs, broadening line-fit throughput. Sustained single-aisle mix shifts favor technologies that ease center-of-gravity management as airlines standardize high-density seating. While supply-chain fragility tempers near-term output, the driver's net positive effect remains sizable over the medium term.
Defense Fleet Modernization Programs
Three-phase tanker recapitalization in the United States involves completing KC-46A deliveries by 2029, procuring 140-160 KC-Y units, and fielding the stealth NGAS platform around 2040. The KC-46A alone has transferred over 200 million lb of fuel in global operations, highlighting the mission-critical role of advanced tank technology. Asia-Pacific outlays, accounting for 42% of global arms imports, widen the addressable military fleet base. Europe's eight-unit Multinational MRTT Fleet provides a cooperative model that other regions may replicate for cost-effective aerial refueling capacity. Premium pricing of stealth-compatible tanks offsets the narrower unit volumes typical of defense programs, ensuring a robust revenue contribution through the long term.
Volatile Aerospace Raw-Material Prices and Supply Chain Risk
Titanium sponge sourcing remains exposed, with the United States importing over 90% from geopolitically sensitive suppliers. Russia's conflict with Ukraine and China's capacity build-up undermine price stability, driving a 6.8% global titanium CAGR through 2027. Counterfeit alloy incidents have prompted intensified incoming inspection protocols at Airbus and Boeing lines, heightening cost and schedule pressure. Backlogs now embed longer lead times for forgings and castings, forcing OEMs to dual-source critical tank components. Diversification campaigns and near-shoring initiatives require multi-year capital commitments, diluting margin upside for first-tier suppliers.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Lightweight CFRP and Hybrid Tanks
- Rising Retrofit Demand for Auxiliary/Long-Range Kits
- Stringent Certification and Fire-Safety Testing Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
External tanks record the fastest 3.9% CAGR as militaries prioritize drop-tanks, conformal systems, and buddy-pod refuelers that can be jettisoned or detached when tactical needs shift. Internal systems still dominate 59.12% of 2025 revenue, underscoring their space-efficiency and center-of-gravity advantages in commercial service. Eaton's 1,360-gal jettisonable units showcase compliance with JP-4, JP-5, and JP-8 while offering structural provisions for supersonic carriage. The emergence of conformable shapes supports blended-wing-body demonstrators that lack traditional wing boxes. Advancements in self-sealing technology protect against incendiary rounds, while integrated fuel-quantity gauging achieves sub-0.25% accuracy through digital probes.
Growth pivots to emerging hybrid fighter missions demanding stealth and ferry range, compelling designers to blend internal bays with low-observable external pods. Bladder-based auxiliary kits reinforce aftermarket momentum, letting airlines field range-extension packages without structural re-certification. Active-health-monitoring sensors feed prognostic algorithms that schedule maintenance windows before leaks propagate. Thus, even as the aircraft fuel tank market size remains, internal systems and external tank innovation deliver a disproportionate share of incremental revenue.
Carbon-fiber composites captured 40.95% of 2025 revenue, driven by weight savings of 15-35 kg per short-haul aircraft, translating into multi-million-dollar lifetime fuel burn reductions. Hybrid cryogenic structures clock a 5.28% CAGR as hydrogen roadmaps crystallize around mid-2030s entry-into-service. Linerless Type V tanks promise 40% additional weight savings but face micro-crack propagation issues under high-cycle pressure loads. Metallic alloys such as aluminum-lithium retain relevance where proven fracture toughness is paramount, especially in wing integral tanks for wide-bodies. Polymer-based bladders continue to service retrofit demand thanks to installation speed and lower capital requirements.
Automated Fiber Placement couples ultrasonic welding to create liquid-tight seams, a prerequisite for cryogenic LH2. Hybrid configurations mesh titanium liners with carbon overwraps, allowing linerless concepts to mature. Embedded fiber-optic sensors track strain and temperature in real time, enabling predictive maintenance business models. Consequently, while composites dominate value today, the aircraft fuel tanks market share of hybrid and smart-material solutions will continue to climb.
Complete Report Scope:
- By Type
- Internal (Integral, Bladder, Self-sealing)
- External (Drop, Conformal, Buddy-Pods)
- By Material
- Metallic Alloys (Al-Li, Ti)
- Carbon-Fiber Composites
- Polymer/Elastomer Bladders
- Hybrid and Next-Gen Cryogenic
- By Platform
- Commercial Aircraft
- Military Aircraft
- General Aviation Aircraft and Business Jets
- By End Use
- OEM
- Aftermarket/Retrofit
- By Region
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led with 35.05% of 2025 revenue on the back of Boeing's high-volume B737 and B787 lines, plus the US Air Force's tanker recapitalization roadmap. The KC-46A program, despite schedule slips, validates advanced inert-ing and boom-refueling tanks capable of 1,200 gallons-per-minute offload rates. Washington's policy focuses on reshoring titanium and aluminum value chains and aims to defuse geopolitical risk from Russia and China. The Biden administration's 2025 Inflation Reduction Act credits hydrogen-aircraft demonstrators, catalyzing early LH2 tank R&D funding
Asia-Pacific posts the highest 5.07% CAGR as China seeks to double its commercial fleet by 2043, demanding more than 8,000 single-aisle aircraft that will ship with integral carbon-fiber tanks. COMAC C919 deliveries reached 10 aircraft by end-2024, stimulating home-grown subsystem ecosystems. India's 8.3% annual passenger growth underpins high-seat-count narrow-body orders, while its Make-in-India scheme lures fuel-system joint ventures such as Safran-HAL for LEAP engine parts. Defense spending, accounting for 42% of global imports, demands multirole tankers and conformal solutions on revamped fighter fleets.
Europe's share edges forward on steady Airbus output and collaborative defense projects like the eight-unit MRTT fleet delivered out of the Netherlands. EASA's RefuelEU mandate requires 2% SAF blending in 2025, scaling to 70% by 2050, compelling tank upgrade paths for fuel-property variability. Regional R&D clusters in Sweden and France invest heavily in cryogenic demonstrators, exemplified by GKN's 5,000 m2 expansion in Trollhattan that integrates AFP cells and digital twins. Brexit-driven customs frictions dampen UK suppliers' competitiveness, yet targeted investments by Spirit AeroSystems shore up critical-structure capacity. Overall, geographical demand shifts make Asia-Pacific the volume growth leader while North America remains the technology bellwether.
- Safran SA
- Meggitt PLC (Parker-Hannifin Corporation)
- Eaton Corporation plc
- Robertson Fuel Systems LLC
- Aero Tec Laboratories Ltd.
- GKN Aerospace (Melrose plc)
- Elbit Systems Ltd.
- Marshall Group
- Applied Aerospace Structures Corporation
- Collins Aerospace (RTX Corporation)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Commercial aircraft production up-cycle
- 4.2.2 Defense fleet modernization programs
- 4.2.3 Adoption of lightweight CFRP and hybrid tanks
- 4.2.4 Rising retrofit demand for auxiliary/long-range kits
- 4.2.5 Mandatory inert-gas inerting systems
- 4.2.6 Emergence of cryogenic LH2 tanks for zero-emission aircraft
- 4.3 Market Restraints
- 4.3.1 Volatile aerospace raw-material prices and supply chain risk
- 4.3.2 Stringent certification and fire-safety testing requirements
- 4.3.3 High R&D and tooling CAPEX for composite tanks
- 4.3.4 Sub-100-seat electric aircraft reducing future tank demand
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Internal (Integral, Bladder, Self-sealing)
- 5.1.2 External (Drop, Conformal, Buddy-Pods)
- 5.2 By Material
- 5.2.1 Metallic Alloys (Al-Li, Ti)
- 5.2.2 Carbon-Fiber Composites
- 5.2.3 Polymer/Elastomer Bladders
- 5.2.4 Hybrid and Next-Gen Cryogenic
- 5.3 By Platform
- 5.3.1 Commercial Aircraft
- 5.3.2 Military Aircraft
- 5.3.3 General Aviation Aircraft and Business Jets
- 5.4 By End Use
- 5.4.1 OEM
- 5.4.2 Aftermarket/Retrofit
- 5.5 By Region
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 France
- 5.5.2.3 Germany
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 UAE
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Safran SA
- 6.4.2 Meggitt PLC (Parker-Hannifin Corporation)
- 6.4.3 Eaton Corporation plc
- 6.4.4 Robertson Fuel Systems LLC
- 6.4.5 Aero Tec Laboratories Ltd.
- 6.4.6 GKN Aerospace (Melrose plc)
- 6.4.7 Elbit Systems Ltd.
- 6.4.8 Marshall Group
- 6.4.9 Applied Aerospace Structures Corporation
- 6.4.10 Collins Aerospace (RTX Corporation)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


