

|
시장보고서
상품코드
2123354
인유두종바이러스(HPV) 백신 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Human Papillomavirus Vaccine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 인유두종바이러스(HPV) 백신 시장 규모는 2025년에 89억 8,000만 달러로 평가되었고 2026년 97억 3,000만 달러에서 2031년까지 145억 9,000만 달러에 이를 것으로 추정되고 있어 예측 기간(2026-2031년) CAGR은 8.39%를 나타낼 전망입니다.
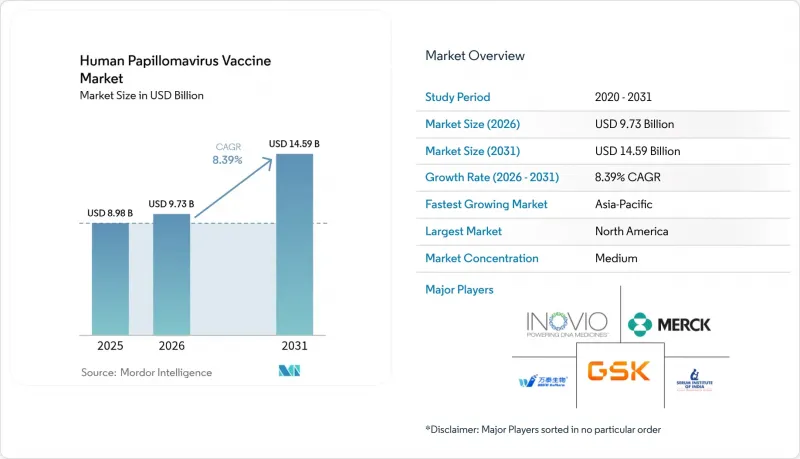
본 보고서는 백신 유형(2가, 4가 등), 적응증(자궁경부암, 항문암, 음경암 등), 유통 채널(공공·민간), 연령대(성인·소아), 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러)으로 표시되어 있습니다.
전 세계 인유두종바이러스(HPV) 백신 시장 동향 및 인사이트
새로운 다가 HPV 백신의 승인
최근, 두경부암 예방을 목적으로 한 가다실 9가 FDA(미국 식품의약국)의 승인을 받음에 따라, 그 예방 범위는 부인과계 악성 종양을 넘어 확대되어 성인 남성 시장으로의 진출이 가능해졌습니다. 머크(Merck) 및 여러 아시아 개발 기업들은 아프리카와 동남아시아에서 빈번하게 발견되는 HPV 유형을 대상으로 한 차세대 다가 백신 후보 물질을 개발하고 있으며, 이는 인유두종바이러스(HPV) 백신 시장의 프리미엄 부문을 강화하고 있습니다. WHO의 파이프라인 리뷰에는 20종 이상의 치료용 백신이 등재되어 있어, 예방과 치료라는 두 가지 접근 방식이 향후 융합될 것임을 시사하고 있습니다. 이러한 혁신은 종합적으로 판매량 성장을 뒷받침하고 지역 간 가격 차별화를 촉진할 것입니다.
정부 및 다자간 기구의 자금 지원 촉진
인도의 2024년도 예산에서는 국내 생산된 Cervavac을 민간 부문에 1회분당 24달러에 공급하는 전국적인 여아 대상 프로그램에 자금이 배정되어, 인유두종바이러스(HPV) 백신 시장에서 사상 최대 규모의 단일 시장 확대를 가져왔습니다. Gavi의 6억 달러 기부 약속과 2013년 이후 유니세프의 누적 9,300만 회분 이상의 조달을 통해 안정적인 수요 전망이 확립되었으며, 아시아 및 라틴아메리카에서의 생산 능력 확충이 정당화되었습니다. 2025년에 PAHO 산하에서 체결될 유사한 협정을 통해 지역 전체의 수주량이 더욱 증가하여 단가 인하와 접근성 확대가 도모될 것입니다.
엄격한 생물학적 제제 규제
복잡한 생물학적 제제 규제 체계에서는 철저한 안전성 및 유효성 데이터가 요구되며, 이로 인해 후보 제품 1건당 개발 비용이 10억 달러를 초과하여 지역 제조업체의 승인 획득이 지연되고 있습니다. 유럽의약품청(EMA)에 제출하는 신청 서류는 규정 준수 부담을 가중시키지만, 다자간 입찰에서는 여전히 WHO의 사전 승인이 필수적입니다. 이러한 중첩된 규제로 인해 시장 출시까지의 기간이 길어지고, 풍부한 자본을 보유한 기존 기업들이 우위를 점하게 되어, 인유두종바이러스(HPV) 백신 시장에서 소규모 신규 진출기업의 성장이 억제되고 있습니다.
부문 분석
2025년에도 4가 백신은 66.85%의 점유율을 유지하며, 각국의 공적 예방접종 프로그램에 광범위하게 보급되는 것을 뒷받침하고 있습니다. 이러한 확고한 입지는 예측 가능한 수익 흐름을 뒷받침하고 있지만, 고가인 9가 제품은 연평균 성장률(CAGR) 9.02%로 더 빠른 속도로 성장하고 있습니다. 북미 및 유럽에서는 지불 기관이 발암성 균주에 대한 더 광범위한 커버리지를 지지하고 있기 때문에 9가 인유두종 바이러스 백신 시장 규모가 강력하게 확대되고 있습니다. 이러한 변화는 더 광범위한 보호를 위해 비용을 지불할 의사가 있는 중산층 소비자들에게도 혜택을 주고 있지만, 한편으로 저·중소득 국가(LMIC)의 조달 기관들은 여전히 비용 대비 효과가 높은 4가 또는 2가 백신을 계속 구매하고 있습니다.
세계 임상 데이터에 따르면, 가다실 9는 자궁경부암에 대해 거의 100%의 예방 효과를 보이며, 기타 HPV 관련 질환에 대해서도 90%의 유효성을 발휘하고 있습니다. WHO의 세콜린(1회 접종) 및 발린백스(2회 접종)에 대한 사전 승인은 공급 옵션을 확대하고, 인유두종바이러스(HPV) 백신 시장의 가격에 압박을 가하고 있습니다. 앞으로 아프리카와 아시아에서 유행하는 균주에 대응하는 지역 특화형 다가 백신 후보가 등장함에 따라, 경쟁 환경은 더욱 세분화될 가능성이 있습니다.
공중 보건에 대한 꾸준한 관심과 수십 년에 걸친 검증된 데이터 덕분에, 2025년 매출의 69.25%는 자궁경부암 예방이 차지했습니다. 그러나 성별을 불문하는 정책으로 인해 남성의 질병 부담이 증가하고 있다는 점이 인식되면서, 항문암 예방 부문의 성장률이 연평균 성장률(CAGR) 9.08%로 가장 빠르게 증가하고 있습니다. 자궁경부암 이외의 적응증이 중요성을 더해감에 따라, 자궁경부암 예방 분야의 인유두종바이러스(HPV) 백신 시장 점유율은 서서히 감소하겠지만, 절대적인 매출액은 계속해서 증가할 전망입니다.
FDA가 가다실 9의 두경부암 적응증을 확대한 것은 여성 중심의 적응증을 넘어선 시장 확대를 뒷받침하는 것이며, 성인을 대상으로 한 보완 접종 프로그램의 지침이 될 것입니다. 검토를 거친 데이터에 따르면, 남성의 중인두암 발생률이 증가하고 있으며, 이는 전 세계적인 정책 재검토를 촉진하고 있습니다. 이에 따라 각 제약사는 남녀 모두에게 어필할 수 있는 종합적인 암 예방을 위한 가치 제안을 향해 방향을 전환하고 있습니다.
지역별 분석
북미의 39.12%라는 점유율은 조기 도입, 광범위한 보험 적용, 그리고 지속적인 성 중립적 추가 접종 이니셔티브를 반영하고 있습니다. 미국에서는 여전히 지불과 관련된 격차가 나타나고 있지만, 캐나다가 2024년에 9-20세를 대상으로 1회 접종을 권장한 것은 이 나라를 정책의 선도자로 자리매김하게 했습니다. 멕시코가 PAHO(범미보건기구)의 근절 로드맵에 참여한 것은 이 하위 지역 전체의 가격 책정 및 조달에 있어 시너지 효과를 약속하는 것입니다.
아시아태평양은 인도의 여아 대상 전액 공비 부담 프로그램과 서유럽 기존 제조업체들에 도전하는 중국 국내 제조업체들의 부상으로 연평균 성장률(CAGR) 8.98%를 기록하며 성장을 주도하고 있습니다. 머크(Merck)의 2025년 1분기 중국 매출이 41% 감소한 것은 가격 경쟁의 심화와 규제의 복잡성을 여실히 드러내고 있습니다. 일본의 남녀 대상 9가 백신 전환과 호주의 성숙한 근절 전략은 이 지역 전체의 인유두종바이러스(HPV) 백신 시장 규모를 확대하는 다양한 정책 모델의 좋은 사례가 되고 있습니다.
유럽에서는 EU4Health 기금의 2,000만 유로 지원을 바탕으로, 여아 접종률 90% 달성 및 남아에 대한 접종 의무 확대를 통해 정책 혁신이 계속되고 있습니다. 경쟁 입찰을 통해 공급 안정성을 해치지 않으면서도 합리적인 가격을 유지하고 있습니다. 중동 및 아프리카에서는 콜드체인이나 백신 접종에 대한 주저함 같은 장벽에 직면해 있지만, 나이지리아가 2024년부터 2025년까지 770만 명의 여아를 대상으로 한 접종 추진에 나서고 있다는 점은 지역 사회 중심의 노력을 통해 높은 이용률을 확보할 수 있음을 보여줍니다. 남미에서는 PAHO(범미보건기구)와 스페인 기관 간의 2025년 파트너십을 통해 9가 백신에 대한 접근성이 향상되고 있으나, 대륙 전체의 경제적 상황 차이로 인해 단계적인 도입이 필요합니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the human papillomavirus vaccine market size was valued at USD 8.98 billion in 2025 and estimated to grow from USD 9.73 billion in 2026 to reach USD 14.59 billion by 2031, at a CAGR of 8.39% during the forecast period (2026-2031).
This report is Segmented by Vaccine Type (Bivalent, Quadrivalent, and More), Indication (Cervical Cancer, Anal Cancer, Penile Cancer, and More), Distribution Channel (Public and Private), Age Group (Adults and Pediatric) and Geography (North America, Europe, Asia-Pacific, and More). The Market and Forecasts are Provided in Terms of Value (USD).
Global Human Papillomavirus Vaccine Market Trends and Insights
Approval of New Multivalent HPV Vaccines
Recent FDA clearance of Gardasil 9 for head-and-neck cancer prevention extends protective reach beyond gynecological malignancies and opens male adult segments. Merck and several Asian developers are advancing next-generation multivalent candidates aimed at HPV types highly prevalent in Africa and South-East Asia, reinforcing the premium tier of the human papillomavirus vaccine market. WHO's pipeline review lists more than 20 therapeutic vaccines, signalling future convergence of preventive and therapeutic modalities . Collectively, these innovations underpin volume growth and encourage price differentiation across regions.
Government & Multi-Lateral Funding Accelerators
India's 2024 budget funded a national girls' program using locally produced Cervavac at USD 24 per private-sector dose, creating the largest single expansion in the human papillomavirus vaccine market. Gavi's USD 600 million commitment and UNICEF's aggregate procurement surpassing 93 million doses since 2013 provide stable demand forecasts that justify capacity builds in Asia and Latin America . Similar agreements under PAHO in 2025 further aggregate regional orders, lowering unit cost and widening access.
Stringent Biologics Regulations
Complex biologics frameworks require exhaustive safety and potency data, driving development costs above USD 1 billion per candidate and delaying approvals for regional manufacturers. European Medicines Agency dossiers add another tier of compliance, while WHO prequalification remains essential for multilateral tenders. These layers heighten time-to-market and favor incumbents with deep capital reserves, tempering the growth of smaller entrants in the human papillomavirus vaccine market.
Other drivers and restraints analyzed in the detailed report include:
- Gender-Neutral Immunization Policies
- One-Dose Schedule Endorsed By WHO
- Vaccine Hesitancy & Misinformation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Quadrivalent vaccines retained 66.85% share in 2025, underpinning broad national program penetration. Their entrenched status supports predictable revenue flow, yet premium-priced nonavalent products are outpacing at a 9.02% CAGR. The human papillomavirus vaccine market size for nonavalent offerings is expanding strongly in North America and Europe as payers endorse wider oncogenic strain coverage. This shift also benefits middle-income consumers willing to pay for broader protection, even while procurement agencies in LMICs continue purchasing cost-efficient quadrivalent or bivalent doses.
Global clinical evidence shows Gardasil 9 delivering near-universal cervical cancer protection and 90% efficacy against other HPV-related conditions. WHO prequalification of Cecolin for single-dose schedules and Walrinvax for two-dose regimes broadens supply options, pressuring price points in the human papillomavirus vaccine market. Looking forward, region-specific multivalent candidates designed for African and Asian strain prevalence may further fragment the competitive field.
Cervical cancer prevention accounted for 69.25% of 2025 revenue thanks to entrenched public-health focus and decades of supportive data. Yet anal cancer prevention is rising fastest at 9.08% CAGR because gender-neutral policies recognize growing male disease burden. The human papillomavirus vaccine market share for cervical applications will gradually erode as non-cervical indications gain prominence, though absolute revenues continue growing.
FDA extension of Gardasil 9 to head-and-neck cancers validates expansion beyond female-centric indications and informs adult catch-up programs. Peer-reviewed data reveal a rising incidence of oropharyngeal cancer among men, catalyzing policy updates worldwide. Manufacturers are therefore repositioning value propositions toward comprehensive cancer prophylaxis that appeals to both sexes.
Complete Report Scope:
- By Vaccine Type
- Bivalent
- Quadrivalent
- Nonavalent
- By Indication
- Cervical Cancer
- Anal Cancer
- Penile Cancer
- Oropharyngeal Cancer
- Genital Warts
- Others
- By Distribution Channel
- Public
- Private
- By Age Group
- Adults
- Pediatric
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America's 39.12% share reflects early adoption, broad insurance coverage, and ongoing gender-neutral catch-up initiatives. The United States still shows payment-linked gaps, yet Canada's 2024 single-dose recommendation for those aged 9-20 positions it as a policy bellwether. Mexico's participation in PAHO's elimination roadmap promises synergies in pricing and procurement across the sub-region.
Asia-Pacific leads growth at a 8.98% CAGR, propelled by India's fully funded girls' program and China's surge of domestic producers challenging Western incumbents. Merck's 41% Q1-2025 sales decline in China highlights intensifying price competition and regulatory complexity. Japan's shift to 9-valent vaccines for boys and girls, together with Australia's mature elimination strategy, illustrates the diversity of policy models that collectively enlarge the human papillomavirus vaccine market size across the region.
Europe continues policy innovation through its 90% female coverage and expanding male vaccination mandate, underwritten by EUR 20 million in EU4Health funds. Competitive tenders sustain affordability without compromising supply security. The Middle East and Africa face cold-chain and hesitancy barriers, yet Nigeria's 2024-2025 drive to reach 7.7 million girls shows that community-centric engagement can secure high utilization. In South America, PAHO's 2025 partnership with Spanish agencies enhances access to 9-valent vaccines, while differential economics across the continent necessitate phased rollouts.
- Merck
- GlaxoSmithKline
- Serum Institute of India Pvt Ltd
- Walvax Biotechnology Co. Ltd
- Bharat Biotech
- Innovax (Xiamen Innovax Biotech)
- Wantai BioPharm
- Sinovac Biotech
- INOVIO Pharmaceuticals
- Novartis
- AstraZeneca
- Dynavax Technologies
- CSL Seqirus
- Shenzhen Kangtai Biological
- Pfizer
- Sanofi
- VBI Vaccines
- Geneos Therapeutics
- Takeda Pharmaceuticals
- Daiichi-Sankyo
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Approval of New Multivalent HPV Vaccines
- 4.2.2 Government & Multi-Lateral Funding Accelerators
- 4.2.3 Gender-Neutral Immunization Policies
- 4.2.4 Rising HPV-Linked Cancer Incidence
- 4.2.5 One-Dose Schedule Endorsed By WHO
- 4.2.6 Emergence of LMIC-Based Vaccine Manufacturers
- 4.3 Market Restraints
- 4.3.1 Stringent Biologics Regulations
- 4.3.2 Vaccine Hesitancy & Misinformation
- 4.3.3 High Procurement Cost for Mics
- 4.3.4 Cold-Chain & Last-Mile Gaps in LMICs
- 4.4 Regulatory Landscape
- 4.5 Porters Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Vaccine Type
- 5.1.1 Bivalent
- 5.1.2 Quadrivalent
- 5.1.3 Nonavalent
- 5.2 By Indication
- 5.2.1 Cervical Cancer
- 5.2.2 Anal Cancer
- 5.2.3 Penile Cancer
- 5.2.4 Oropharyngeal Cancer
- 5.2.5 Genital Warts
- 5.2.6 Others
- 5.3 By Distribution Channel
- 5.3.1 Public
- 5.3.2 Private
- 5.4 By Age Group
- 5.4.1 Adults
- 5.4.2 Pediatric
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Merck & Co., Inc.
- 6.3.2 GSK plc
- 6.3.3 Serum Institute of India Pvt Ltd
- 6.3.4 Walvax Biotechnology Co. Ltd
- 6.3.5 Bharat Biotech
- 6.3.6 Innovax (Xiamen Innovax Biotech)
- 6.3.7 Wantai BioPharm
- 6.3.8 Sinovac Biotech Ltd
- 6.3.9 INOVIO Pharmaceuticals
- 6.3.10 Novartis AG
- 6.3.11 AstraZeneca plc
- 6.3.12 Dynavax Technologies
- 6.3.13 CSL Seqirus
- 6.3.14 Shenzhen Kangtai Biological
- 6.3.15 Pfizer Inc.
- 6.3.16 Sanofi SA
- 6.3.17 VBI Vaccines
- 6.3.18 Geneos Therapeutics
- 6.3.19 Takeda Pharmaceutical
- 6.3.20 Daiichi-Sankyo
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


